
EB Daily Market Report - Tuesday, January 31, 2023
Executive Market Summary
- Futures were down overnight, but strengthened into the opening bell
- Our major indices opened slightly higher and we've trended higher throughout the day
- 10 of our 11 sectors are higher, thwarted only by utilities (XLU, -0.23%)
- Consumer discretionary (XLY, +1.77%) and materials (XLB, +1.65%) are the clear leaders
- Home construction ($DJUSHB, +4.11%) is having another excellent day, with the 10-year treasury yield ($TNX) down 2 basis points to 3.53%
- Crude oil ($WTIC, +1.45%) has climbed back above $79 per barrel, but energy stocks (XLE, +0.39%) have lagged nearly every other sector
- Gold ($GOLD, +0.37%) is rallying again on the heels of a weak dollar (UUP, -0.16%); be careful with gold here, though, as the UUP is nearing major long-term support - its rising 20-month EMA
- Spotify (SPOT, +12.04%) is among the top performers today as the internet stock ($DJUSNS, +1.37%) posted strong subscriber numbers, despite missing its earnings forecast (think Netflix)
Market Outlook
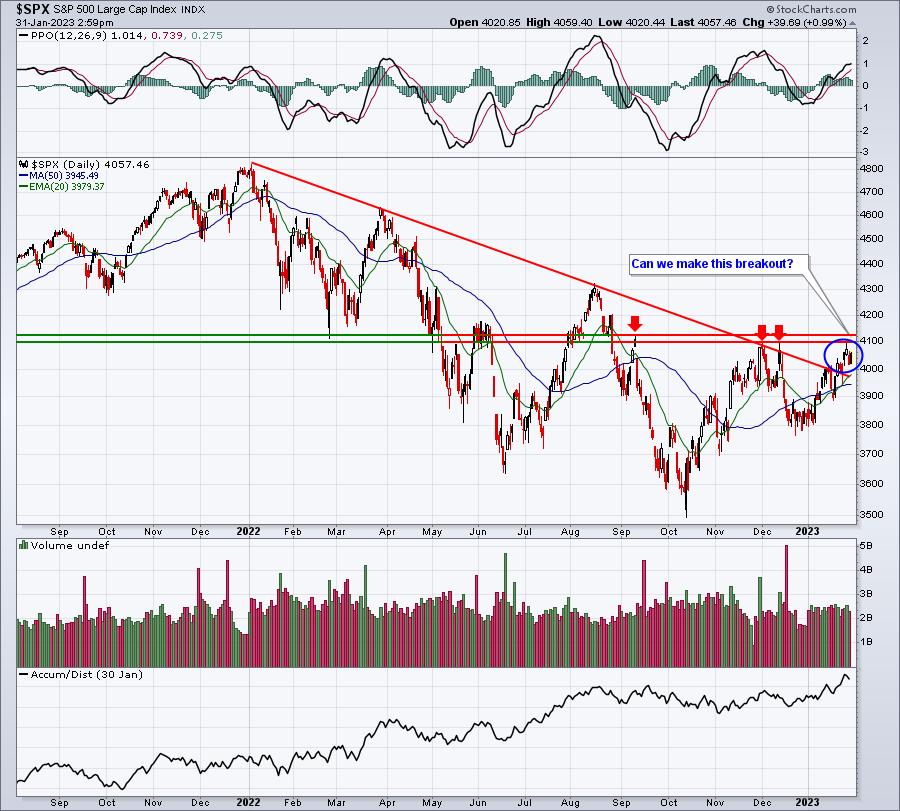
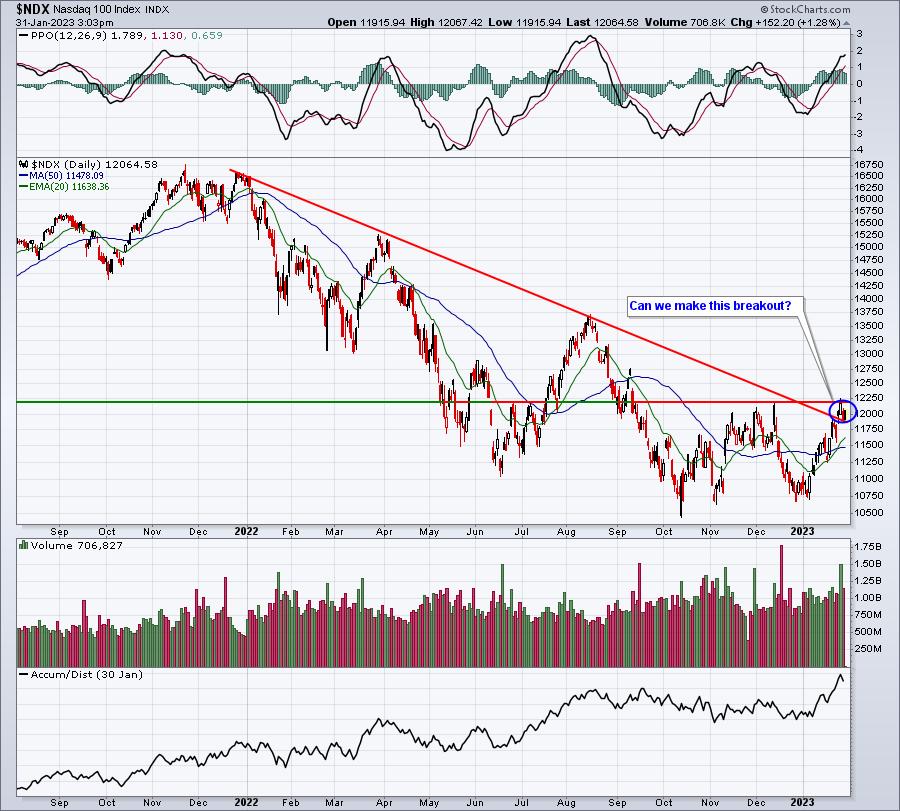
I usually look for stock prices to gravitate to either key price support or resistance as the Fed's 2pm ET policy statement approaches. 60-minute charts remain quite bullish in terms of their PPOs, so I don't see any negative divergences to worry about. Given today's strength, will we simply gravitate towards the obvious key resistance on the S&P 500 and NASDAQ 100 charts?
S&P 500:
NASDAQ 100:
Sector/Industry Focus
Volatility ($VIX) spiked on Monday and, quite honestly, it wasn't surprising at all. I'd certainly expect the potential for the VIX to increase the closer we get to a Fed announcement. That would be the market makers' best defense against increased whipsaw action - make the retail trader pay for more potential volatility, right? Well, the odd thing is that the VIX is tumbling today, down roughly 3.25% to 19.29 after hitting 20.70 earlier in the session.
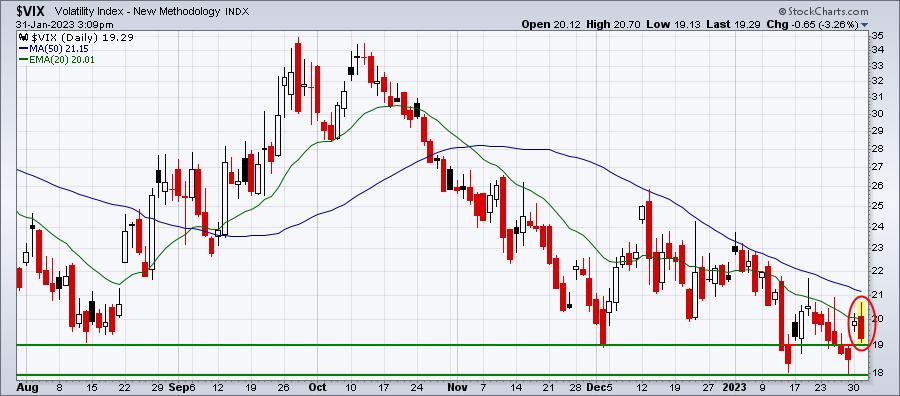
Are market makers not worried about downside action here? If so, then this is a very bullish signal, in my view. But I still want to see actual bullish price confirmation - the breakouts above 4110 on the S&P 500 and 12100-12200 on the NASDAQ 100.
ChartLists/Strategies
Personally, I've been sticking primarily with ETFs and I will head into the Fed policy statement on Wednesday with the QQQ, an ETF that tracks the growth-oriented NASDAQ 100 ($NDX). Too many individual stocks continue to see whipsaw action, making my preferred swing-trading style more difficult. I'll let you know when I begin to get a bit more aggressive. I believe we're heading higher, but we need to see key confirmed breakouts before I'll grow more aggressive.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Tuesday, January 31:
XOM, PFE, MCD, UPS, CAT, AMGN, AMD, CB, SYK, MDLZ, UBS, CP, MPC, MCO, PSX, GM EW, MSCI, SYY, EA, IMO, GLW, DOV, SPOT, IEX, SNAP, MTCH, WDC, IP, HUBB, PHM, DOX, BXP, JNPR, AOS, LII, RNR, PNR, UNM, NATI, ST, ALGM, HLI, OSK, PII, CACC, ASH, AQUA, MAN, SMCI, KEX, MMYT, OI, MRCY, APAM, MDC, CVLT
Wednesday, February 1:
META, NVO, TMO, NVS, TMUS, SONY, MO, GSK, BSX, WM, HUM, EPD, SCCO, MET, MCK, JCI, CTVA, AFL, ODFL, ALL, OTIS, ABC, FTV, ALGN, HOLX, GIB, MAA, MKL, PTC, AFG, GL, CHRW, QRVO, DT, CHX, DXC, LFUS, LSTR, MUSA, SLAB, SLM, PTON, MTH, MXL, ELF, KLIC, SITM, CCS, CSGS, EAT, VSTO, MHO, ALGT, CLB, CMC
Economic Reports
FOMC meeting begins (policy decision out on Wednesday at 2pm ET)
November Case-Shiller home price index: -0.5% (actual) vs. -0.5% (estimate)
November FHFA house price index: -0.1% (actual) vs. +0.0% (estimate)
January Chicago PMI: 44.3 (actual) vs. 45.1 (estimate)
January consumer confidence: 107.1 (actual) vs. 109.0 (estimate)
Happy trading!
Tom