
EB Daily Market Report - Tuesday, October 31, 2023
Happy Halloween!
Executive Market Summary
- Futures were higher overnight, but lost a bit of momentum heading into the opening bell
- After early morning weakness, the bulls have been back at it, with gains across all of our major indices
- The Volatility Index ($VIX, -8.25%) has tumbled for a 2nd straight day
- The 10-year treasury yield ($TNX) is flat for the session after opening quite weak
- Most commodities are lower, though natural gas ($NATGAS, +7.07%) continues its recent hot streak
- All 11 sectors are higher today, led by real estate (XLRE, +1.97%) and financials (XLF, +0.94%); consumer discretionary (XLY, +0.76%), industrials (XLI, +0.72%), and technology (XLK, +0.69%) are all leading the S&P 500
- Consumer staples (XLP, +0.28%) is the primary laggard after getting off to a fairly strong start this morning
- Arista Networks (ANET, +13.68%) is the top performer in the S&P 500 today after posting strong quarterly results; a close above 198.40 would be a breakout and ANET currently trades at 199.75 nearing the close
Market Outlook
I'm seeing very interesting action today. I'm not surprised by the gains the past two days as we've now entered the most bullish historical period of the year. But I am a bit surprised that the Volatility Index ($VIX, -8.86%) has fallen nearly 20% since last Friday's high just above 22. Given how volatility typically accelerates after a Fed announcement, I find it odd that options premiums are dropping so much just before a key announcement. Remember, market makers set premiums on options. If they're willing to price options much cheaper, is that a signal that we're likely to see the market move higher after FedSpeak? I don't know, but again I find it very interesting. Here's a quick glance at the VIX:
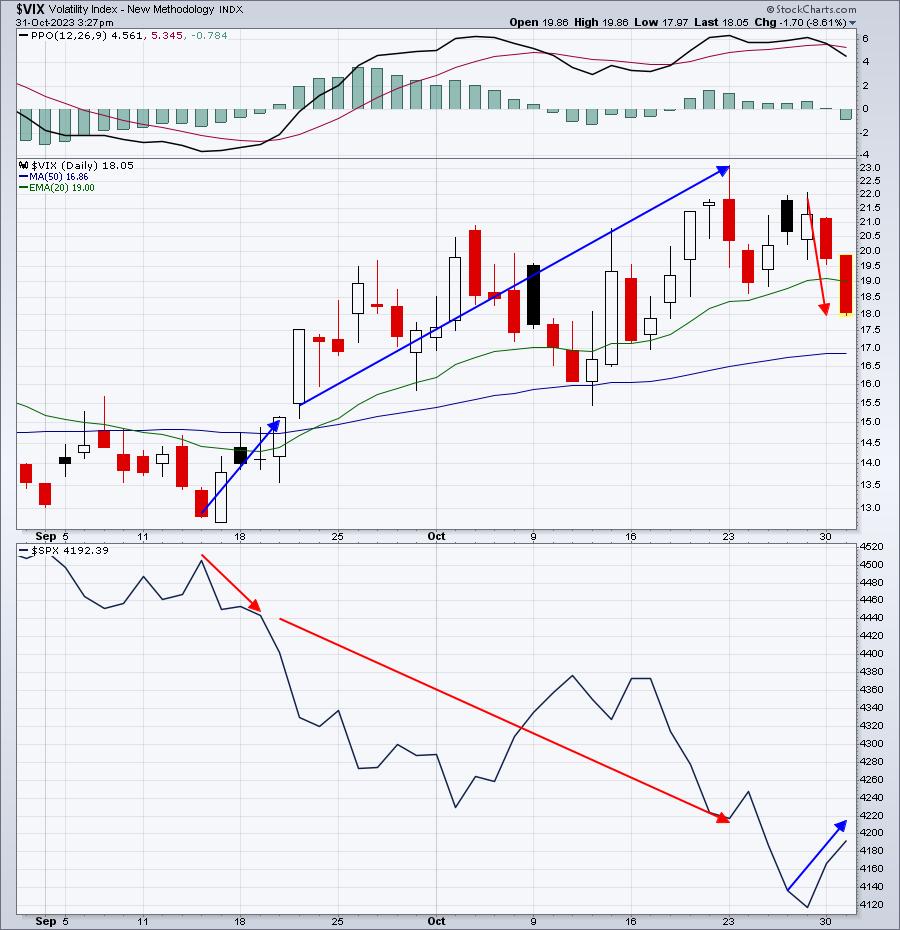
Just before the September 19-20 Fed meeting, the VIX began spiking from much lower levels. Of course, we now know history and that was just the start of the S&P 500 correction. So as we see the VIX declining rapidly heading into this Fed meeting, is this simply the start of much further gains in the S&P 500? I think it's a very good question.
Sector/Industry Focus
Growth continues to be strong on a relative basis vs. value. That is totally opposite what we saw in early 2022, before a significant cyclical bear market took shape. Think about it. If we're expecting higher inflation, slower growth (possibly even a recession), and/or higher interest rates, growth stocks should be getting clobbered. But they're not. Check out the chart, it doesn't lie:
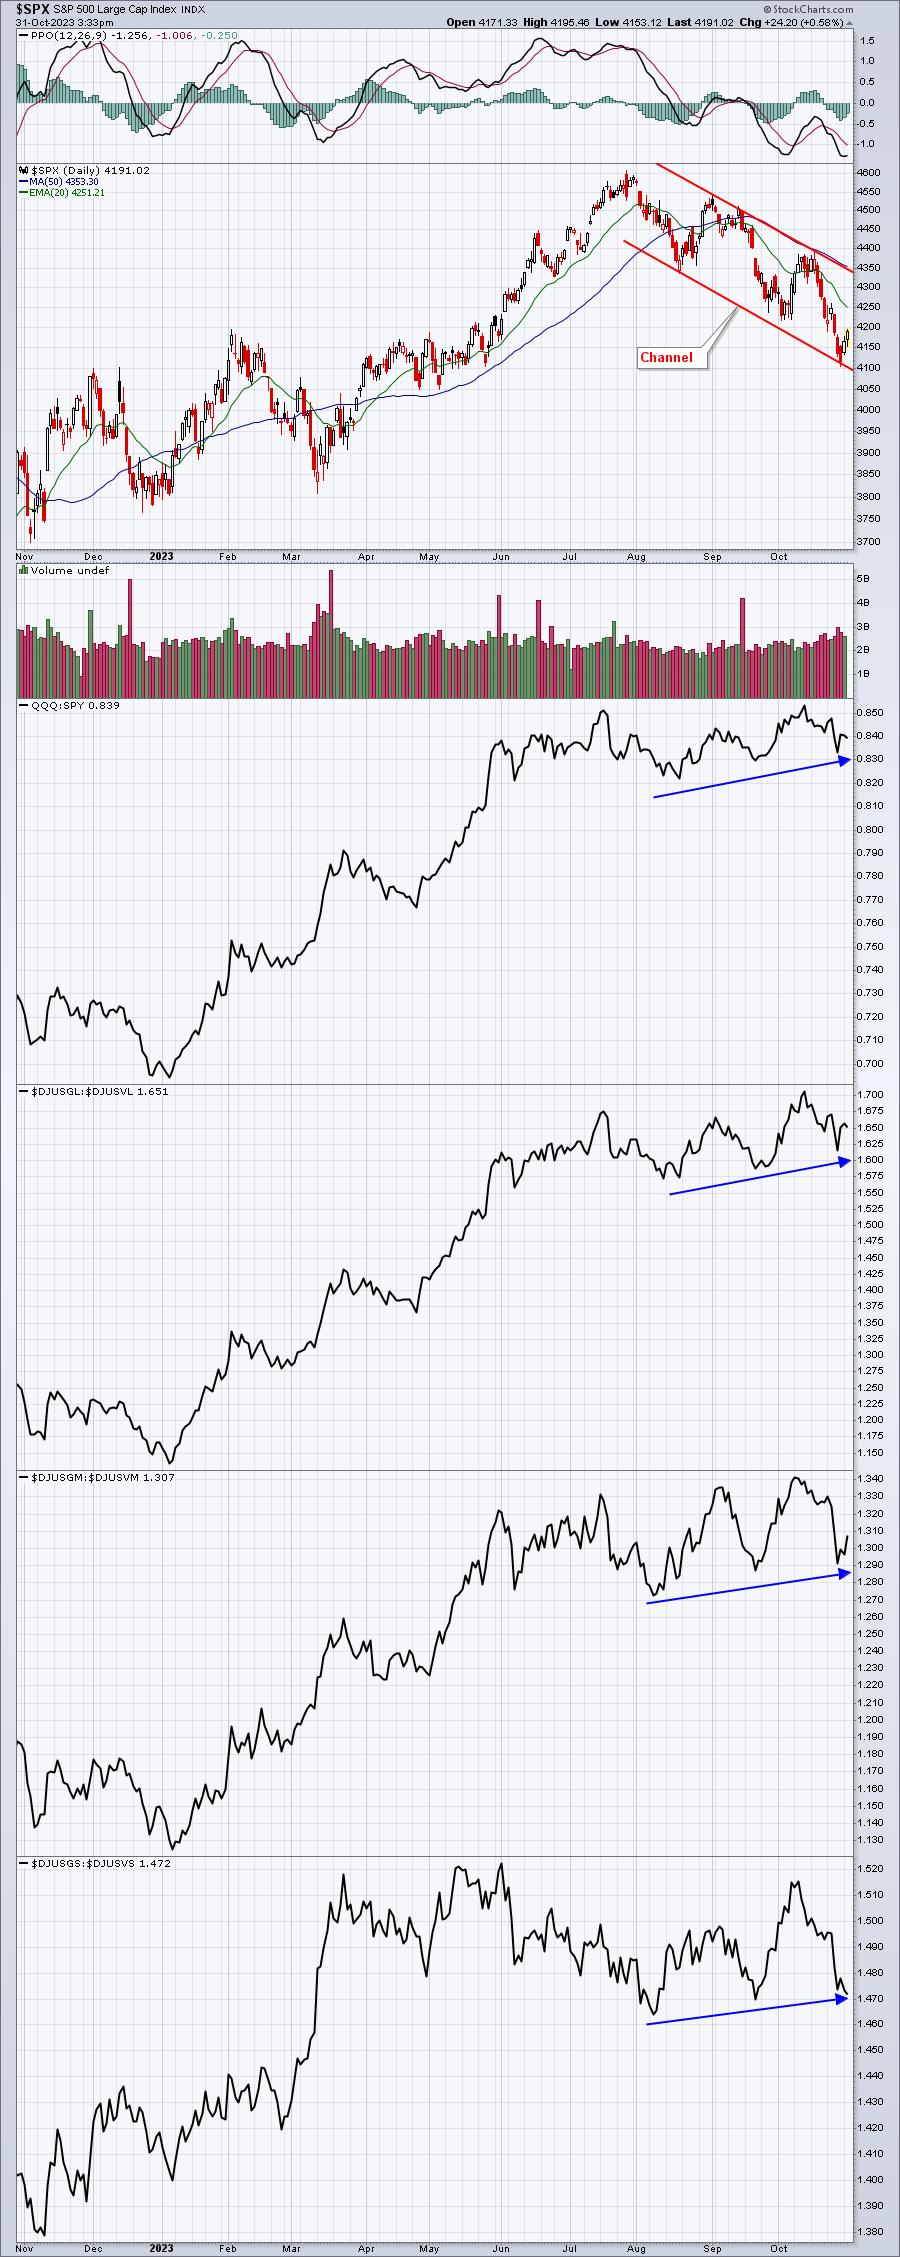
Every lower high and lower low on the S&P 500 has been met with higher highs and higher lows on the 4 growth vs. value ratios provided above. That did NOT happen in late 2021 and early 2022. Growth was hammered and this area of the market should be hammered if we're expecting higher inflation, higher interest rates, and/or slower growth (or recession). The story this chart tells me is one where the S&P 500 goes higher into year end, not lower.
Just my interpretation and opinion, of course.
ChartLists/Strategies
I'm passing on any individual trades ahead of the Fed announcement tomorrow. I don't trust this Fed AT ALL. I am, however, in ETFs tracking the NASDAQ 100 (QQQ) and Russell 2000 (IWM). That's a conservative way (for me) to trade the U.S. stock market the next couple days.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Tuesday, October 31:
PFE, AMGN, CAT, BP, BUD, ETN, EPD, MPC, BBVA, ECL, ABEV, MSCI, SYY, AME, ARES, PEG, GEHC, ARGX, GPN, WEC, YUMC, EQR, XYL, CCJ, SIRI, FSLR, HUBB, VIV, PAYC, AMCR, LDOS, INCY, CHK, BEN, ZBRA
Wednesday, November 1:
QCOM, MDLZ, CVS, ABNB, GSK, HUM, MCK, MELI, PYPL, TRI, APO, AFL, EL, MET, AIG, TT, WMB, ET, SGEN, KHC, TEL, YUM, EA, DD, IQV, IDXX, VRSK, ALL, PRU, CTSH, DASH, NTR, CDW, MLM, IR, EIX, ANSS AWK, DTE, ETR, GRMN, MKL, TS, MRO, PTC, ALB, CF, TYL, BMRN, CLX, TPL, BLDR, SMCI, APA, TRMB, EXAS, RNR, HST, GFL, WES, NI, UTHR
Economic Reports
FOMC meeting begins
Q3 employment cost index: 1.1% (actual) vs. 1.0% (estimate)
August Case-Shiller home price index: +1.0% (actual) vs. +0.7% (estimate)
August FHFA house price index: +0.6% (actual) vs. +0.8% (estimate)
October Chicago PMI: 44 (actual) vs. 45 (estimate)
October consumer confidence: 102.6 (actual) vs. 100.0 (estimate)
Happy trading!
Tom