
EB Daily Market Report - Tuesday, November 25, 2025
Executive Summary
- Futures were mixed overnight and we saw bifurcated action at the opening bell
- Small caps (IWM, +2.21%) are once again showing excellent absolute and relative strength
- The NASDAQ 100 ($NDX, +0.35%) and growth stocks (IWF, +0.50%) are higher, but definitely lagging on the session
- Health care (XLV, +2.20%) is providing the most sector strength, though consumer stocks are also strong
- Home construction ($DJUSHB, +4.93%) are helping to drive discretionary stocks (XLY, +2.04%) much higher
- Mortgage finance ($DJUSMF, +5.11%) is soaring ahead of what's now expected to be a December rate cut
- Commodities are mixed with gold ($GOLD, +0.99%) higher, while crude oil prices ($WTIC, -1.50%) drop below $58 per barrel
- Energy shares (XLE, -0.43%) dip in sympathy with the falling crude prices
- The 10-year treasury yield ($TNX) is down another 3 basis points to 4.01% as the yield moves closer to the April low near 3.90%
- Kohl's (KSS, +39.96%) is soaring after it raised its forecast; short sellers are scrambling to cover (buy) as KSS is one of the most heavily-shorted stocks
Market Outlook
Well, the bulls could not have scripted a better start to this week. During a secular bull market, the benefit of the doubt should always be given to the bulls and we're seeing why. In the middle of last week, I was nearly convinced there'd be no rate cut and I said if it did appear that a rate cut was still in order, we should expect to see explosions to the upside in key interest-rate-sensitive areas of the market like small caps (IWM), regional banks (KRE), homebuilders (XHB), and transports ($TRAN).
The following chart shows the S&P 500 and a 3-day rate of change (ROC) in the panel beneath the price chart. Also included on this chart in the panels below are 3-day ROCs in the IWM, KRE, XHB, and $TRAN:
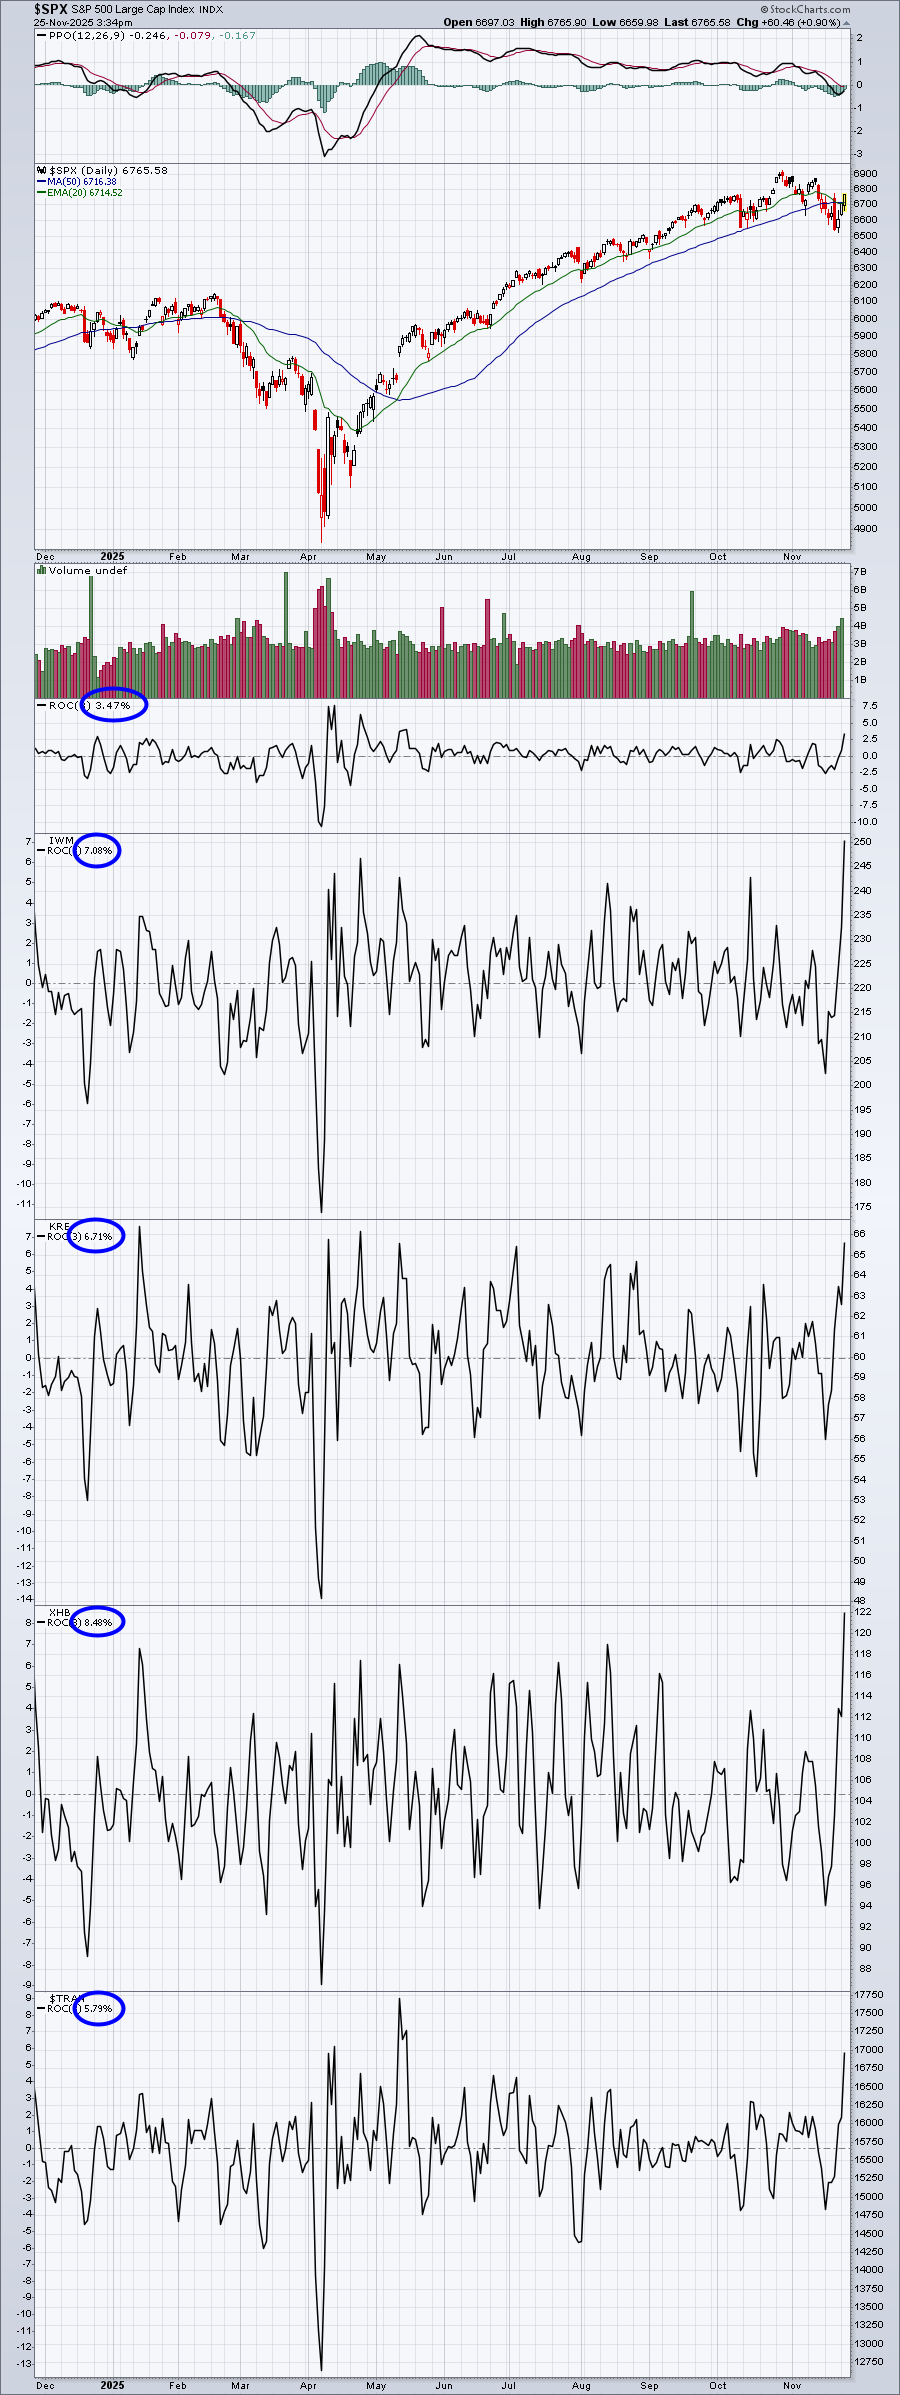
The odds of a December rate cut were approximately 30% last Wednesday. The odds are now reflected at roughly 80%. You can see that the 3-day rate of change on all of the interest-rate-sensitive groups soared. The IWM and XHB have seen their best 3-day advances in the past year. The KRE and TRAN both are close to their best 3-day advances. Wall Street had given up on a rate cut less than one week ago and now they're positioning as if it's a foregone conclusion.
This is what I'd call an excellent recovery by the bulls.
Sectors/Industries
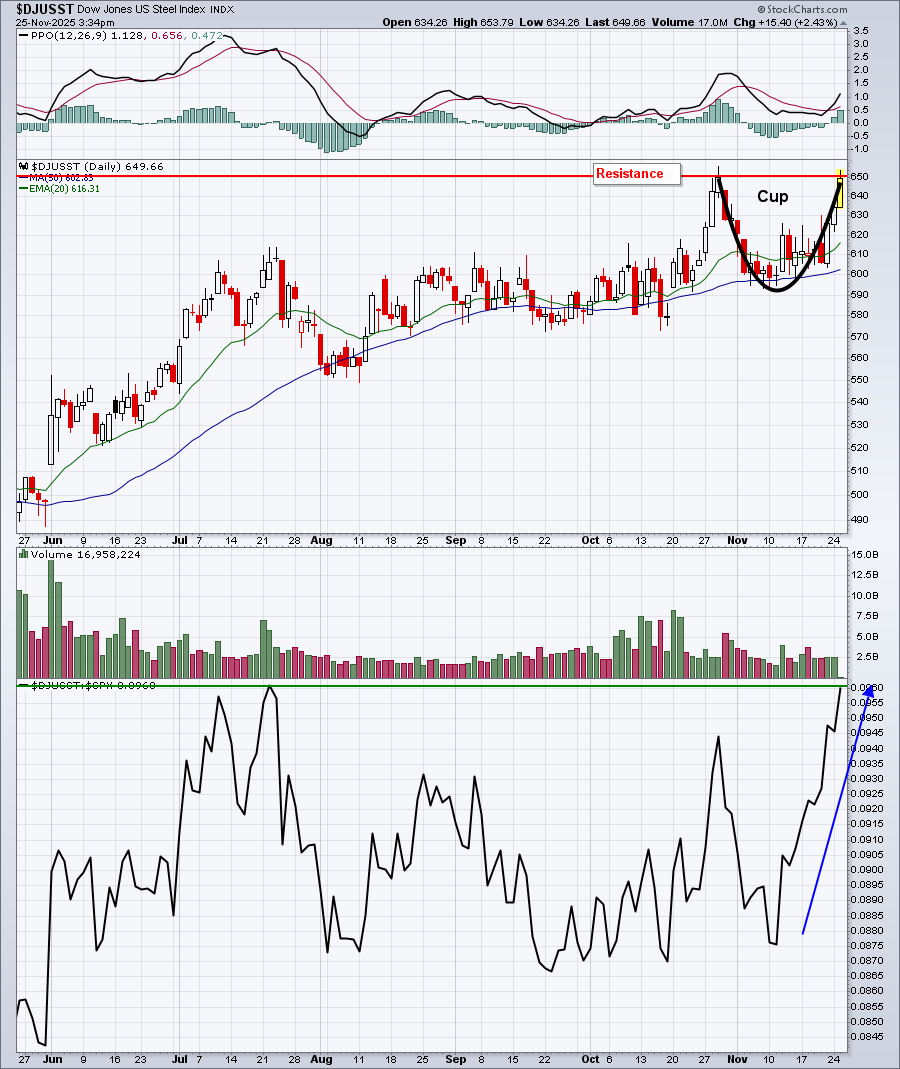
Momentum has been building in steel stocks ($DJUSST) in November and today the group is testing a key overhead resistance level. The chart appears to be in a cup with handle pattern that, ultimately, would measure to roughly 710 or so. Don't be surprised, however, if we see a short-term pullback to establish a handle:
ChartLists and Trading Strategies
Given the very bullish bounce off the 20-week EMA, I'm fine taking on new positions. First, an aggressive trade would be to enter PubMatic, Inc. (PUBM) on the recent post-earnings selloff:
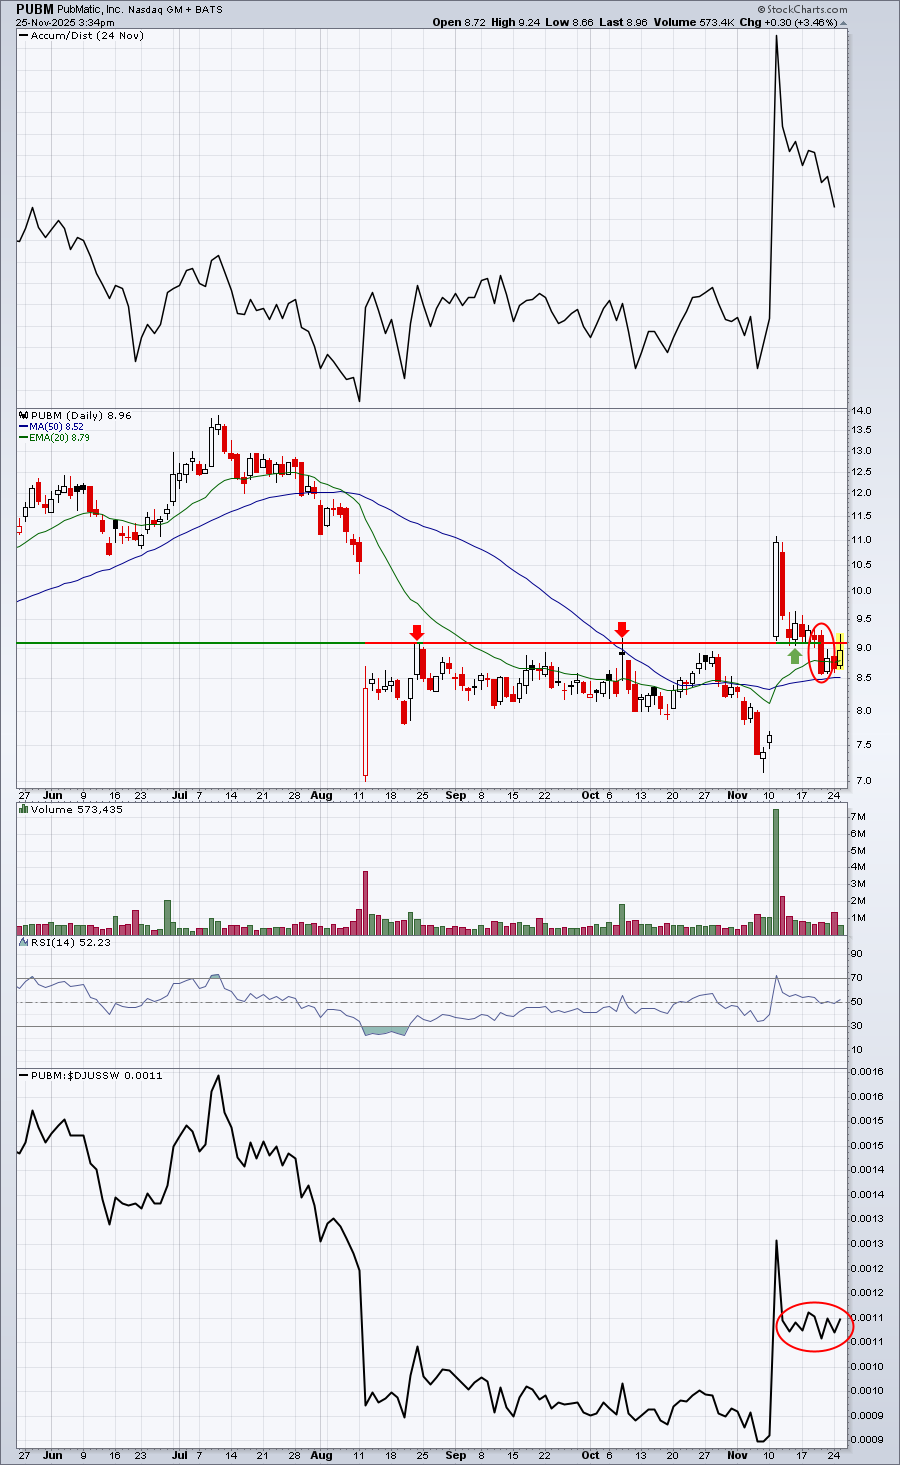
At first glance, I didn't like the red-filled candle that cleared both price support and 20-day EMA support. However, software ($DJUSSW) has been very weak, which PUBM is part of, and volume on that drop was fairly light. I'll grant it that one excuse, so long as the 50-day SMA continues to hold. PUBM soared on extremely heavy volume after earnings and I'm looking for it to push back towards its post-earnings high.
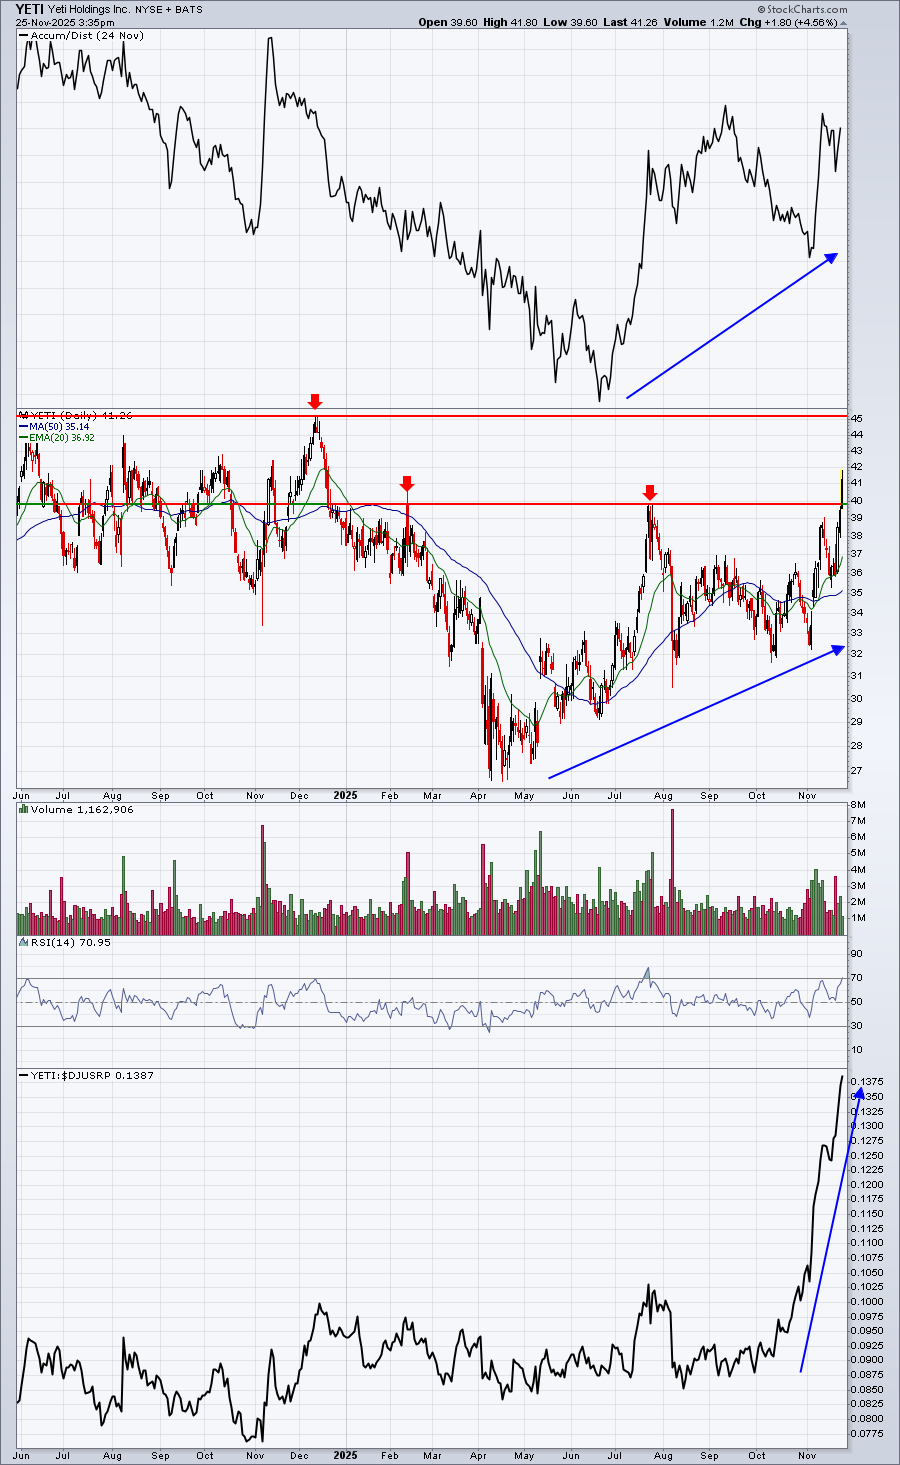
Second, I love the breakout on Yeti Holdings (YETI). I expect to see a continuing run to 45 with pullbacks contained by the rising 20-day EMA:
Upcoming Earnings
We are tracking the daily Upcoming Earnings and the Weekly Upcoming Earnings Relative Strength ChartLists for Q3 earnings. They are included on our website under ChartLists. Earnings season is winding down, but we'll continue to prepare these ChartLists for perhaps one more week.
Economic Reports
September retail sales (delayed): +0.2% (actual) vs. +0.3% (estimate)
September retail sales less autos (delayed): +0.3% (actual) vs. +0.3% (estimate)
September PPI (delayed): +0.3% (actual) vs. +0.3% (estimate)
September Core PPI (delayed): +0.1% (actual) vs. +0.3% (estimate)
September Case-Shiller home price index: 1.4% (actual) vs. 1.3% (estimate)
August business inventories (delayed): +0.0% (actual) vs. +0.1% (estimate)
November consumer confidence: 88.7 (actual) vs. 93.2 (estimate)
October pending home sales: +1.9% (actual) vs. +0.0% (estimate)
Happy trading!
Tom