
EB Daily Market Report - Thursday, March 31, 2022
Webinar Special
We occasionally offer an annual special for our service that coincides with key webinars. Until tomorrow at midnight, any of our members can take us up on our annual offer and receive a 13th month FREE. If you're currently on a 30-day trial, the 13 months will be added to the end of your trial period. You won't lose the balance of your trial period.
If you're interested in this special offer, CLICK HERE for more details.
ChartLists Updated
The Excel spreadsheet used for yesterday's "Resumption of Secular Bull Market" is now available on our website for annual members. As of this morning, there's been difficulty downloading ChartLists on the StockCharts.com platform. We've made them aware of it and they planned to look into it. In the meantime, you can view the charts on ChartLists when you attempt to download, but when you save them into your own account, all the charts are gone. Yesterday's ChartList has been added to our website and is available for download, but the issue at StockCharts will need to be fixed before you can download them successfully into your account.
I am in the process of updating several of our frequently-updated ChartLists. I should have those ready for download by tomorrow when the DMR is published.
Executive Market Summary
- Futures were modestly lower this morning as our key indices gapped down at the opening bell
- Crude oil ($WTIC, -6.51%) is down $7 per barrel to $100 after President Biden announced the released of 1 million barrels of oil per day from reserves in an effort to ease gas prices
- Cryptocurrencies are weak today, but for now bitcoin ($BTCUSD, -2.37%) remains 2% above key price support at 45,000
- Commodities are mixed with gold ($GOLD, +0.41%) rising, while silver ($SILVER, -0.25%) and copper ($COPPER, -0.27%) both drift lower
- The 10-year treasury yield ($TNX) is down 3 basis points to 2.33% as banks ($DJUSBK, -2.09%) lead financials (XLF, -1.17%) lower
- Defensive groups are showing strength as utilities (XLU, +0.59%) gain ground
- Advanced Micro Devices (AMD, -7.10%) was downgraded by Barclays, leading to underperformance in semiconductors ($DJUSSC, -0.63%)
- Renewable energy ($DWCREE, +2.45%), meanwhile, is showing strength as SolarEdge (SEDG, +4.34%) and Enphase Energy (ENPH, +4.24%) are the S&P 500's top two performers
Market Outlook
The S&P 500 is testing gap support, which I had mentioned in yesterday's DMR as a key short-term support. The 4575-4590 range is what I'd consider to be very short-term support. Holding that range into the close would provide the bulls an opportunity to regain momentum on Friday as the nonfarm payrolls number is released for March. Here's the illustration of the short-term support range:
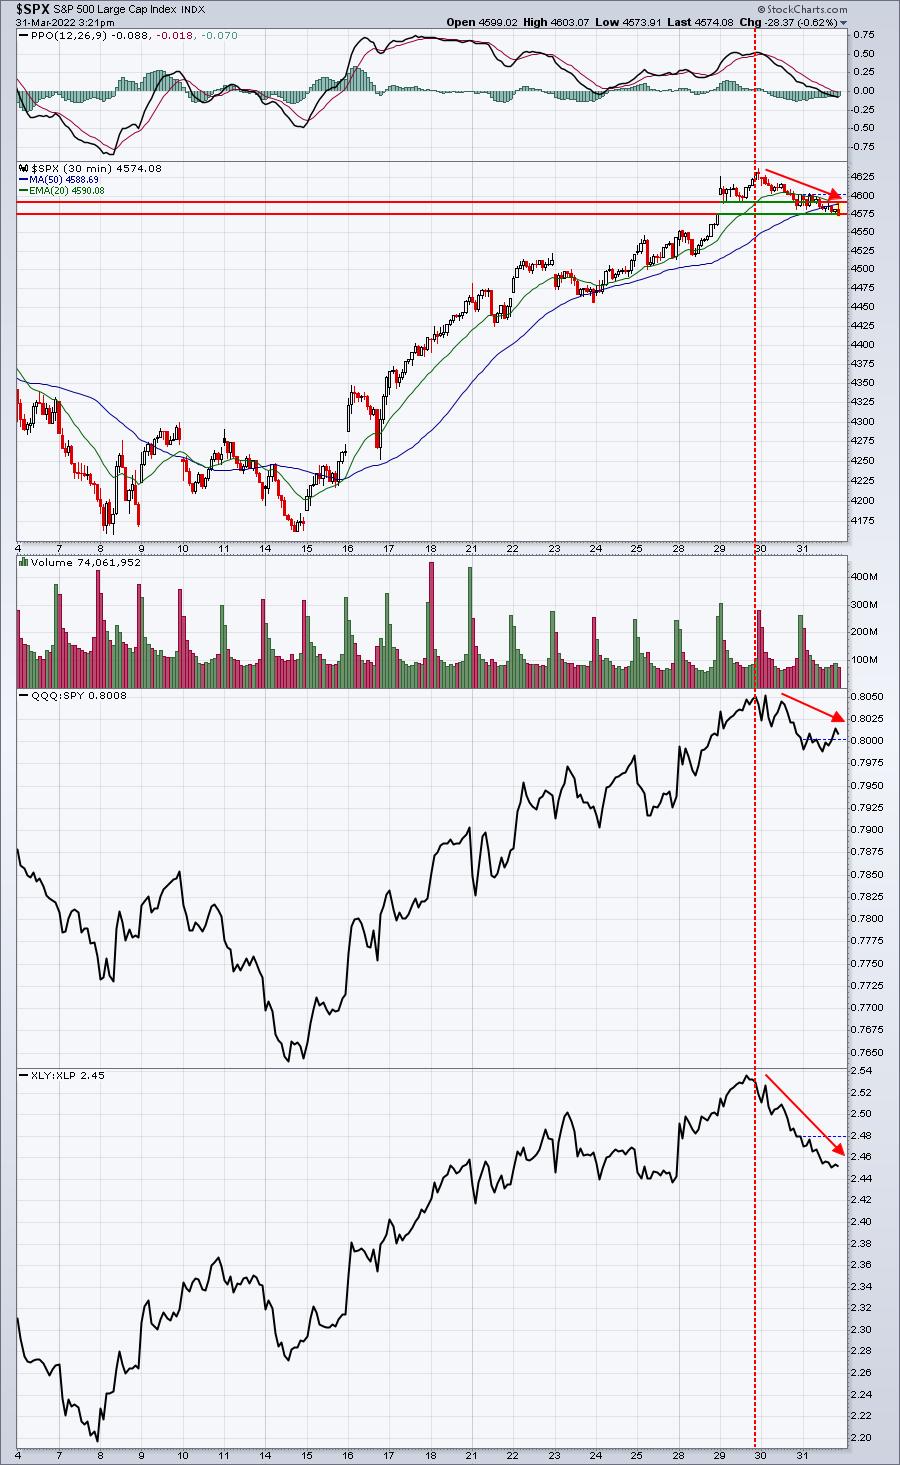
Over the past two days, prices have eroded and so too has the relative strength of both the XLY:XLP and QQQ:SPY. Right now, I'd consider this to be mostly just profit taking, though we know technically the significance of further selling. That would likely trigger more volatility, with the VIX up 6.57% to 20.60 at last check. As the VIX rises, so too can the selling acceleration.
Sector/Industry Focus
The weakness in home improvement retailers ($DJUSHI) continues. We're breaking below the recent price low and appear poised to test the 52-week low soon:
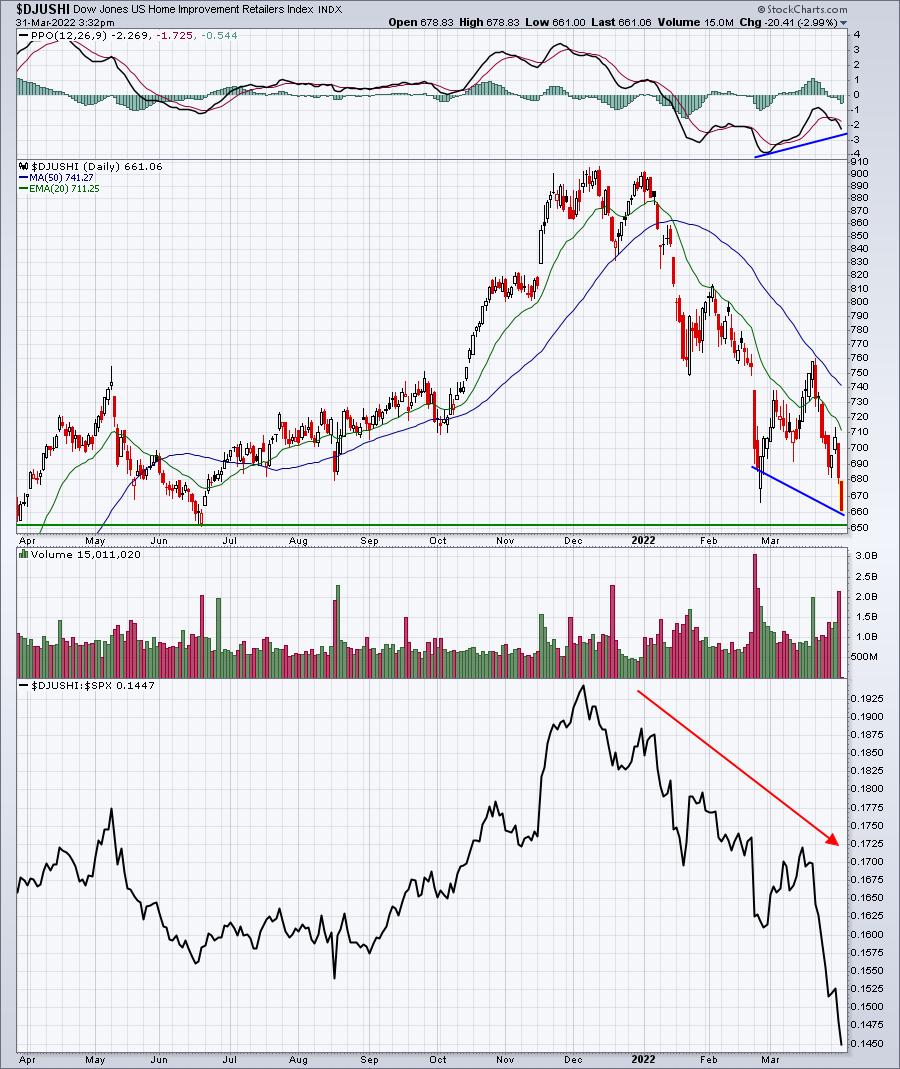
One thing I do like about this chart is the nearly certain positive divergence that'll be in place when the ultimate bottom is reached. I think it could happen when it tests the low from June. Stay tuned.
ChartLists/Strategies
Yesterday's featured stock here was McCormick & Co. (MKC). It's a stock on our Strong AD ChartList (SADCL) and the strategy of looking at these stocks for weakness early, especially if price support is near, and afternoon strength is a sound one. Like any other trade, stops need to be considered and they certainly won't all work out the way we plan, but the reason stocks are on our SADCL is that they have (or had at the time of inclusion) strong AD lines. Here was one from today with weakness:
TALO:
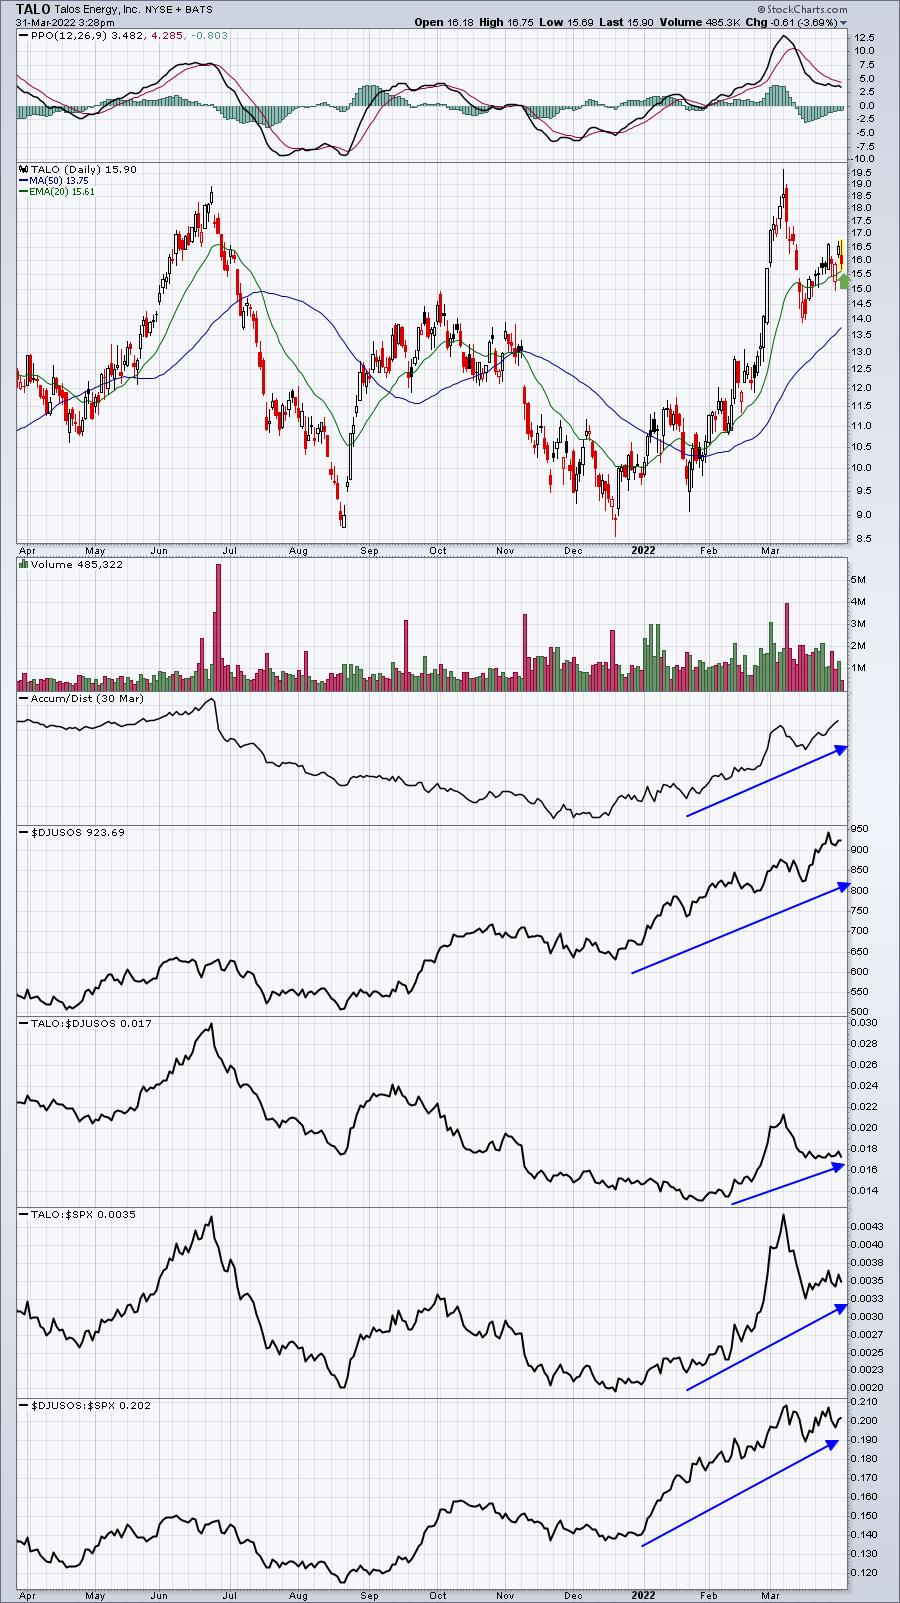
Today's volume on TALO is light, so even if it finishes at or near its low, it'll likely have little effect on an AD line that has been surging to the upside. Any weakness on Friday to challenge the recent low near 15.00 could present a nice trading opportunity.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, March 31:
WBA, BB, DCT
Friday, April 1:
None
Economic Reports
Initial jobless claims: 202,000 (actual) vs. + 195,000 (estimate)
February personal income: +0.5% (actual) vs. +0.5% (estimate)
February personal spending: +0.2% (actual) vs. +0.5% (estimate)
March Chicago PMI: 62.9 (actual) vs. 57.0 (estimate)
Happy trading!
Tom