
EB Daily Market Report - Tuesday, April 30, 2024
May Seasonality
I sent out the May Seasonality Report earlier this afternoon. I'm working on the Seasonality ChartList and hope to have available on our website later this evening or early tomorrow morning. In the meantime, I do want to make everyone aware that AMD, SMCI, and CZR all report their quarterly results this afternoon after the closing bell, so their May performance, at least on the opening day, will be dictated by the initial market reaction to their earnings.
Executive Market Summary
- Futures were weak overnight and our major indices opened lower
- Selling has been mostly continuous throughout today's session
- Energy (XLE, -2.64%) is today's worst-performing sector as it says goodbye to one of its favorite seasonal months, April
- Meanwhile, leadership comes from defensive sectors like health care (XLV, -0.01%) and utilities (XLU, -0.06%); they're both down, but performing much better than the other 9 sectors
- Automobiles ($DJUSAU, -4.55%), after a very strong Monday session, are leading discretionary stocks lower
- Transportation stocks ($TRAN, -1.83%) are having another very difficult session, attempting to break beneath recent price support
- Cryptocurrencies are struggling as bitcoin ($BTCUSD, -5.08%) drops back below 60000
- Gold ($GOLD, -2.24%), normally a hedge against stock market weakness, is tumbling and now trades beneath its 20-day EMA for the first time since mid-February
- Crude oil ($WTIC, -1.14%) has fallen below $82 per barrel as most commodities move lower today
- Eli Lilly (LLY, +5.96%) is among the S&P 500 leaders after reporting strong quarterly results
Market Outlook
One ratio I'm watching closely (not just today, but going forward) is the Dow Jones U.S. Large-Cap Growth Index vs. the Dow Jones U.S. Large-Cap Value Index ($DJUSGL:$DJUSVL). I'm expecting to see solid action in large cap growth in the 4 months ahead, as that's what history tells us to expect. But first, we'll need to see more bullish technical developments to confirm:
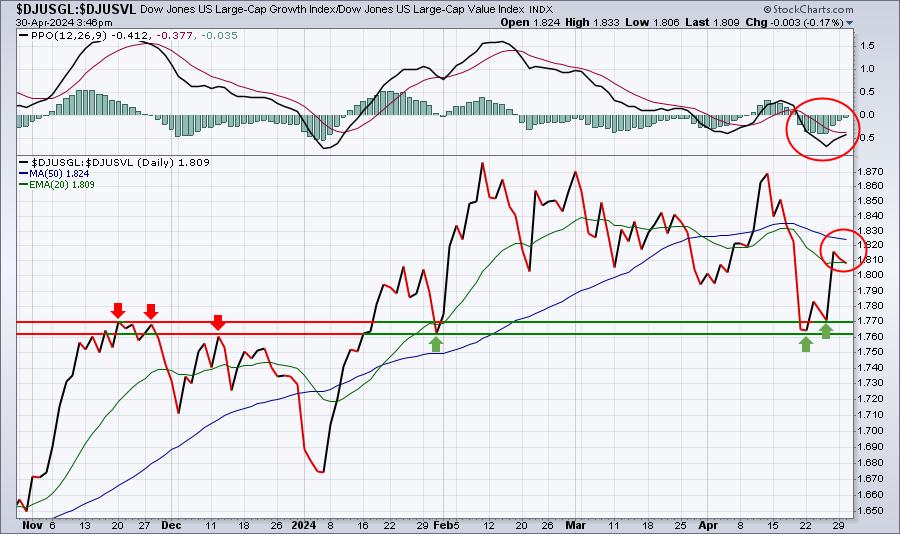
The relative PPO needs to turn positive and the relative price action needs to clear both its 20-day EMA and 50-day SMA. In the meantime, relative price support in the 1.76-1.77 area must hold on any further deterioration in this ratio.
Sector/Industry Focus
We saw two strong housing reports out this morning - Case Shiller and FHFA - but both are lagging February reports. Despite this fundamental strength, the Dow Jones U.S. Home Construction Index ($DJUSHB) is down 1.45% today, obviously more concerned with the direction of the 10-year treasury yield ($TNX):
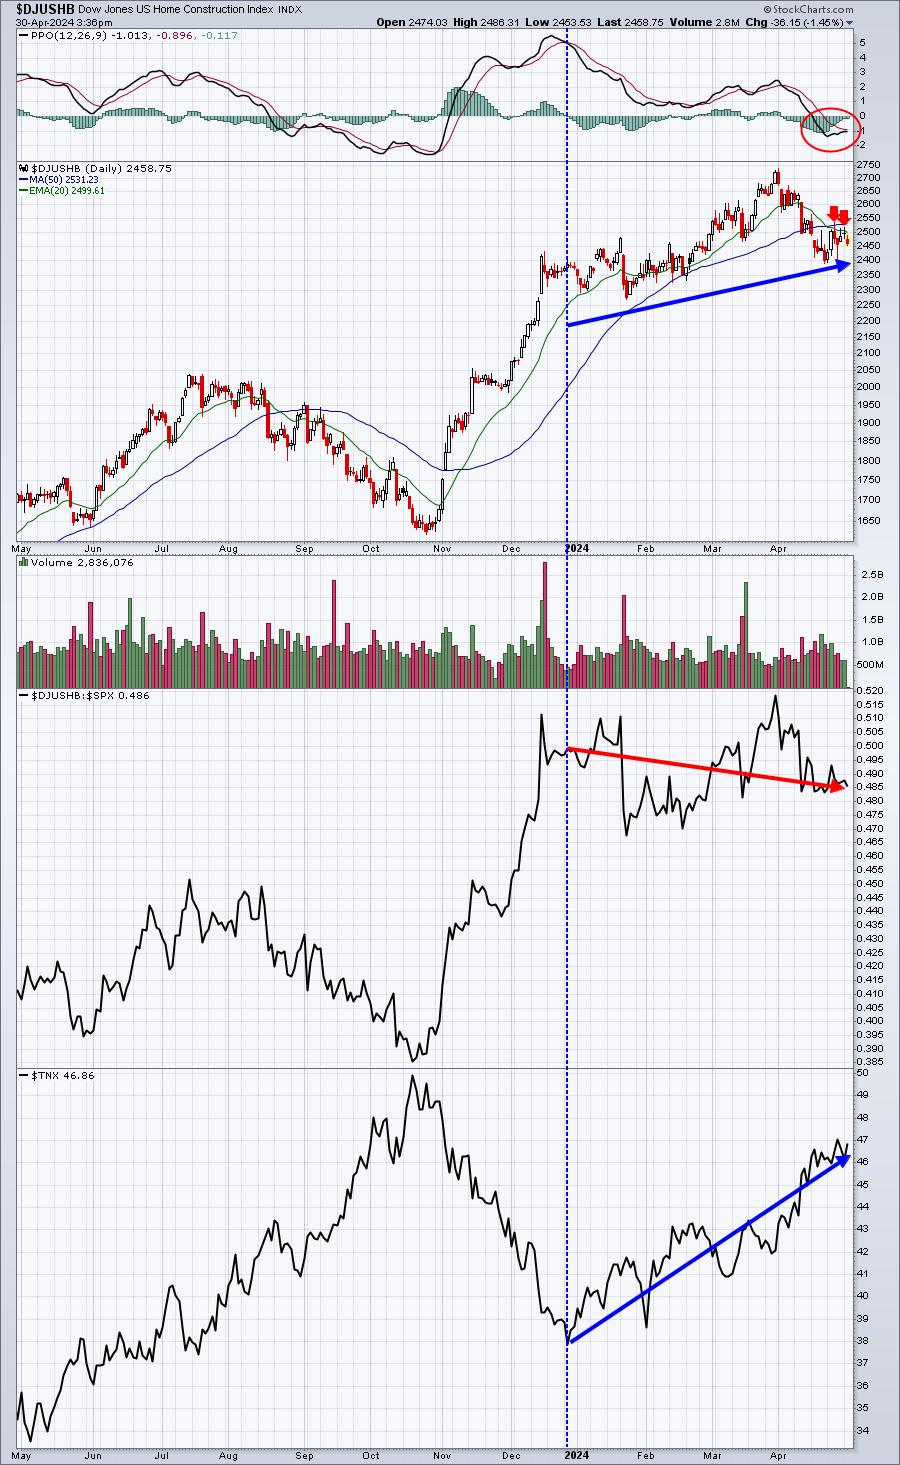
On a relative basis, the DJUSHB has held up remarkably well since the TNX bottom in late December. And the absolute price action hasn't been that bad, but you can see a bit of technical deterioration as the DJUSHB now sits beneath its 20-day EMA, with recent failed attempts to clear that key moving average (red arrows). Momentum has turned bearish as we've seen a PPO centerline cross and the 20-day EMA has crossed beneath the 50-day SMA.
Home construction stocks still have some technical work to do to repair its chart.
ChartLists/Strategies
Wells Fargo (WFC) is a stock I'm watching closely. It's been a leader among its banking peers ($DJUSBK) and it's pulling back slowly after its recent high-volume breakout:
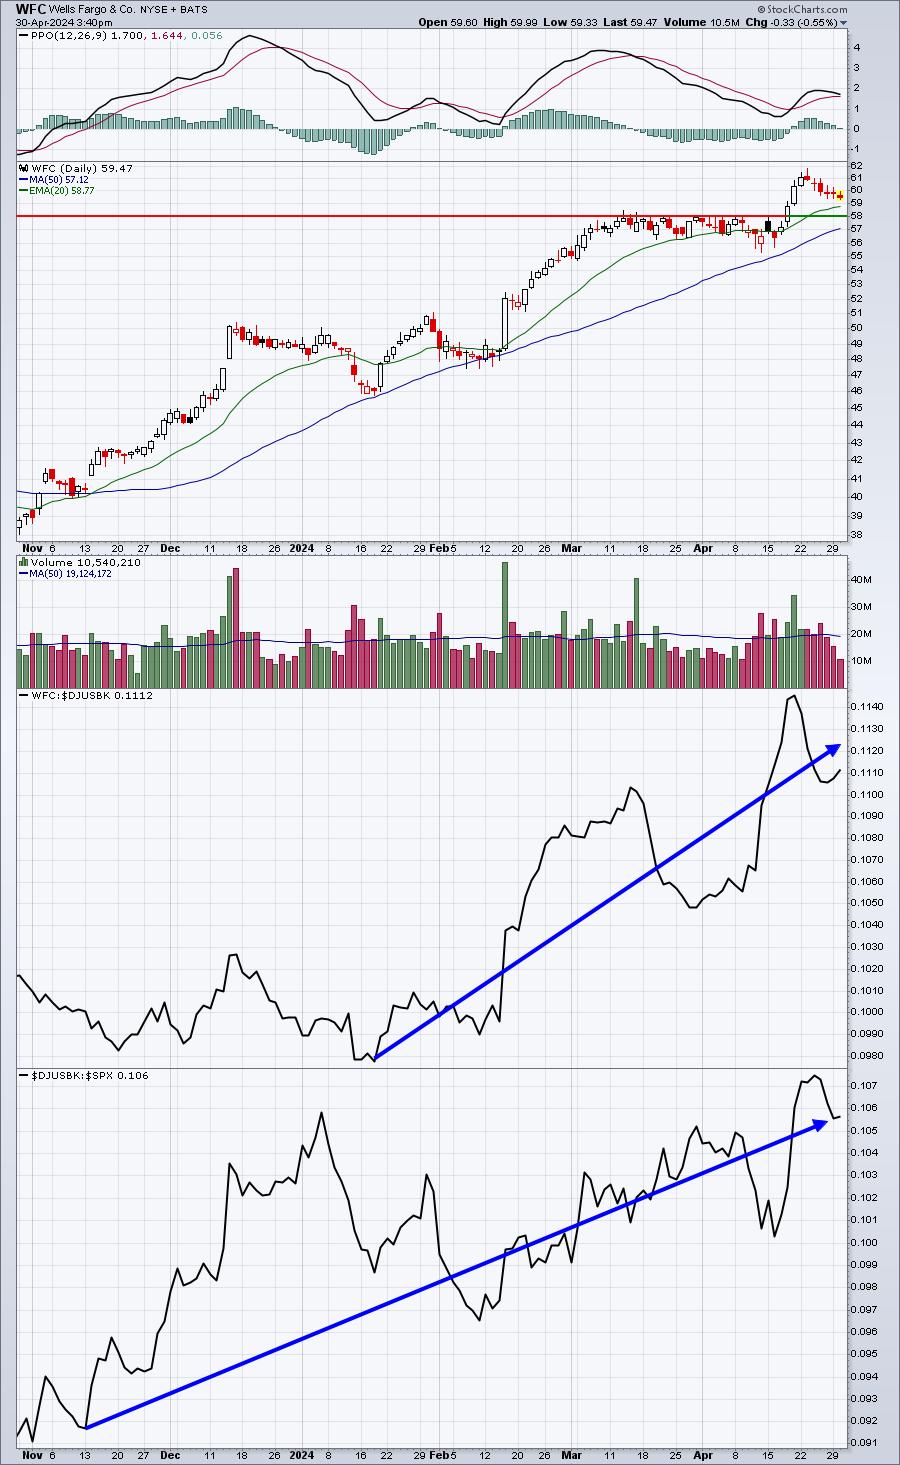
The 58-59 level would seem to be a solid reward-to-risk entry given price support and the rising 20-day EMA in this range.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include notable companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies that you own or are considering owning.
Tuesday, April 30:
AMZN, LLY, KO, AMD, MCD, ETN, SYK, SBUX, MDLZ, SAN, AMT, STLA, ITW, MPC, PYPL, TT, ECL, EPD, RSG, PCAR, APD, MMM, SMCI, OKE, PSA, AEP, MPLX, PRU, GEHC, SYY, MLM, FANG, IT, PEG, ADM, EXR, EIX, GLW, QSR, PINS, HUBB, CCJ, INVH, BSBR, LPLA, CNP, CLX, LDOS, SWKS, ESS, ZBRA, TAP, AMCR, UDR, EQH, WPC, CHK, SIRI, INCY, RNR, PAG, THC, GPK, CZR, LEA, TMHC, TKR, NOG, CVLT, MMSI, TXG, MLCO, LGIH, EAT, NEO, POWL, LMND
Wednesday, May 1:
MA, QCOM, PFE, ADP, GSK, CVS, KKR, MAR, DASH, EL, MET, AIG, AFL, COR, KHC, ALL, JCI, IDXX, CVE, YUM, CTVA, DVN, CTSH, MPWR, CDW, GPN, VRSK, DD, GOLD, VICI, ANSS, GRMN, EBAY, WEC, GIB, FNV AWK, PTC, ENTG, PPL, FTS, WLK, FSLR, MKL, VTR, CVNA, AER, CG, MRO, MAA, CF, ALB, NBIX, HST, MGM, ARCC, BIP, FLEX, SRPT, GFL, QRVO, WING, UTHR, PAYC, AFG, CLH, SCI, TTEK, PCOR, TECH, ZG, APA, MOS, INFA, MUSA, GNRC, PSN, CHRW, NCLH, ETSY, SFM, ENSG, GIL, FRSH, TENB, SLGN, GKOS, GTES, CRS, NSP, SMG, CAR, FORM, RELY, ACLS, WOLF, RIOT, LIVN, KLIC, EVTC, FSLY, UPWK, EXTR
Economic Reports
FOMC meeting begins today
Q1 employment cost index: 1.2% (actual) vs. 0.9% (estimate)
February Case-Shiller home price index: +0.6% (actual) vs. +0.1% (estimate)
February FHFA house price index: +1.2% (actual) vs. +0.1% (estimate)
April Chicago PMI: 37.9 (actual) vs. 45.0 (estimate)
April consumer confidence: 97.0 (actual) vs. 104.0 (estimate)
Happy trading!
Tom