
EB Daily Market Report - Friday, May 28, 2021
Memorial Day Holiday
Monday, May 31st is Memorial Day and is an observed holiday. Because the stock market will be closed, EarningsBeats.com will also be closed. Accordingly, there will be no EB Digest newsletter and no Daily Market Report (DMR). I want to wish everyone a safe and happy holiday weekend! And many thanks to all those who have served our great nation and those who continue to serve!
Executive Market Summary
- Futures were higher out of the gate this morning, but it's been a struggle to tack on anything further
- Most commodities are higher today, though crude oil ($WTIC) is down fractionally
- Earnings is still in the news as Salesforce.com (CRM, +5.93%) is the top performer in both the Dow Jones and S&P 500 after posting their quarterly results, which handily beat expectations
- A second big gainer from earnings is Ulta Beauty, Inc. (ULTA, +5.91%), another company that beat expectations soundly (EPS: $4.10 vs. $1.92 - actual vs. estimate)
- Real estate (XLRE, +0.83%) and technology (XLK, +0.67%) are today's leading sectors, while materials (XLB, -0.02%) is the only sector in negative territory
- The U.S. dollar (UUP) tested its declining 20-day EMA for the first time in a few weeks, likely leading to a bit of trepidation in the energy (XLE) and materials area
- Mostly weaker-than-expected economic data has led to a more defensive posture today, with the 10-year treasury yield ($TNX) falling 3 basis points to 1.58%
Market Outlook
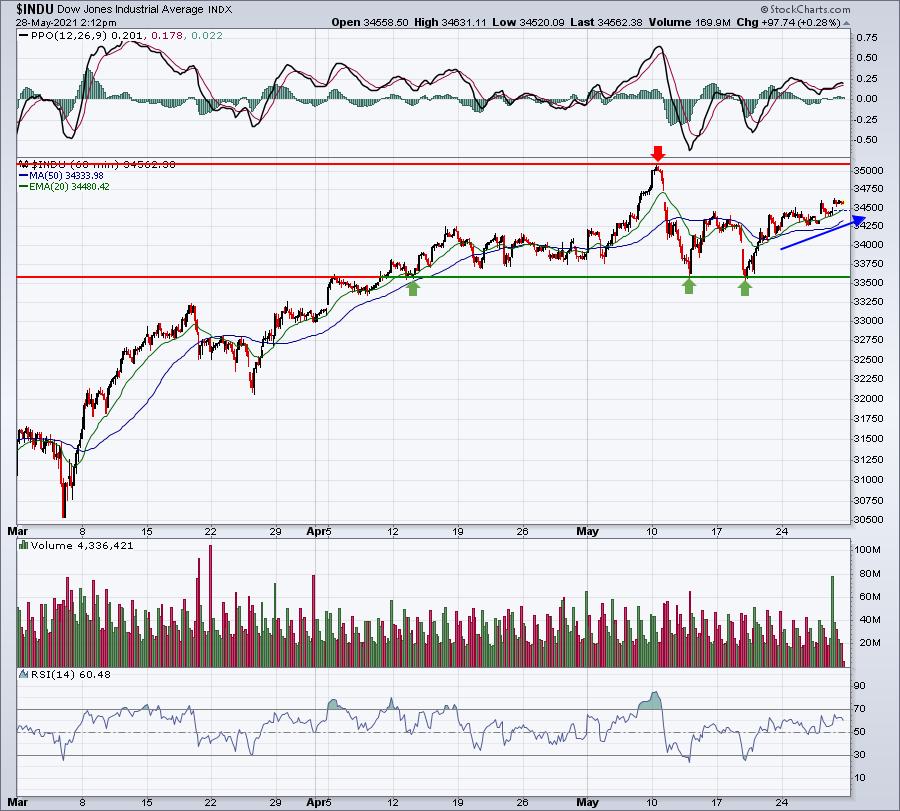
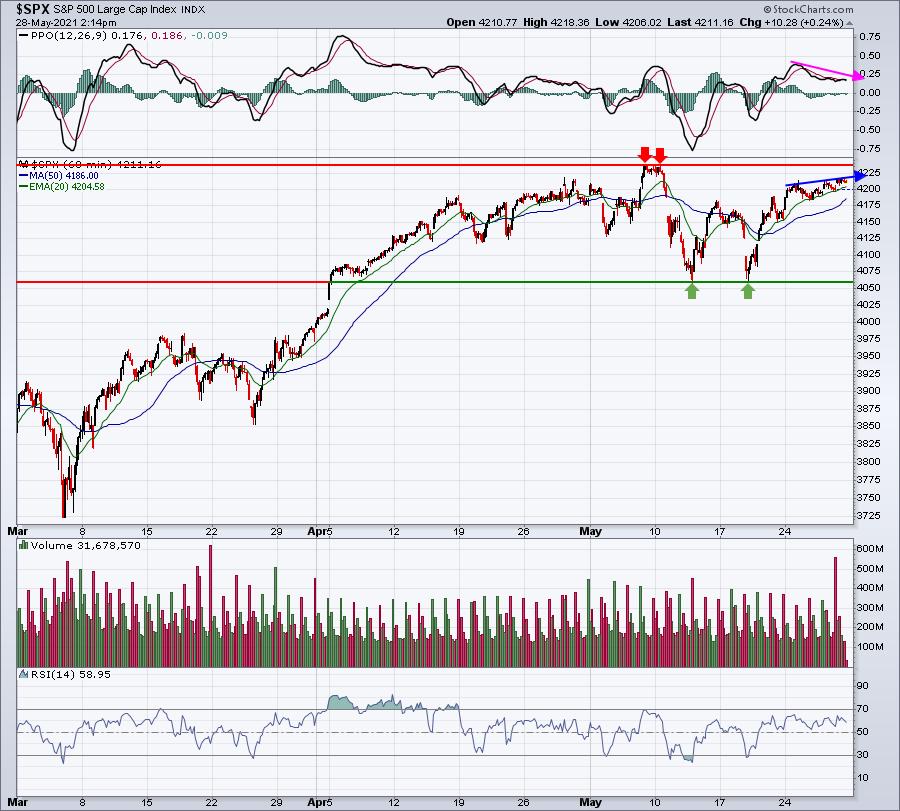
Here's the latest look at our 3 major indices on an hourly chart:
Dow Jones:
S&P 500:
NASDAQ:
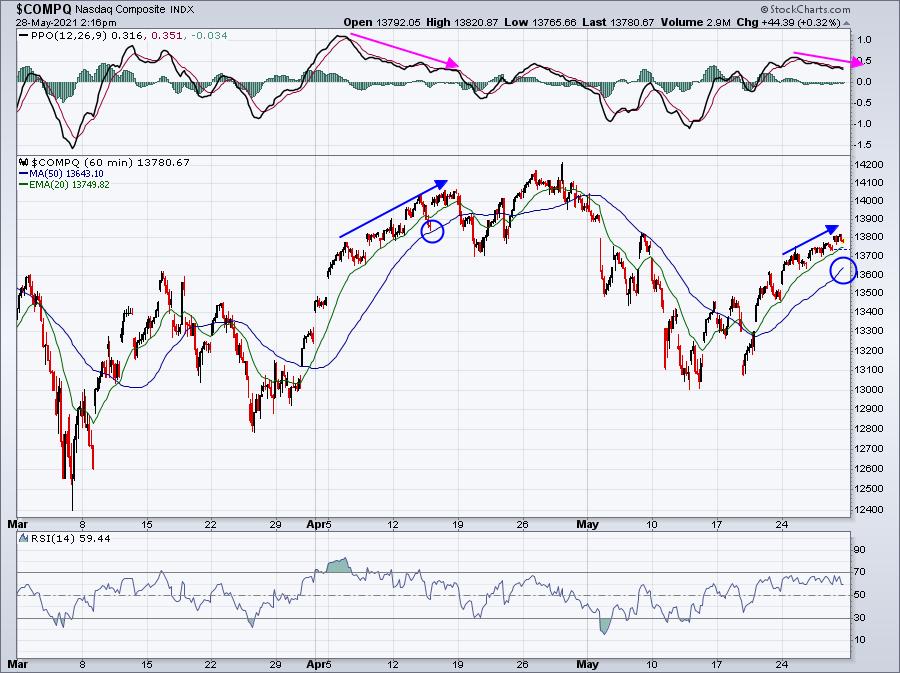
I believe the stock market is poised to set new highs in the near-term. However, the above charts do show mostly rising prices with a falling hourly PPO. That suggests a 1% selloff could occur at any time. We're in a historically strong period through the end of next week. If we do see a selloff, I wouldn't be surprised to see a very quick recovery off of that selling.
I think the more intermediate-term picture is one of consolidation. Therefore, once we move beyond next week, I'd grow a bit more cautious, especially with another round of inflation reports looming the following week (June 10th for CPI and June 15th for PPI).
Sector/Industry Focus
Computer hardware ($DJUSCR) has been weak on a relative basis, topping out back in January. But it has reached a solid reward-to-risk entry level based upon its trendline:
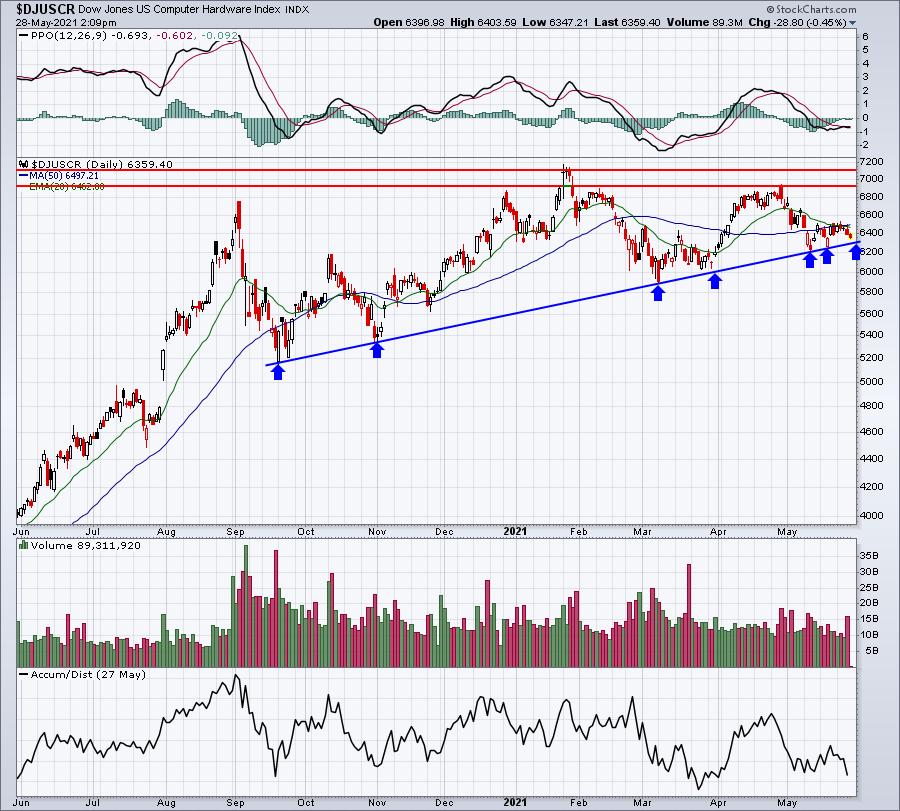
Because the index is so close to its trendline support and because it's successfully tested this trendline on at least 6 prior occasions (blue arrows), it wouldn't be a bad time to look at key stocks within this area of market - like Apple (AAPL).
ChartLists/Strategies
While our major indices have moved mostly higher, that doesn't mean that every stock is moving higher. Many continue to pull back and consolidate and the best way for us to uncover those is to run our custom scans against our ChartLists. When I ran our 20-day EMA test against our Strong Earnings ChartList, I found 2 stocks that I'd expect to bounce sooner rather than later:
LAND:
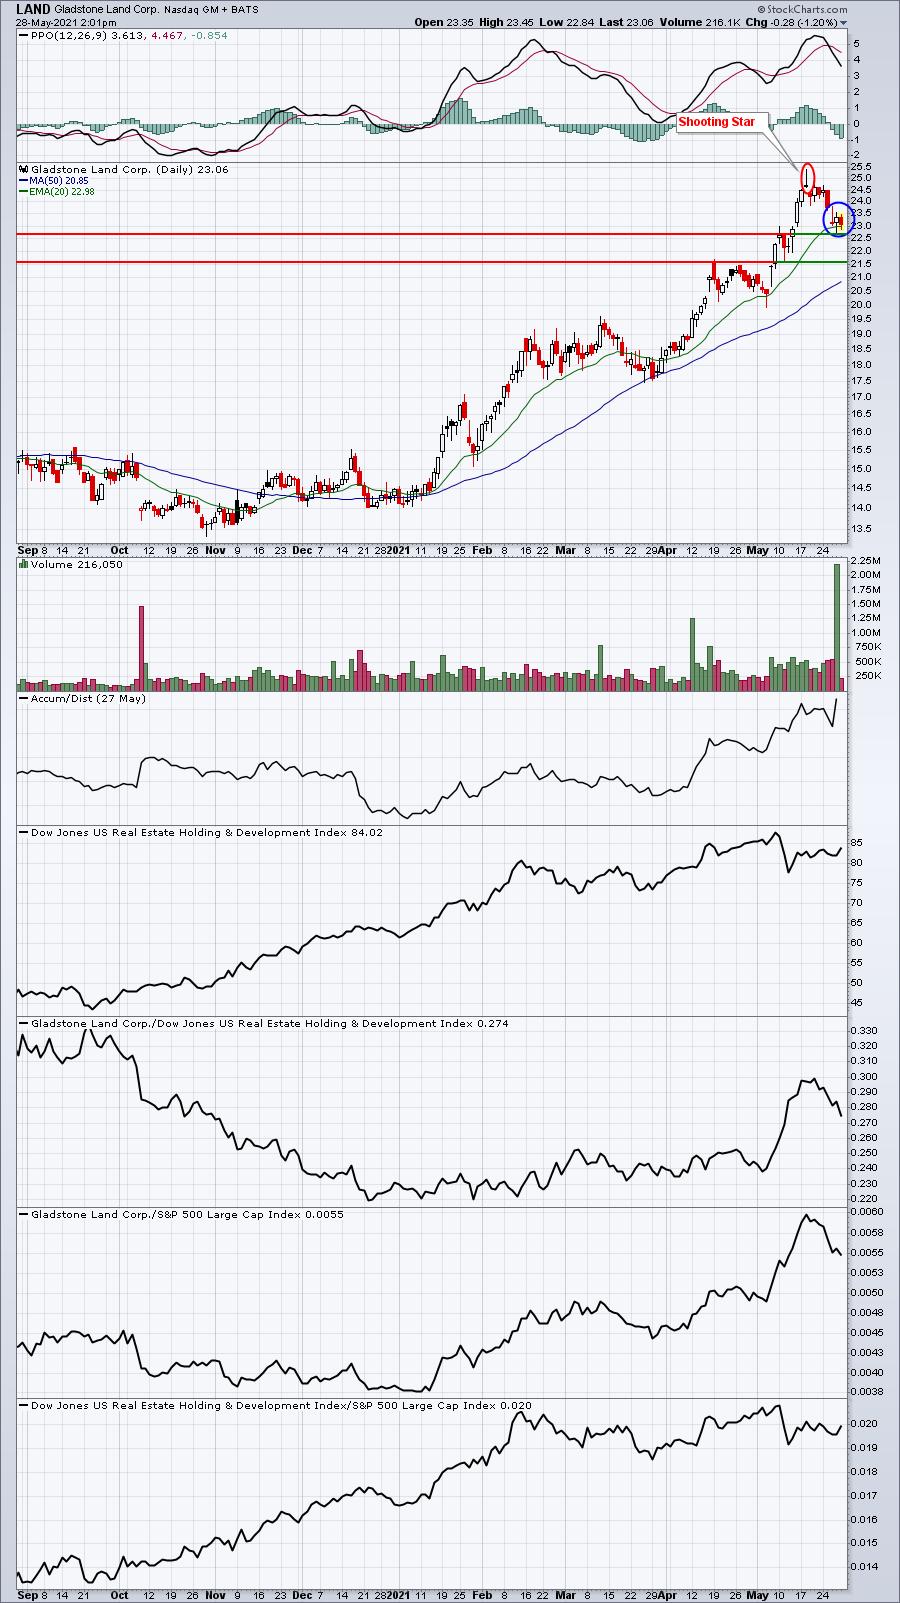
I like 20-day EMA tests as entry points on uptrending stocks with strong PPOs. At LAND's last high, the PPO was also at a high, so there's no sign of slowing momentum at this point.
LQDT:
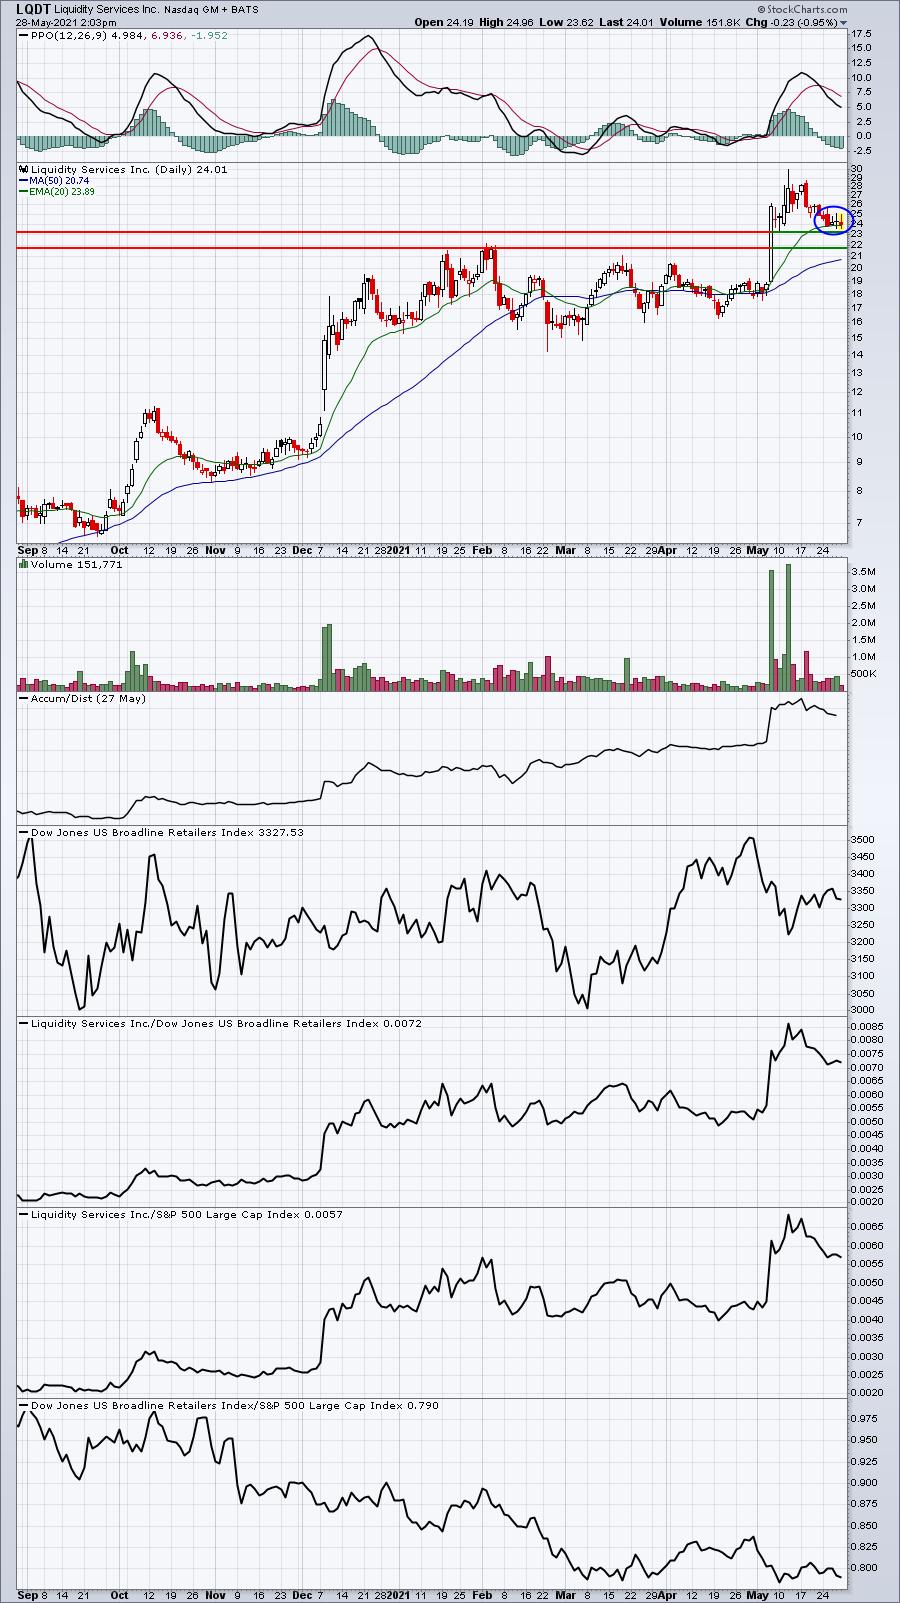
Like LAND, LQDT has an area of price support just beneath its 20-day EMA, but I'd still expect a bounce from the current 20-day EMA. If LQDT moves back up and prints a negative divergence, that's when I'd look for a move back to test price support.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Friday, May 28:
BIG, HIBB
Tuesday, June 1:
ZM, BNS, HPE, STNE, CGC, APPS, MDLA, AMBA
Economic Reports
April personal income: -13.1% (actual) vs. +0.5% (estimate)
April personal spending: +0.5% (actual) vs. +0.6% (estimate)
April wholesale inventories: +0.8% (actual) vs. +1.2% (estimate)
May Chicago PMI: 75.2 (actual) vs. 70.0 (estimate)
May consumer sentiment: 82.9 (actual) vs. 83.0 (estimate)
Happy trading!
Tom