
EB Daily Market Report - Friday, July 29, 2022
ChartLists
I have updated three more key ChartLists as follows:
- Raised Guidance ChartList (RGCL)
- Strong AD ChartList (SADCL)
- Bullish Trifecta ChartList (BTCL)
They are all available for viewing/download on our website.
Executive Market Summary
- Futures were higher overnight after a couple of key large cap earnings reports
- Crude oil ($WTIC, +2.29%) traded above $100 per barrel earlier today, but is back down to $98.60 at last check
- The 10-year treasury yield ($TNX) is down a couple basis points, threatening to close beneath yield support at 2.70% for the second straight day
- Energy (XLE, +4.38%) is benefiting from the strength in crude
- Meanwhile, consumer discretionary (XLY, +3.86%) is rallying after the solid reaction to Amazon.com's (AMZN, +11.50%) quarterly earnings report last night
- Apple, Inc. (AAPL, +3.55%) is providing strength of its own after it also posted solid results that included record revenues and better-than-expected earnings
- Roku, Inc. (ROKU, -23.38%) wasn't quite so fortunate, missing its estimates; ROKU was a stock that I suggested you avoid heading into earnings
Market Outlook
As I mentioned earlier, I took profits on the QQQ and QLD. I figure if we can make the breakout, then I'll change strategies and begin buying more individual stocks for swing trades. If we fail to make the breakout, then there'll be even better opportunities in the days ahead. Here's the reprint of what I sent out earlier today:
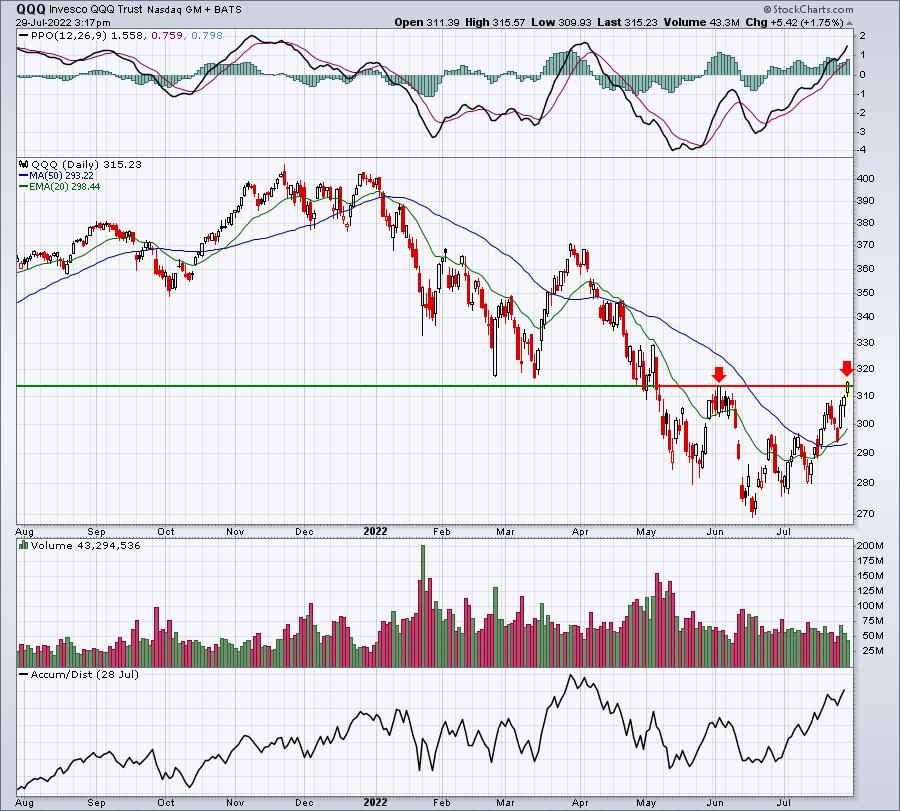
We still have another 30 minutes left in the trading day and a failure could still occur. But it sure doesn't seem like that will happen. The XLY:XLP ratio broke out above critical neckline resistance today, further confirming that this bull market is gaining steam.
Sector/Industry Focus
The Volatility Index ($VIX) continues to hit lower lows as fear subsides. Bad news should result in the stock market falling and the VIX rising. Instead, we've been seeing stocks bought with bad news and the VIX is now trading at a 3-month low:
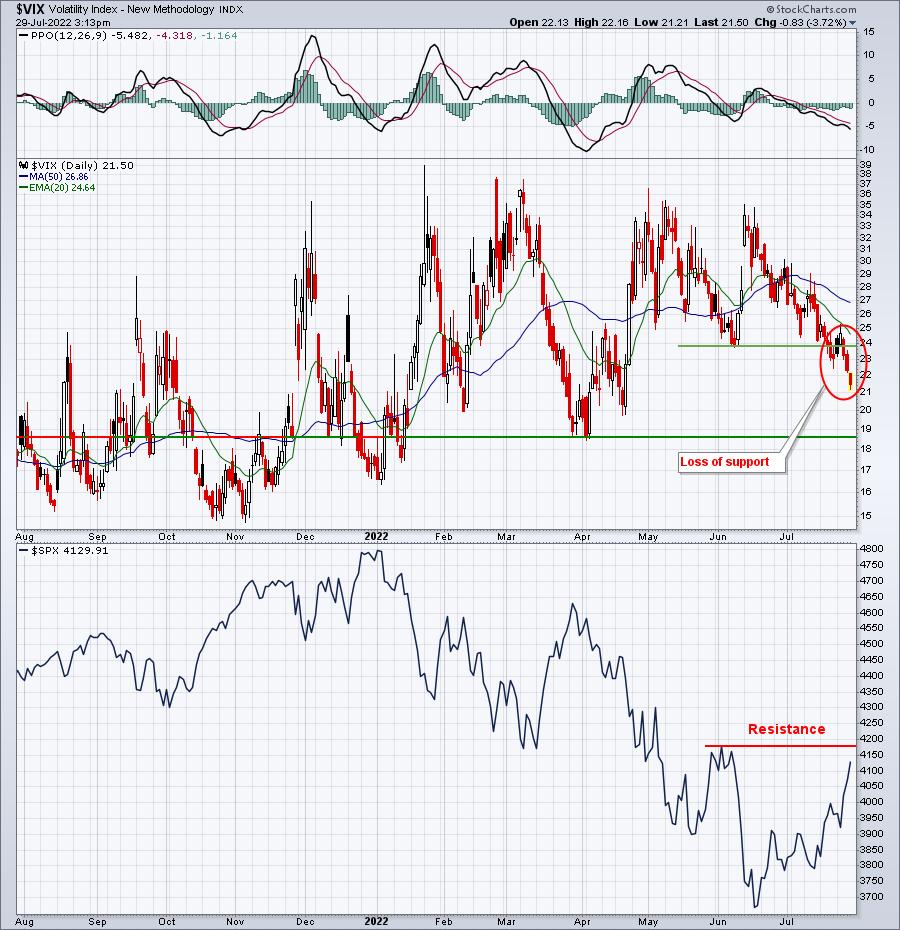
Note that while the S&P 500 has yet to take out overhead price resistance, the VIX has already broken down beneath the low that was established on that early-June S&P 500 rally. Traders are growing much less fearful and that is one ingredient necessary to resume the secular bull market.
ChartLists/Strategies
Given today's big breakout on the NASDAQ, I will be changing my trading strategies to include more individual stock trades and I'll trade the QQQ/QLD much less often. I will favor stocks from our portfolios and Strong Earnings ChartList (SECL), looking for solid reward to risk setups. Now that prices are beginning to uptrend (in my opinion), I'll be looking primarily for great looking charts where we've seen pullbacks to test key price support and/or 20-day EMA support. Here's an example of a nice looking trade:
QCOM:
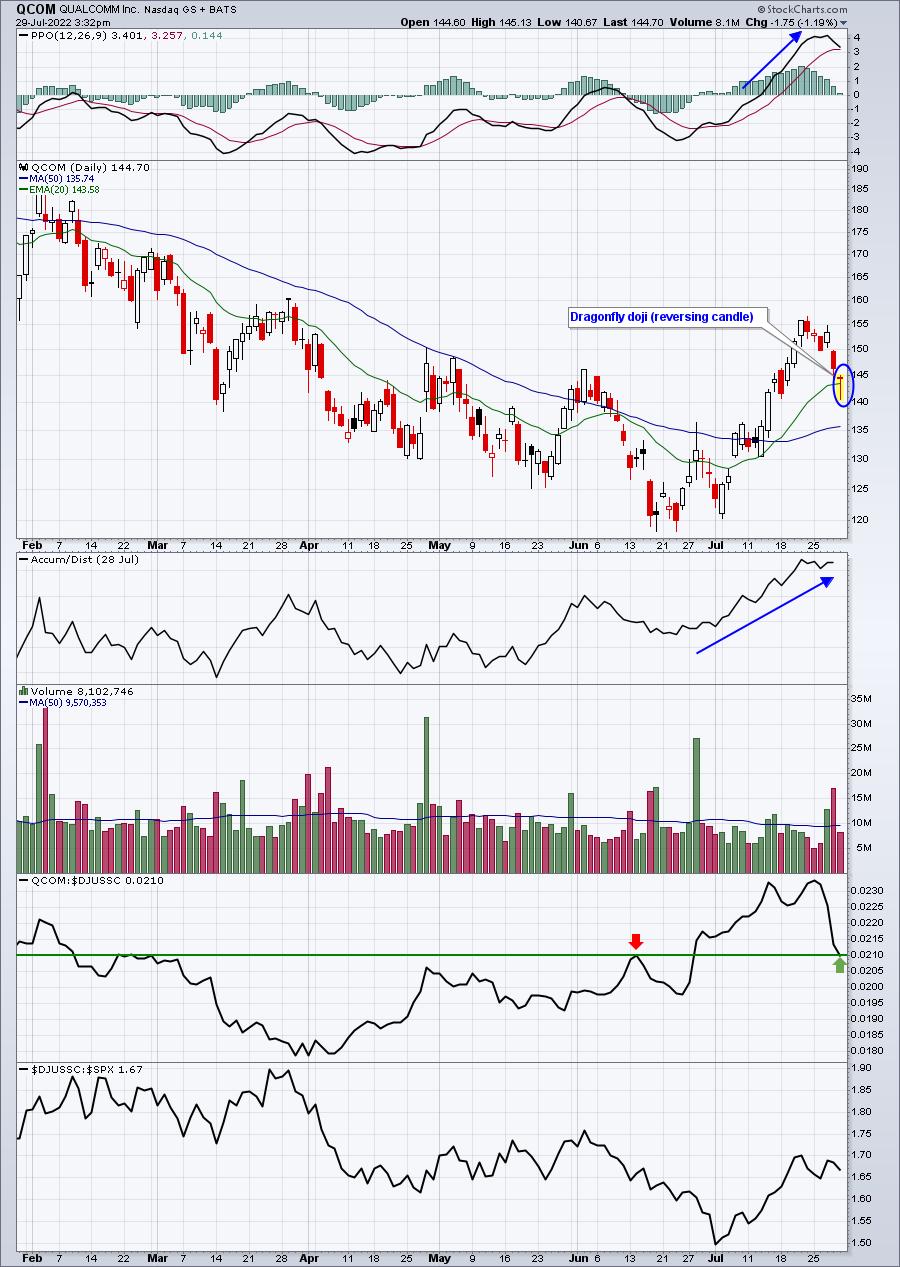
There's a lot to like here. Semiconductors are beginning to strengthen and QCOM has shown leadership amongst its semiconductor peers. Throw in that strong PPO and the pullback to test the rising 20-day EMA, and I believe the reward to risk on the long side is excellent here.
I'll be providing many more individual stock setups in the days and weeks ahead, assuming the S&P 500 continues to trend above its now-rising 20-day EMA.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Friday, July 29:
XOM, PG, CVX, ABBV, AZN, ENB, CHTR, CL, AON, PSX, SMFG, E, MFG, NWG, LYB, IMO, BBVA, WY, GWW, CHD, MGA, CNHI, WPC, CBOE, BAH, NWL, GTLS, NVT, CRI, BLMN
Monday, August 1:
ATVI, WMB, DVN, AFL, SBAC, SPG, GPN, ANET, ON, FANG, MPWR, CF, MOS, J, CHKP, ZI, PINS, CNA, BLDR, DVA, LSCC, CAR, OHI, VNO, LEG, AMG, AMKR, NSP, RDN, AJRD, AXNX, VRNS, SANM, RMBS, RIG, KFRC, HLIT, TWI
Economic Reports
June personal income: +0.6% (actual) vs. +0.5% (estimate)
June personal spending: +1.1% (actual) vs. +0.9% (estimate)
July Chicago PMI: 52.1 (actual) vs. 56.0 (prior)
July consumer sentiment: 51.5 (actual) vs. 51.1 (prior)
Happy trading!
Tom