
EB Weekly Market Report - Monday, July 20, 2026
ChartLists/Spreadsheets
The following ChartLists/Spreadsheets were updated over the weekend and have been updated on our website:
- Strong Earnings (SECL)
- Strong Future Earnings (SFECL)
- Raised Guidance (RGCL)
- Bullish Trifecta (BTCL)
- Short Squeeze (SSCL)
- Leading Stocks (LSCL)
- Matt's Hot Stocks (HTCL)
- Upcoming Earnings
- Upcoming Earnings Relative Strength
- Key Manipulation Spreadsheet
The above ChartLists and the Key Manipulation spreadsheet have been updated through Friday, July 17th. You can view and/or download these ChartLists from our website, and also read about them to gain a better understanding of how they can help in your trading success.
Weekly Market Recap
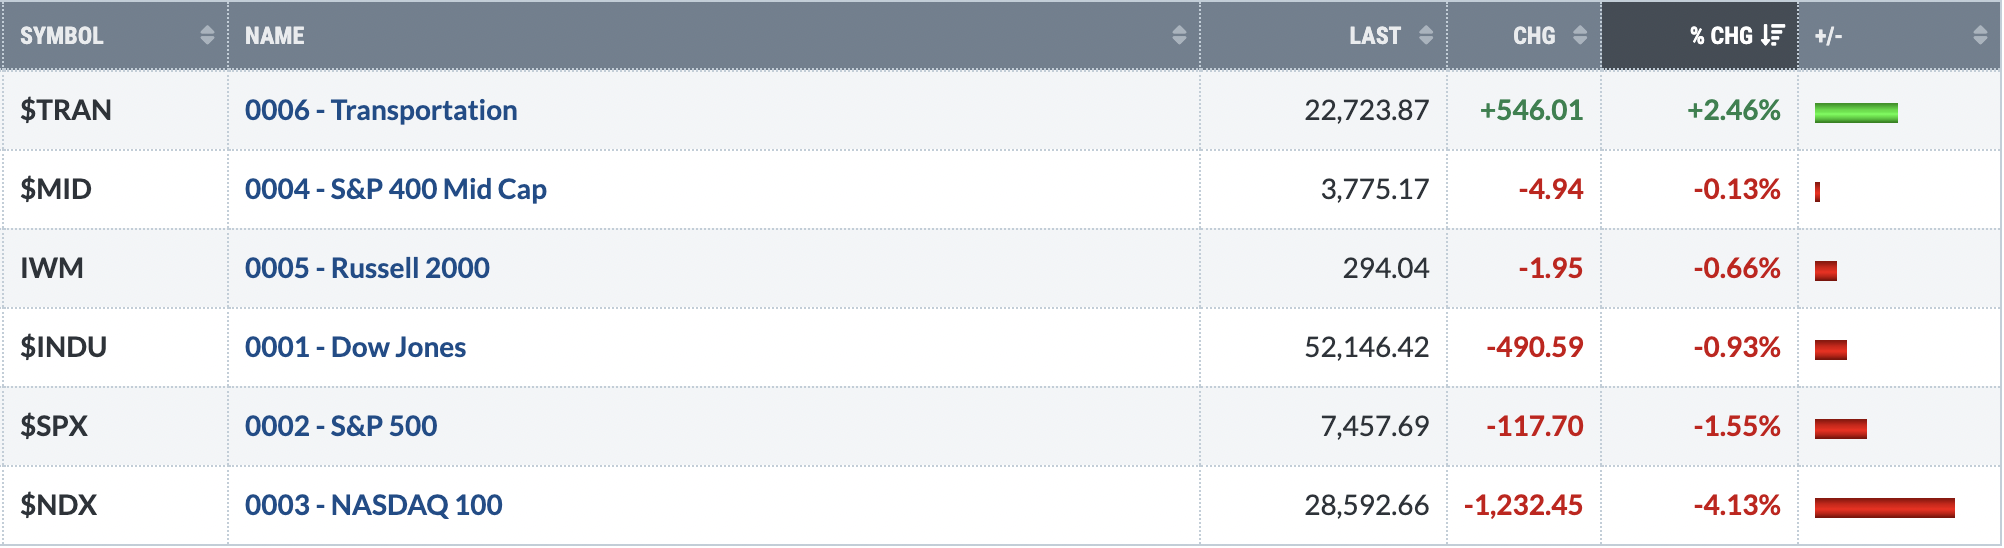
Major Indices
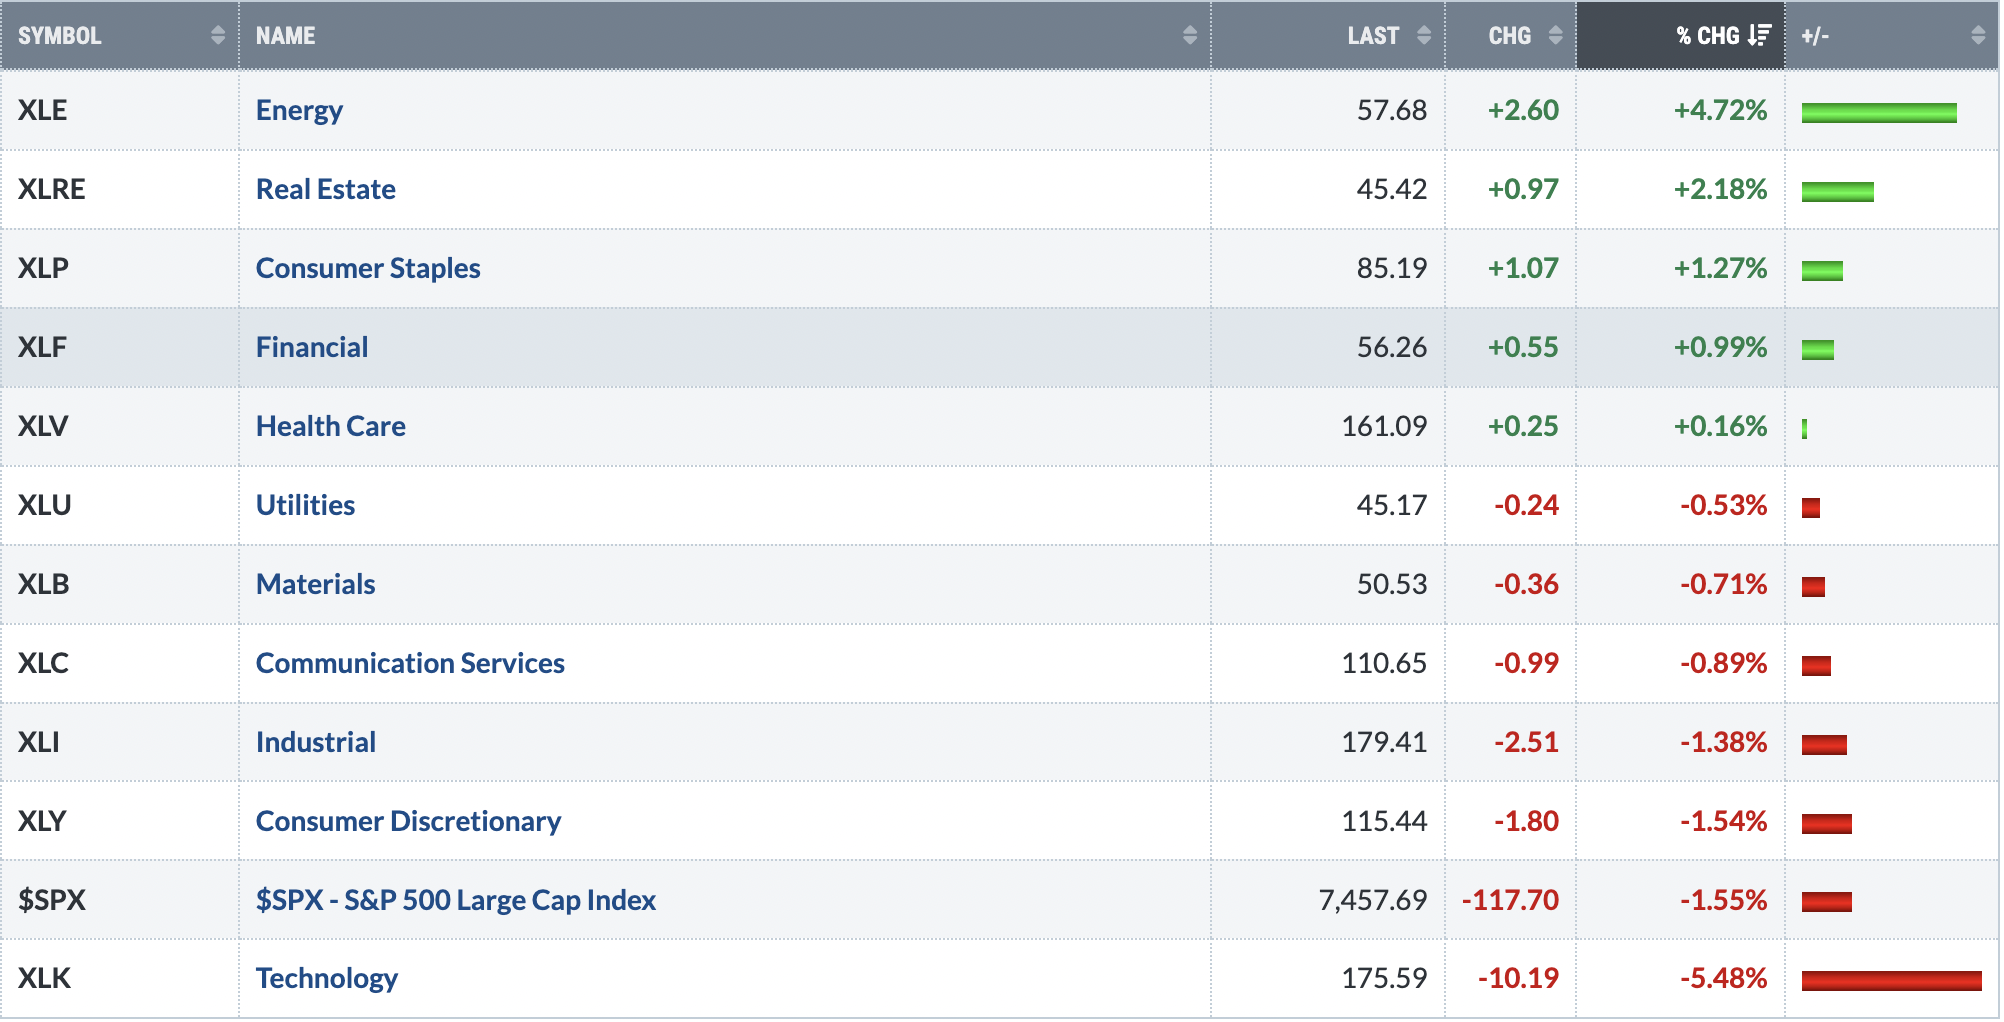
Sectors
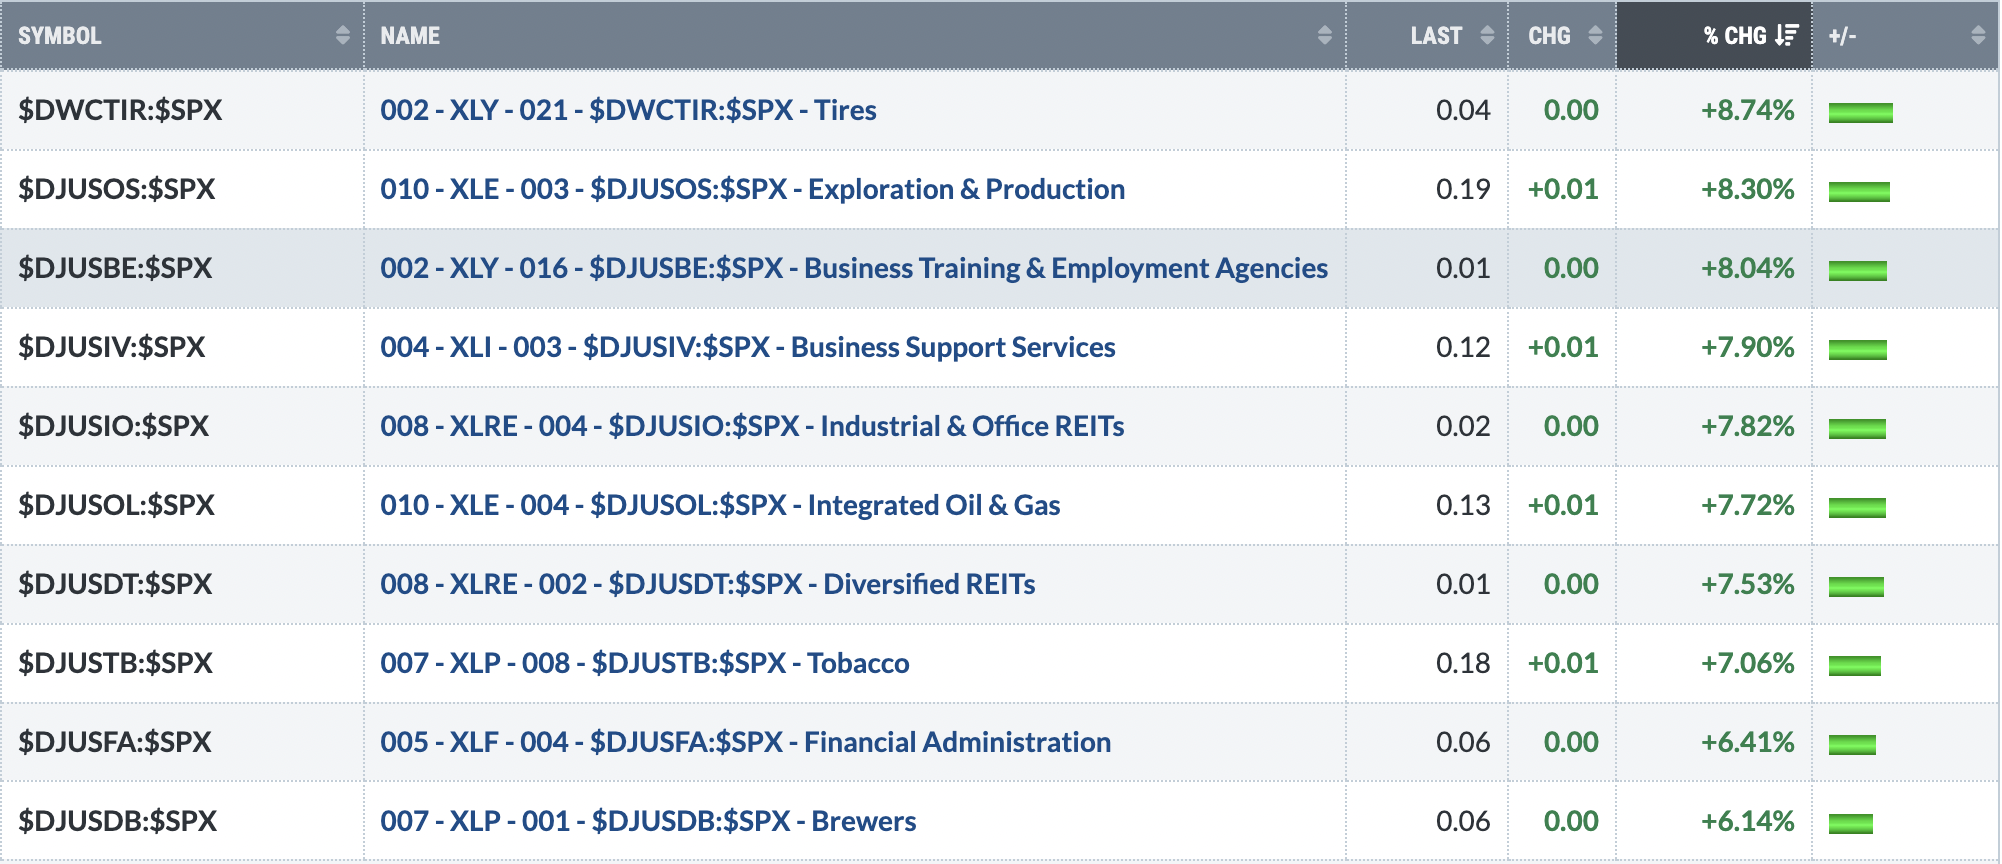
Top 10 Industries Last Week
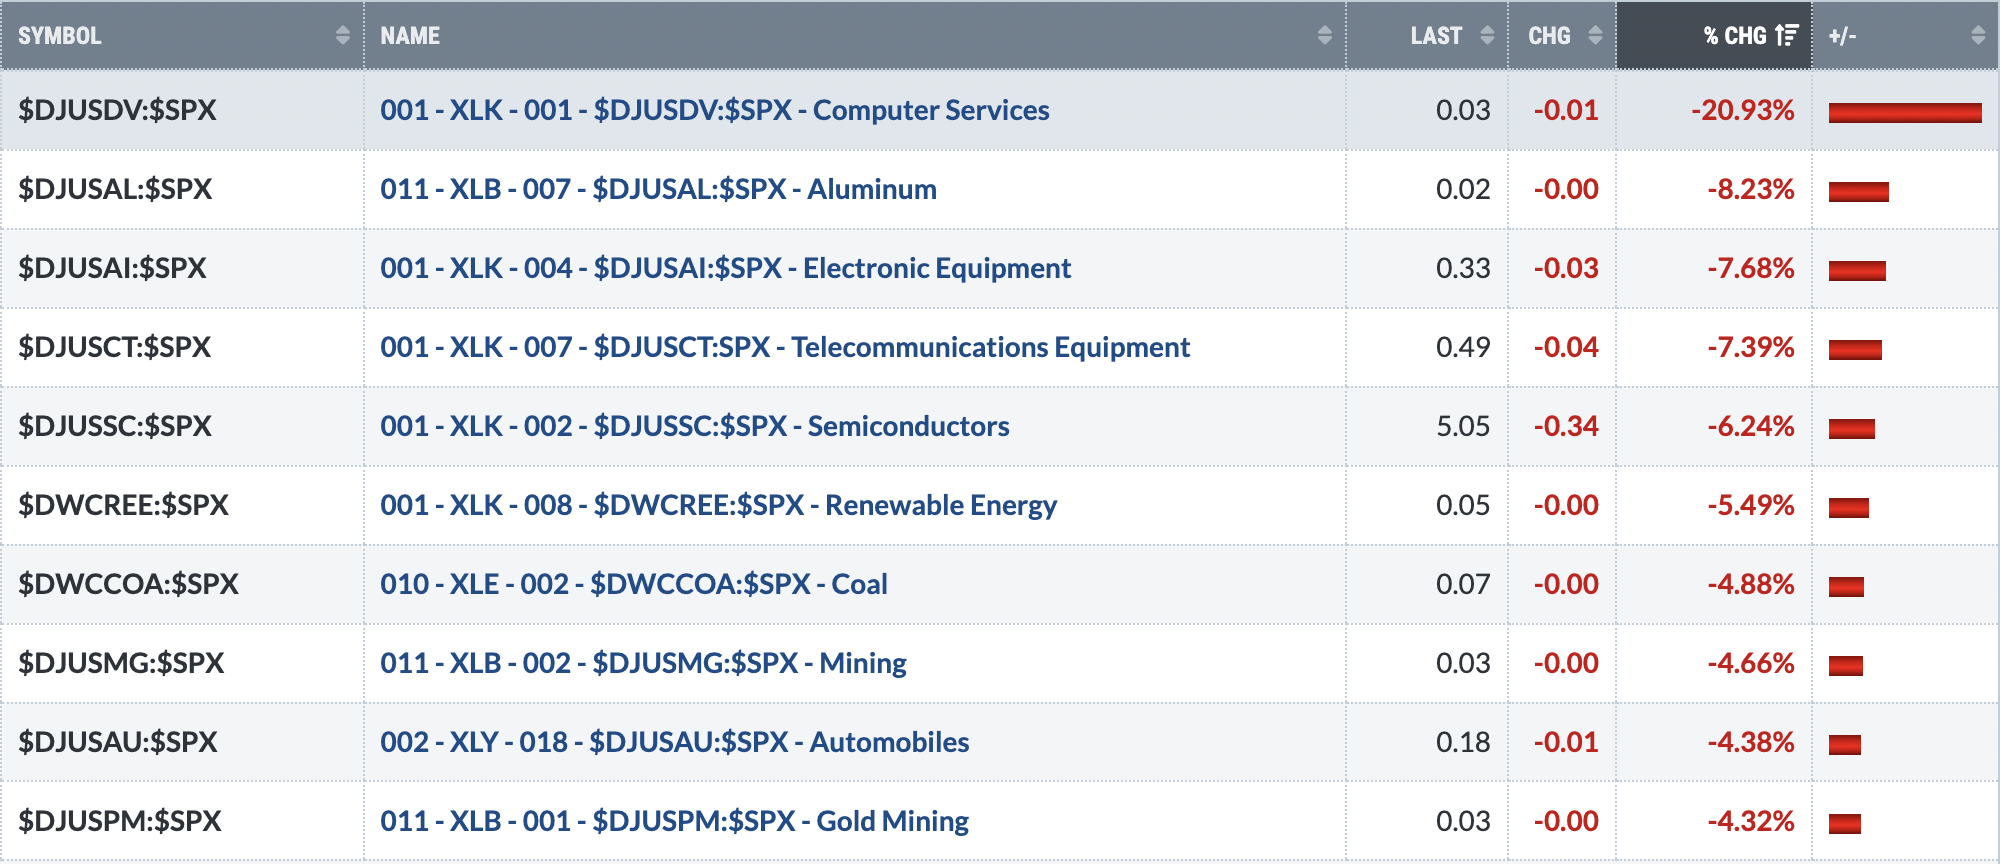
Bottom 10 Industries Last Week
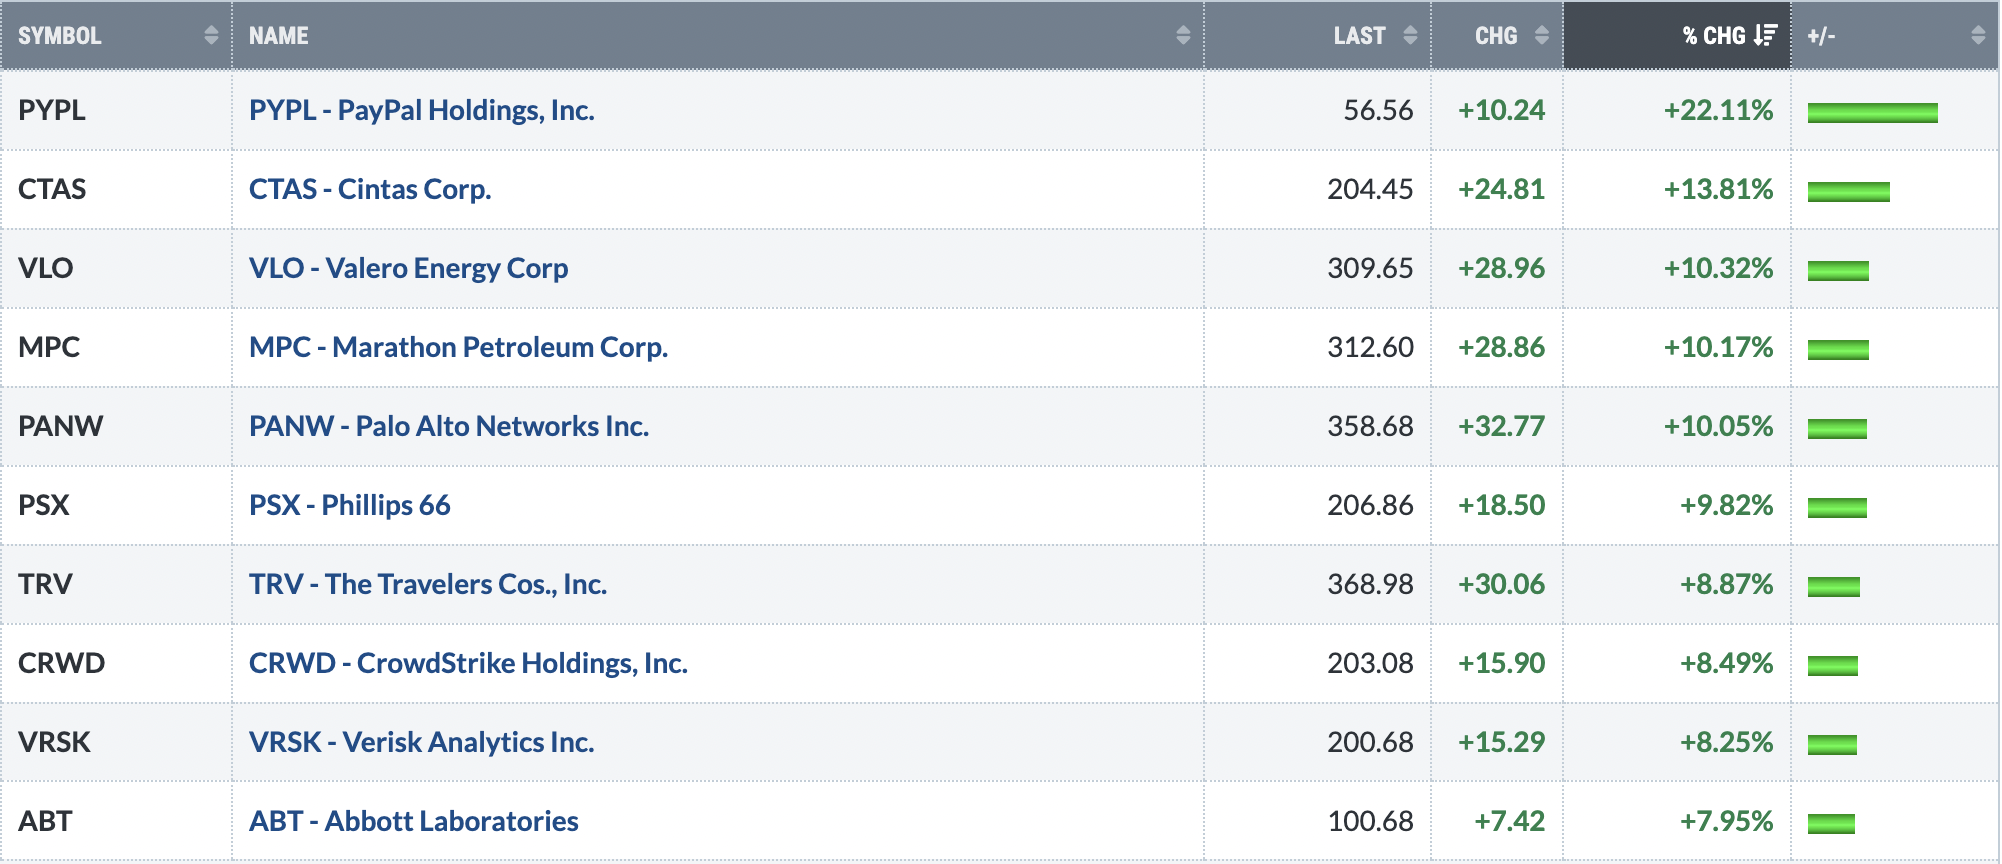
Top 10 Stocks - S&P 500/NASDAQ 100
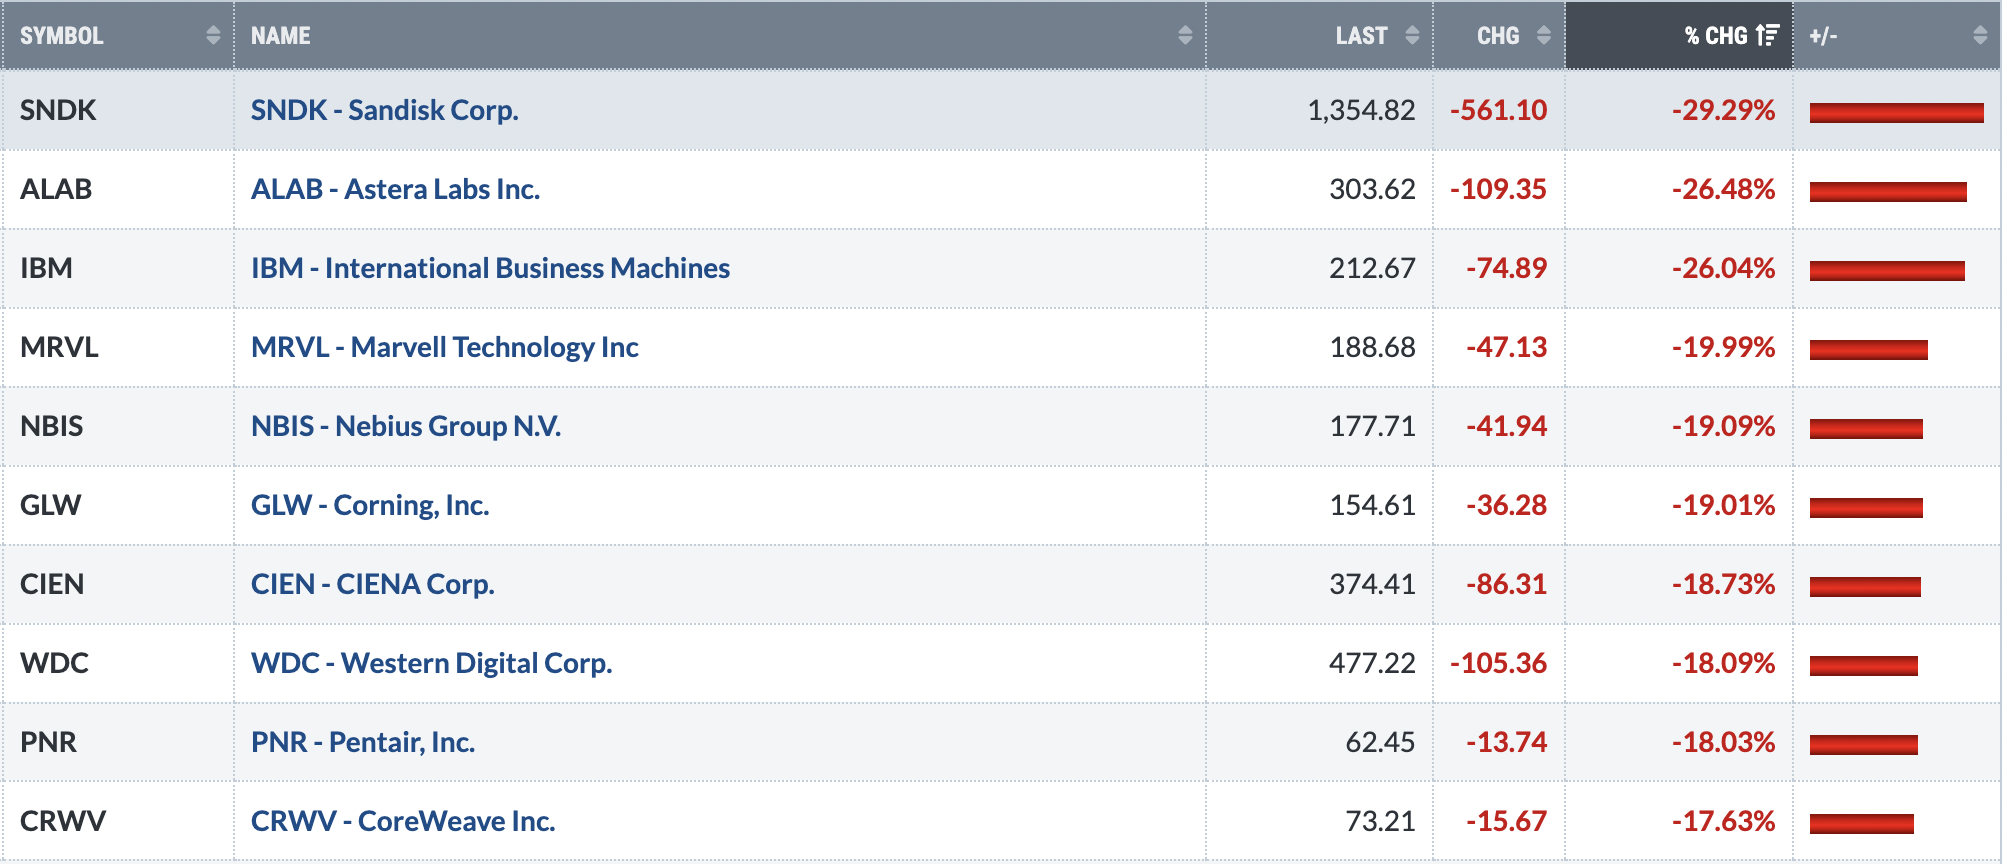
Bottom 10 Stocks - S&P 500/NASDAQ 100
Big Picture
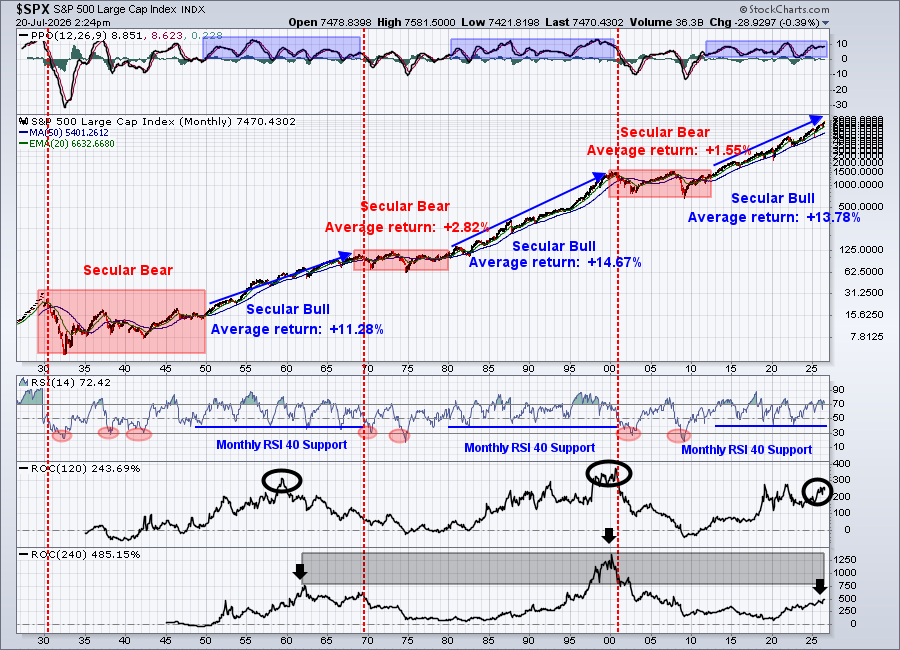
One common ingredient of EVERY secular bear market is a monthly PPO that turns negative, or drops below the monthly PPO centerline. There MUST be sustained weakness over an extended period of time in order for this to occur. The problem is that many market pundits want to call a secular bear market every time we have a normal period of profit taking and consolidation. There have only been 2 secular bear markets in my lifetime and I'd say that most folks will never witness 4 secular bear markets in their lifetime. Stop trying to call them. It's a waste of time and energy and the opportunity costs are tremendous.
We're in a secular BULL market. Enjoy it.
Sustainability Ratios
Here's the latest look at our key intraday ratios as we follow where the money is traveling on an INTRADAY basis (ignoring gaps):
QQQ:SPY
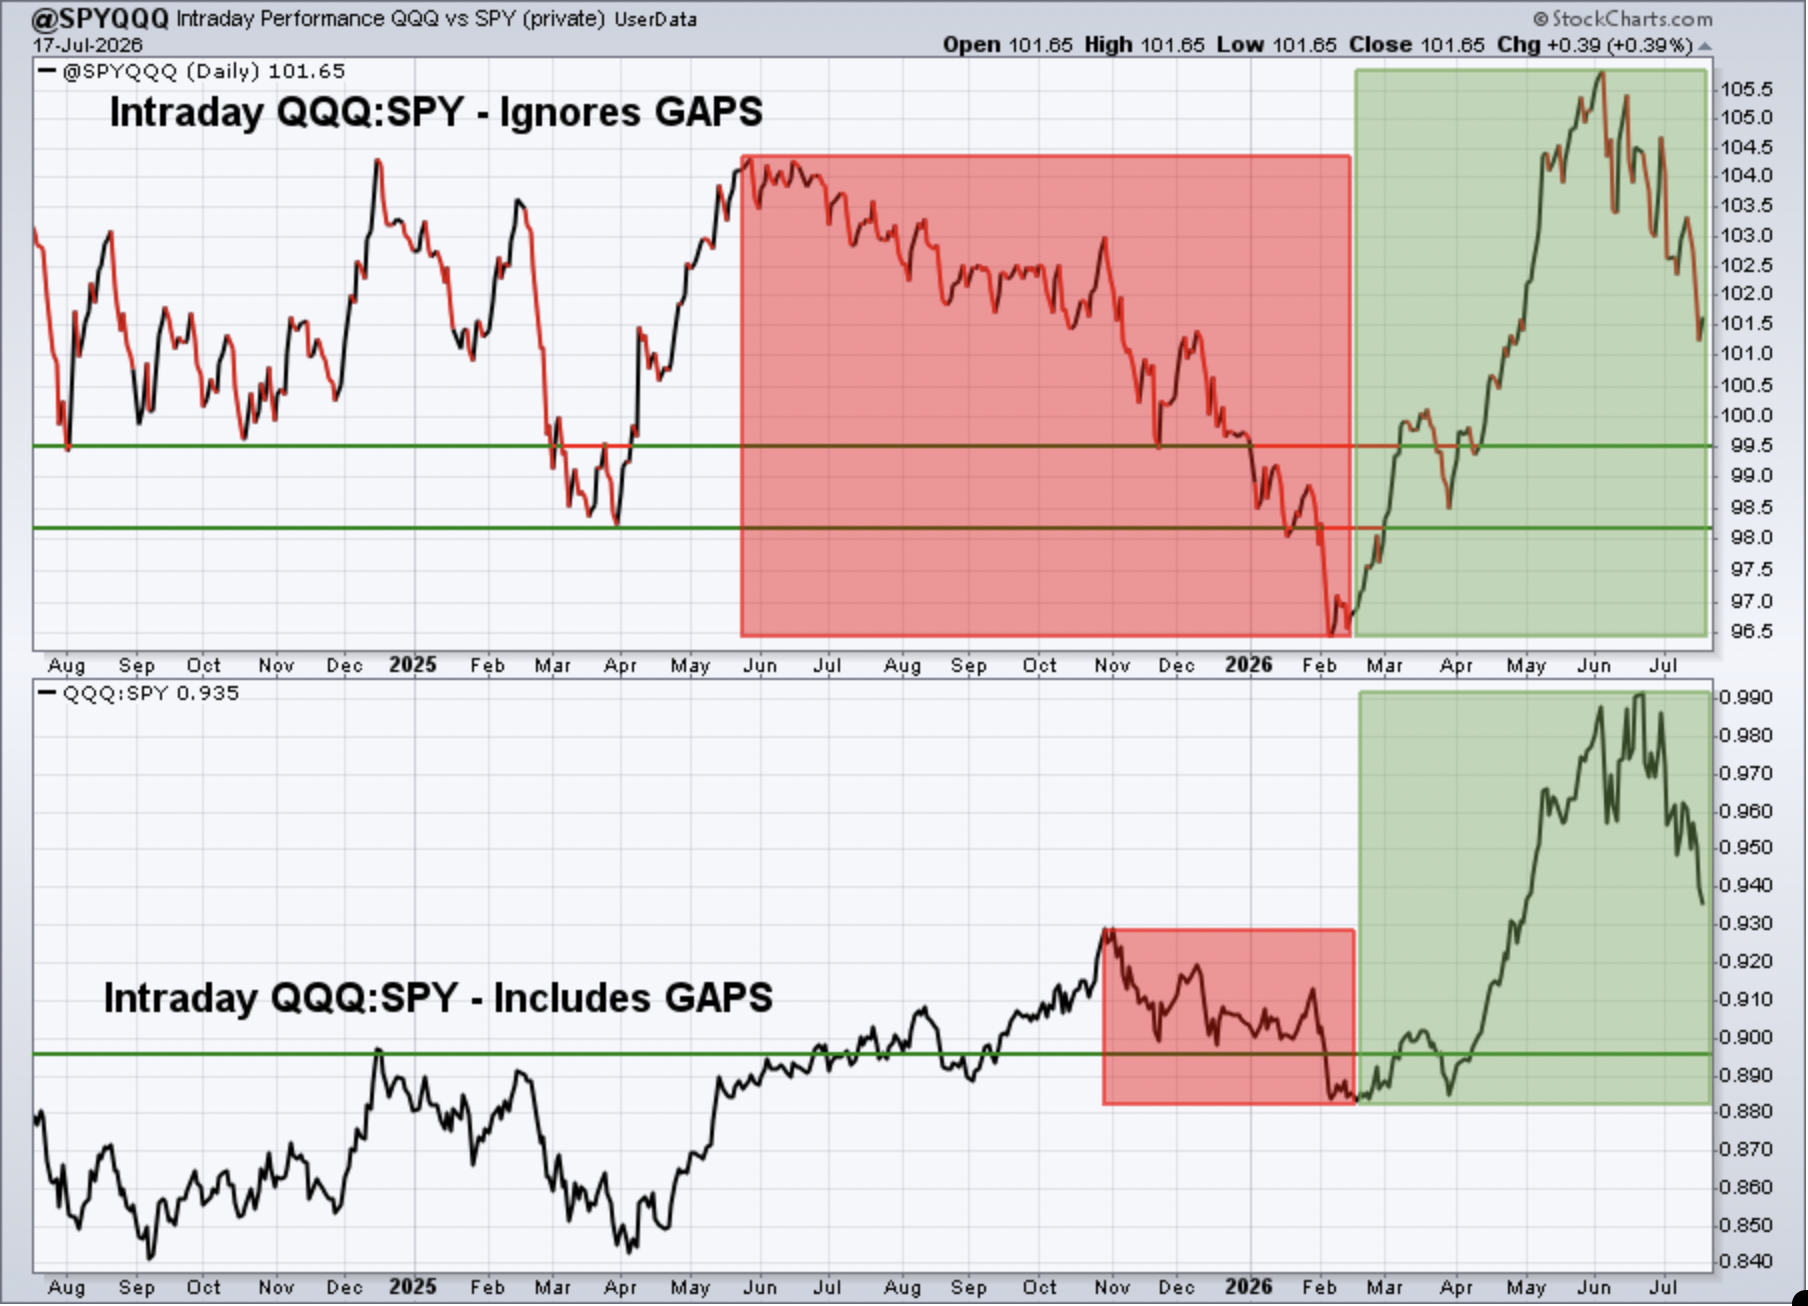
Keep in mind that the intraday analysis provided is a "work in progress". I continue to analyze this data to see if it helps provide us clues about calling market direction. It makes common sense to me that it should help in some sense, but it'll require a much longer-term study to determine its worth.
The recent QQQ:SPY relative downtrend remains in play as money rotates into more value-oriented stocks during this consolidation phase. This will likely continue so long as semiconductor stocks struggle, because of their huge impact.
IWM:QQQ
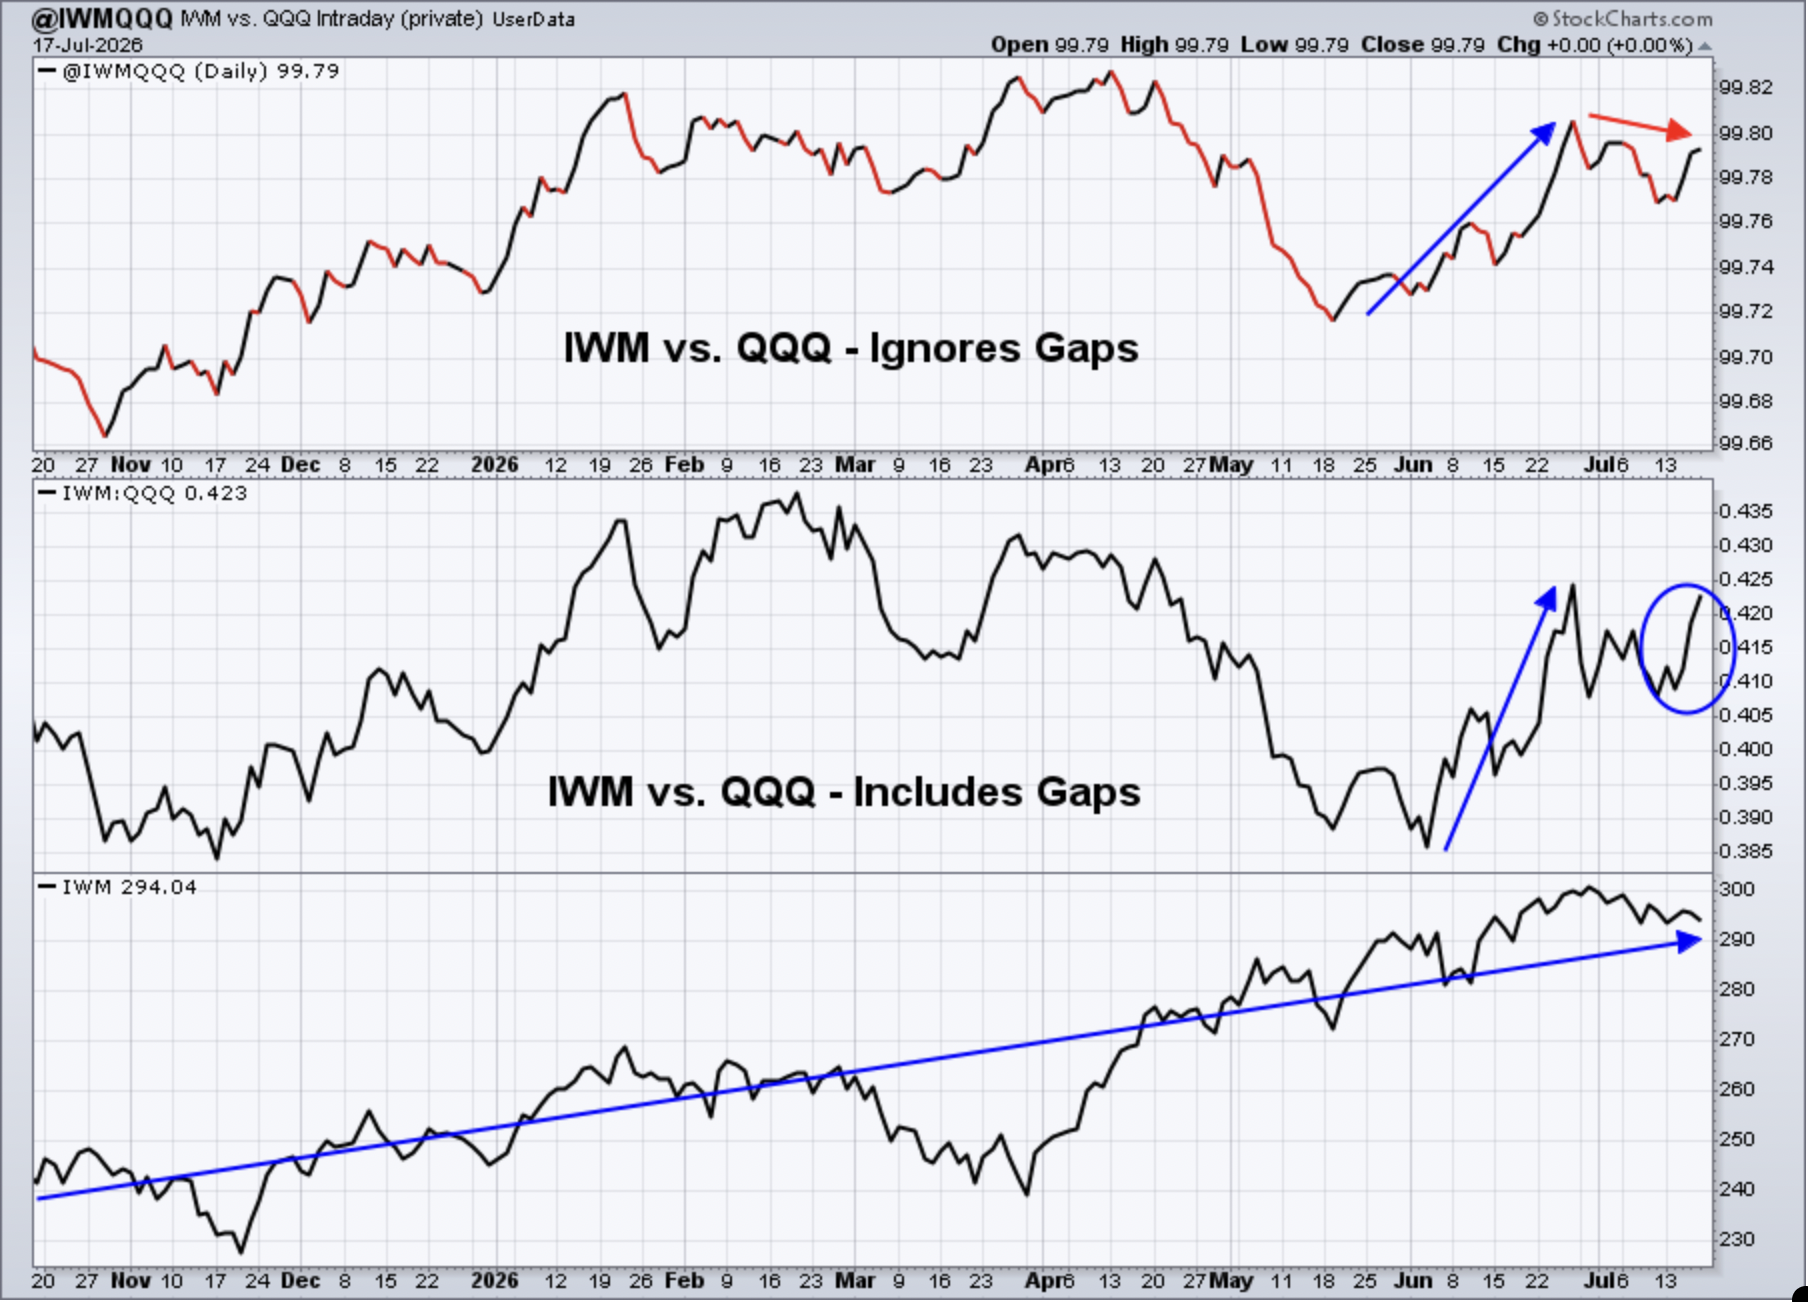
There was a clear bounce last week in small caps on a relative basis. While that was good to see, I doubt that it continues unabated. There are still concerns as to what the Fed's next move will be. That uncertainty will likely keep a lid on the IWM's relative outperformance. At least, that's what I'm expecting at this point. Regional banks (KRE) are the most influential area of small caps and a negative divergence printed on KRE's latest daily high. If that slowing momentum plays out and the KRE consolidates, or sells off briefly, it will make IWM outperformance less likely - for now.
XLY:XLP
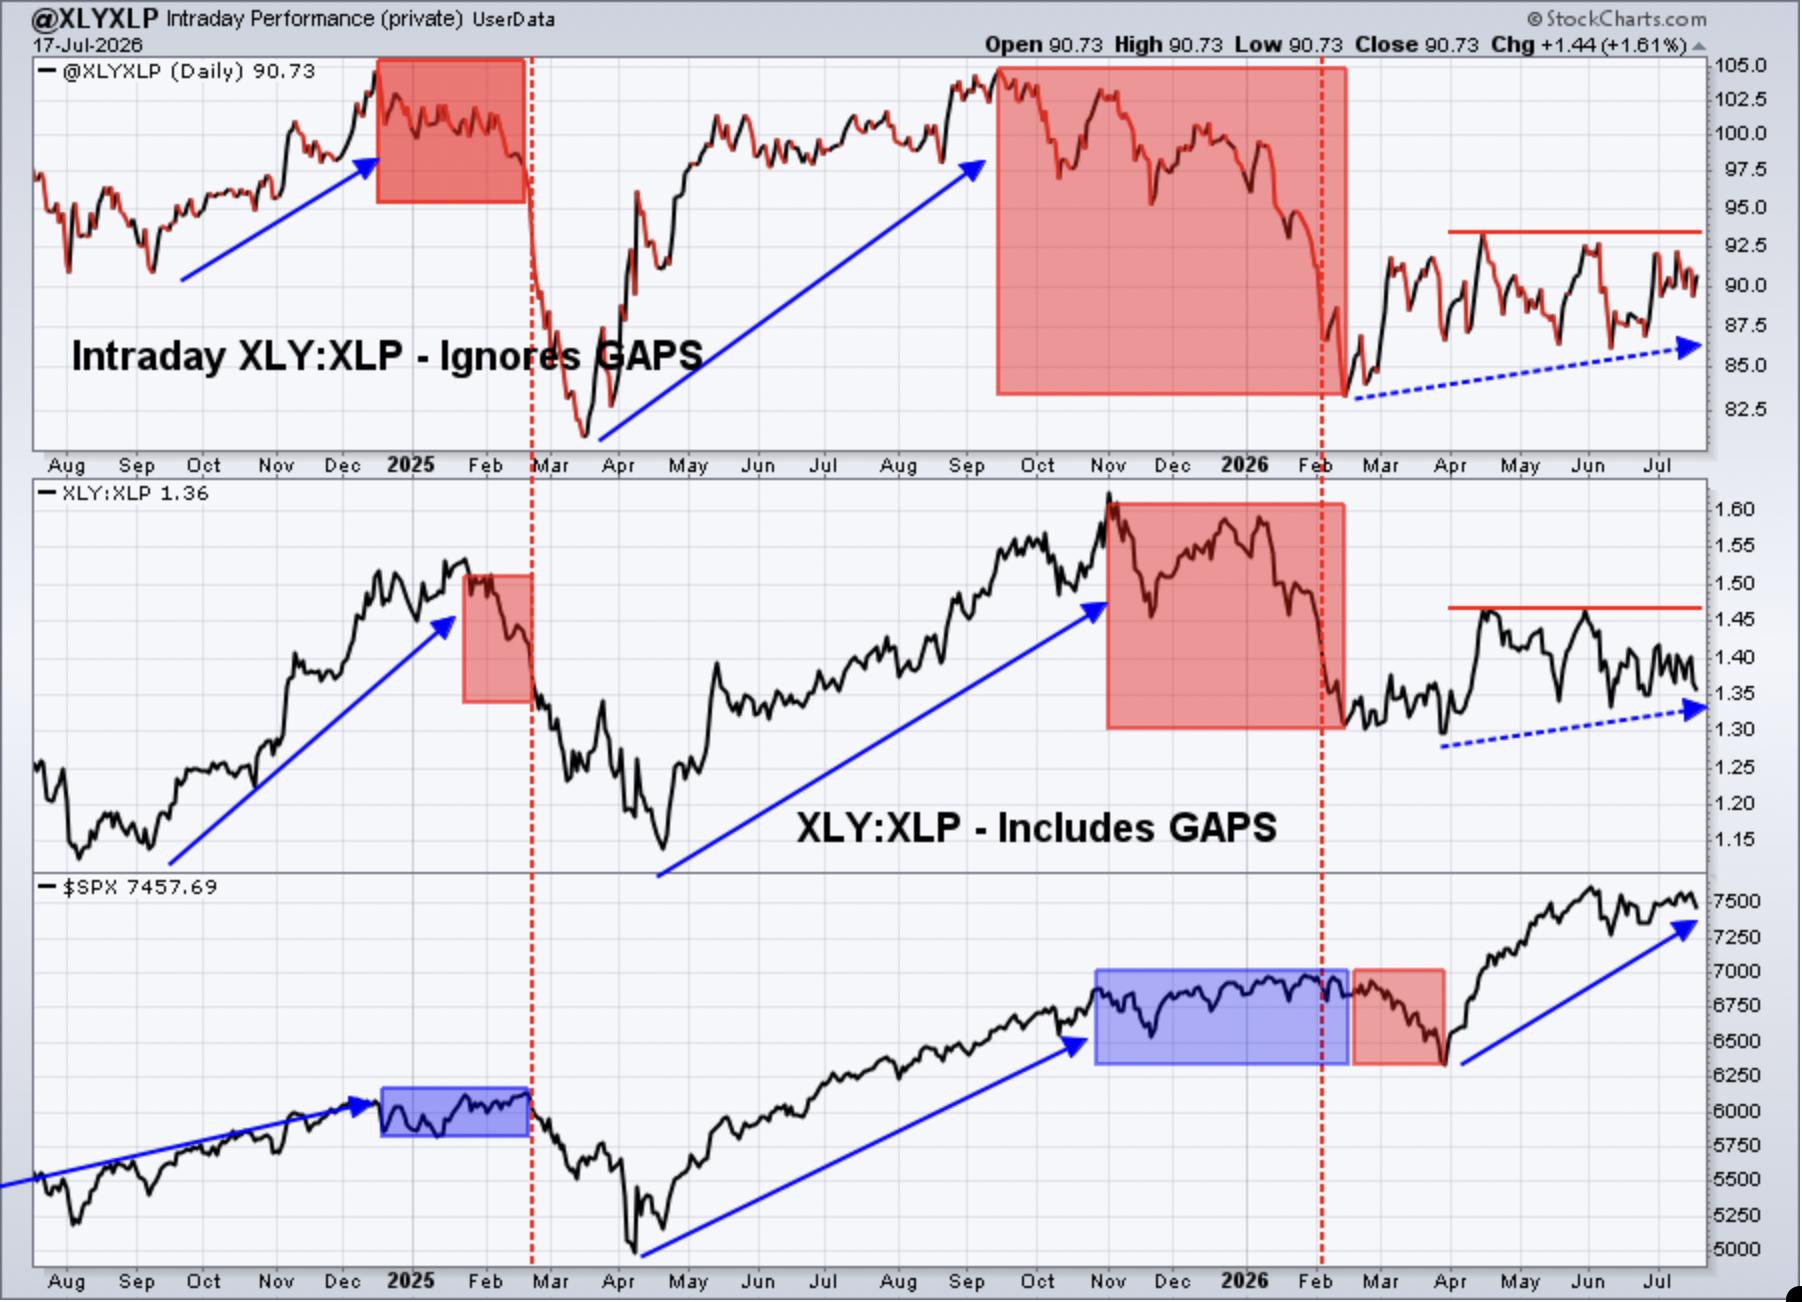
This relative ratio remains a challenge for the bulls as well. I find it slightly encouraging that the INTRADAY XLY:XLP ratio (Ignores Gaps) in the top panel remains close to a 6-month high. Ultimately, a break out above this red relative resistance line would argue for higher S&P 500 prices.
Sentiment
5-day SMA ($CPCE)
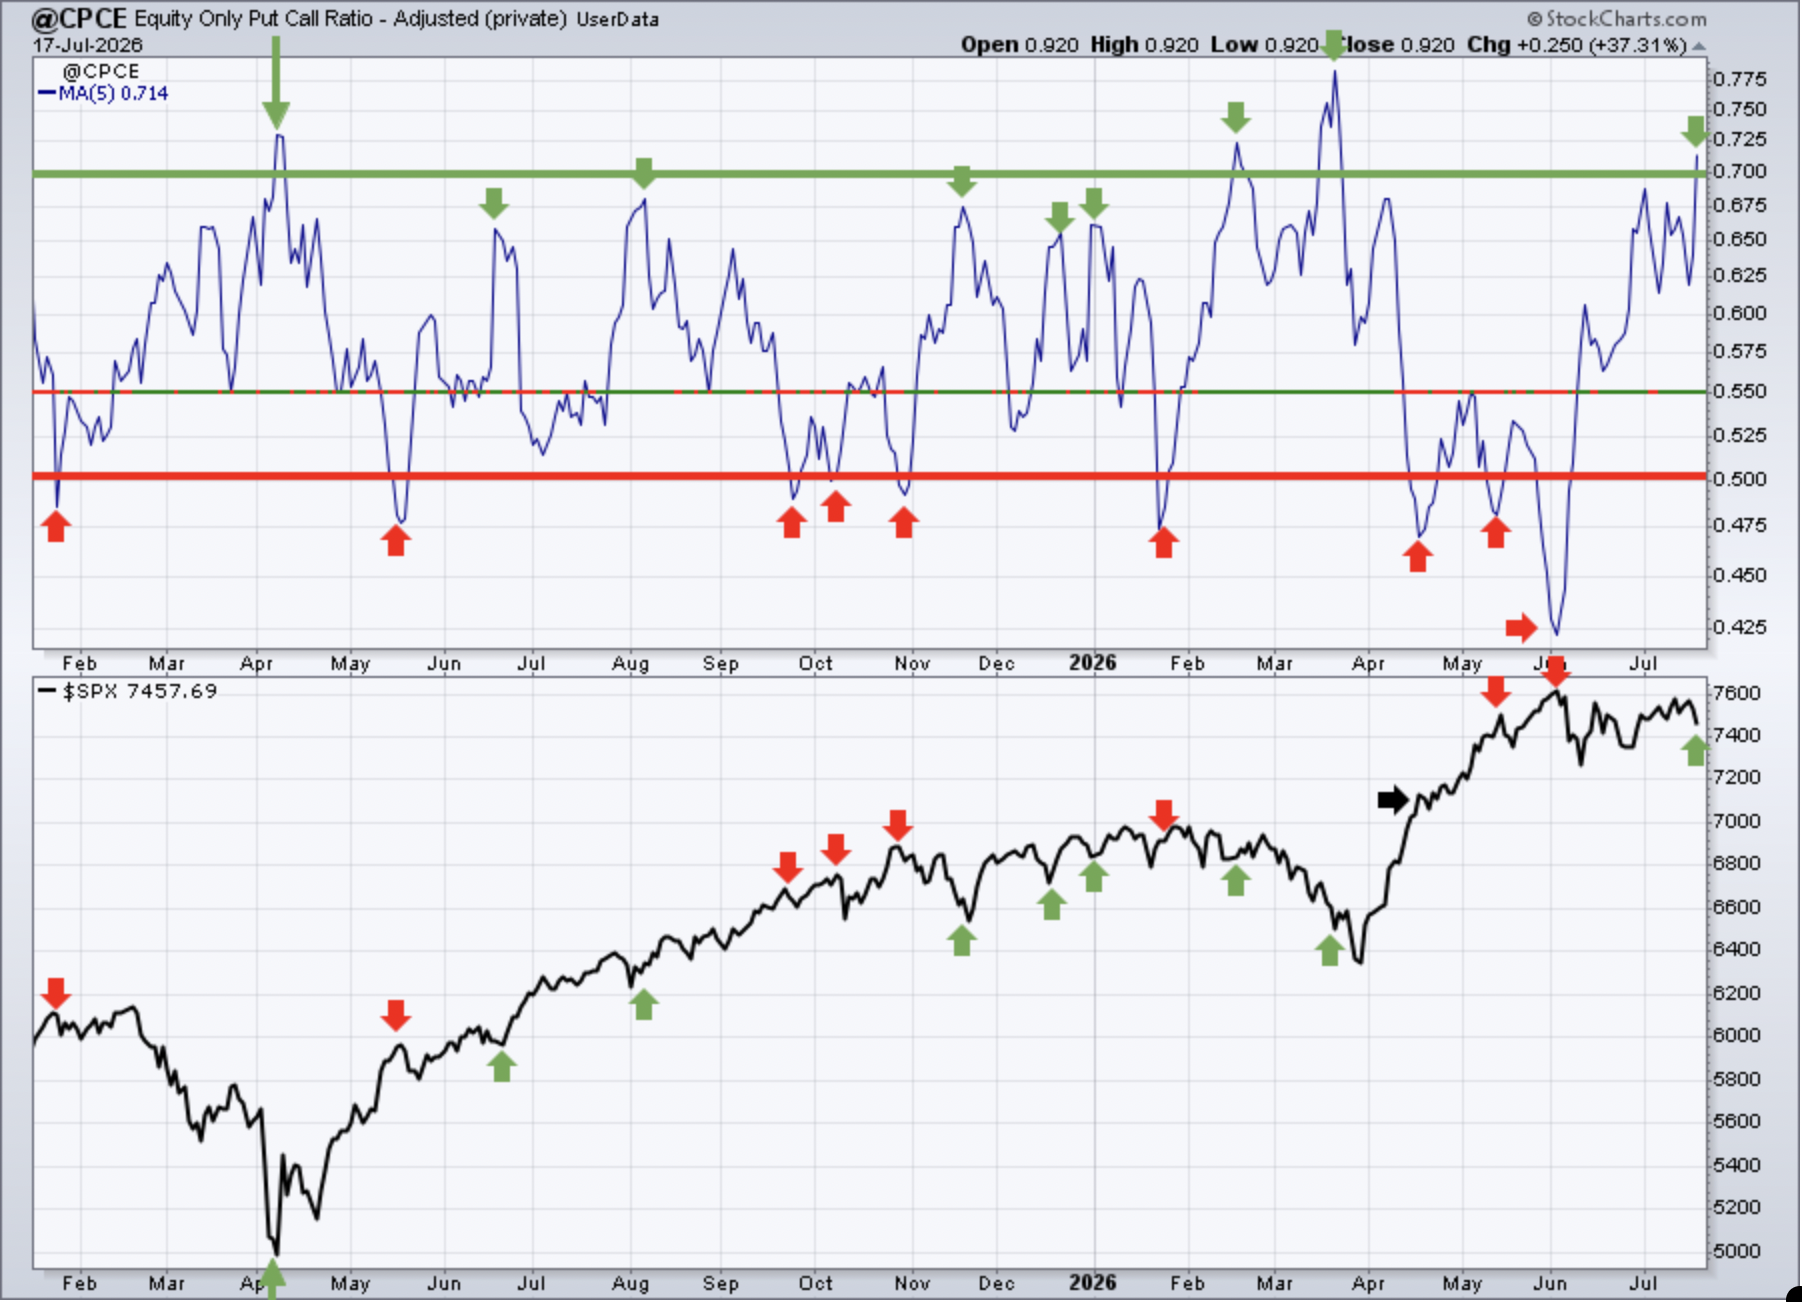
Sentiment indicators are contrarian indicators. When they show extreme bullishness, we need to be a bit cautious and when they show extreme pessimism, it could be time to become much more aggressive. Major market bottoms are carved out when pessimism is at its absolute highest level.
The 5-day SMA of the CPCE has moved above 0.70. Historically, any readings at .75 or higher tend to mark significant bottoms in the secular bull market, so this is an indication to me that we are probably closing in on a short-term bottom.
253-day SMA ($CPCE)
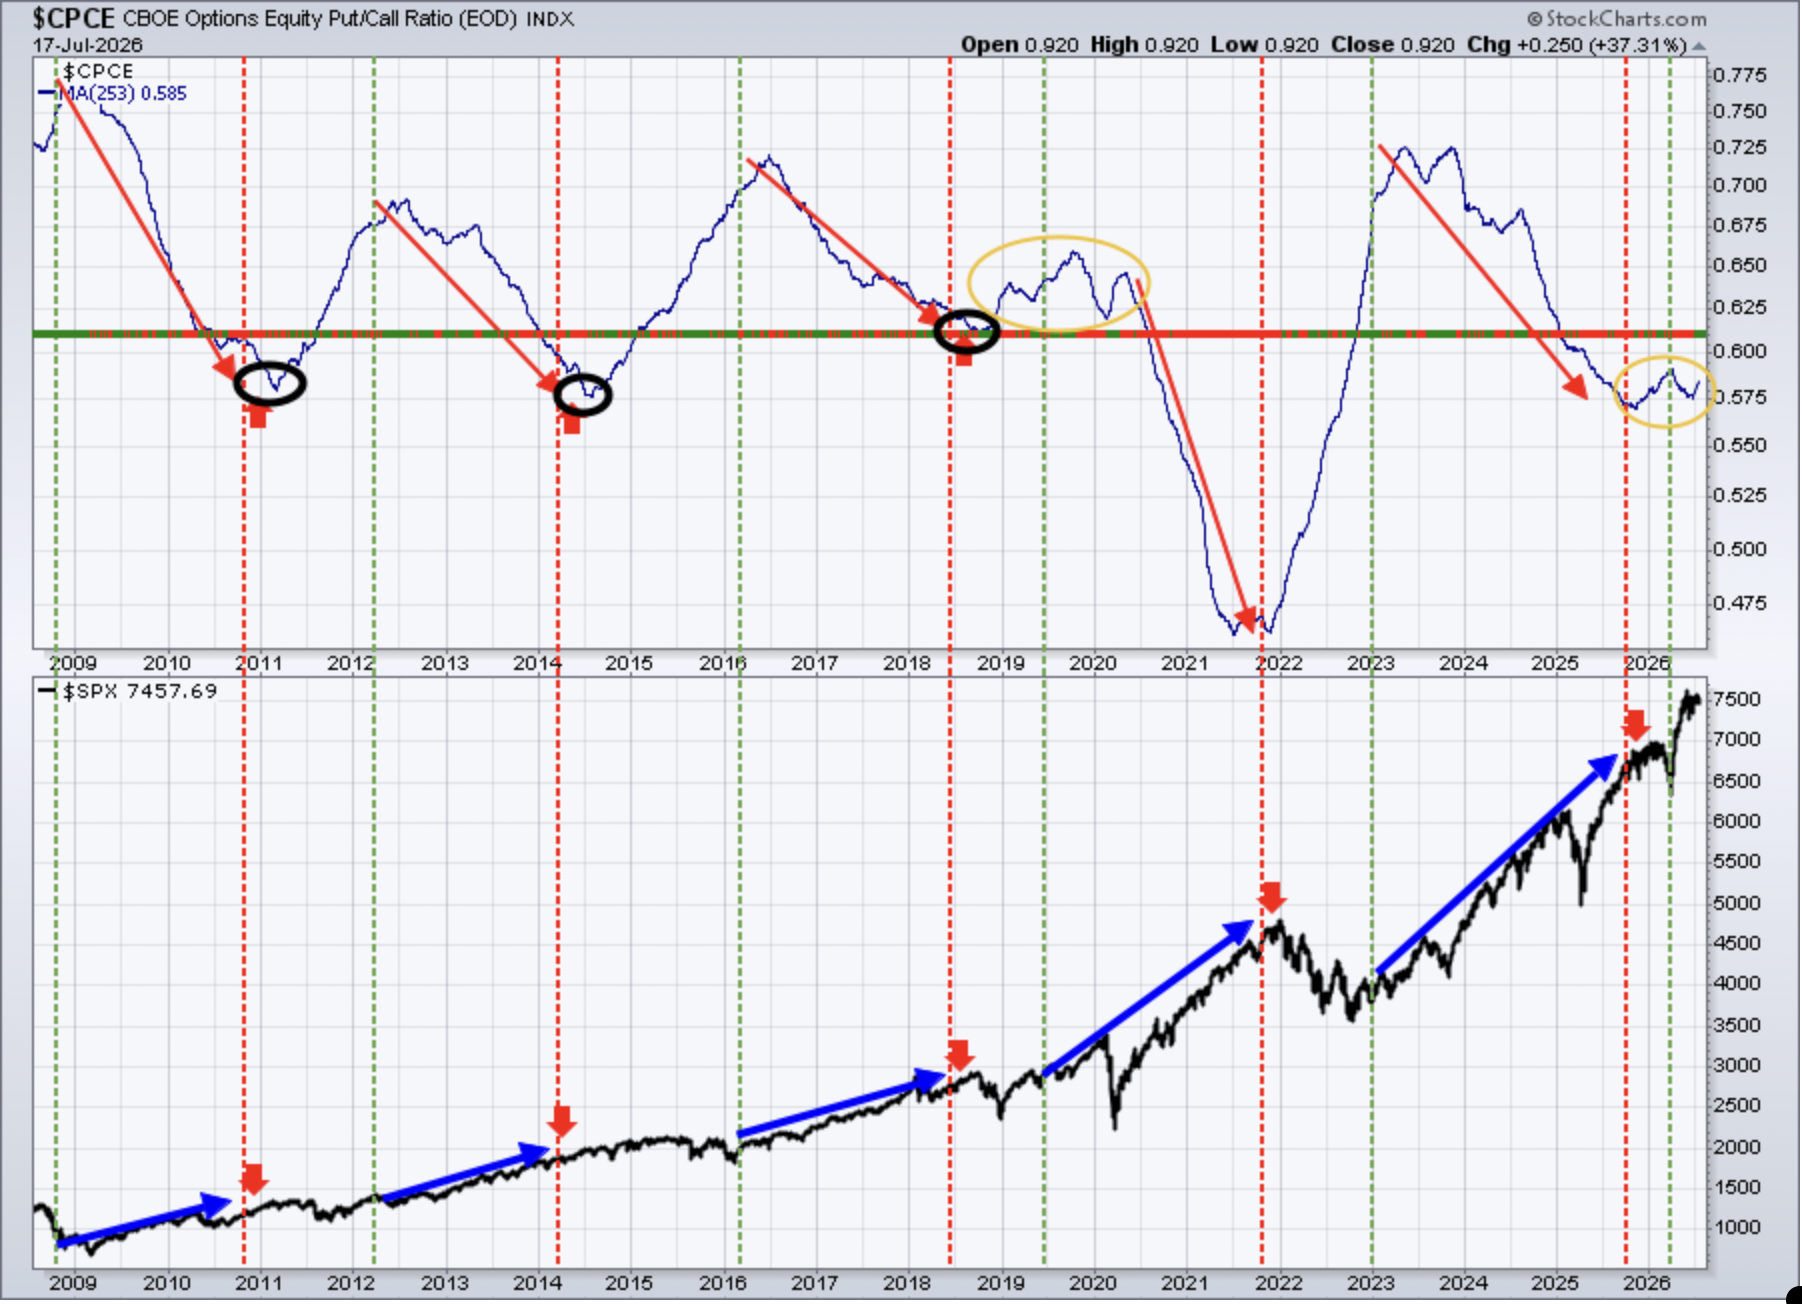
This longer-term 253-day SMA of the CPCE is our "ocean-liner" signal, unlike our short-term speedboat indicator. Any significant change in direction in this 253-day CPCE, in the past, has had profound effects on the S&P 500.
I've circled the indecision in this 253-day CPCE reading from 2019, because we seem to be shaping up the same way in 2026. A definitive break to a new low would be bullish and suggest further all-time highs ahead in our major indices. A more significant rise, however, would indicate the potential for storm clouds ahead. (No changes from last week)
Long-Term Trade Setups
Since beginning this Weekly Market Report in September 2023, I've discussed the long-term trade candidates below that I really like. Generally, these stocks have excellent long-term track records, and many pay nice dividends that mostly grow every year. Only in specific cases (exceptions) would I consider a long-term entry into a stock that has a poor or limited long-term track record and/or pays no dividends. I try to review the long-term picture once a month, and below is how I viewed each weekly chart as of the end of June:
- JPM - just completed right side of cup; possible handle to form, bullish
- BA - trending higher off April 2025 low, would like to see 200 support hold
- FFIV - very bullish chart, but overbought as it consolidates in bull flag
- MA - downtrending, but slight positive divergence; 475 is key support
- GS - pulling back from overbought conditions, 950 solid support
- FDX - negative divergence and bearish engulfing candle suggest more selling
- AAPL - might be best Mag 7 stock right now, tested 20-week EMA last week
- CHRW - appears to be forming right side of cup - bullish
- JBHT - solid uptrend intact, rising 20-week EMA is key support
- STX - weekly RSI been hanging near 90, last week's selling not a bad thing
- HSY - eversing piercing candle printed last week, looking for recovery
- DIS - consider 93-110 as the intermediate-term trading range
- MSCI - wondered if breakout was coming; emphatic no based on June trading
- SBUX - trending higher, looking for test of 113-114 price resistance
- KRE - solid month of June resulted in bullish breakout
- ED - excellent action last week, keeping uptrend intact in the process
- AJG - breakout above 20-week EMA after positive divergence says bottom is in
- NSC - trading in narrow 299-320 trading range
- RHI - moving thru 34 price resistance from January would be very bullish
- ADM - beautiful bounce off rising 20-week EMA
- BG - triple top breakout was 110 and that's where we tested last week on selling
- CVS - chart couldn't look much better; in breakout and all-time high territory
- HRL - last week's 9.73% gain seems to be indicating long-term bottom is in
- DE - 3-month downtrend ended in June; now looking at testing 675 resistance
- LULU - nice reversal last week, but massive downtrend remains in play
- TTD - broken stock and one of the worst relative performers in software
- META - weakening with possible test of 480-520 price support range upcoming
- ADBE - failed miserably at 20-week EMA and moved below 200 for first time since 2018
- KMB - surged 14% last week to test declining 20-week EMA for first time
- ORCL - huge 34% decline last week sets up another test near 140 support
- ABBV - rode the health care rally to its new all-time high
- MCD - weekly RSI at 34, generally solid long-term entry point
- MKC - nice reversal last week, perhaps it'll move up to test its declining 20-week EMA
Keep in mind that our Weekly Market Reports favor those who are more interested in the long-term market picture. Therefore, the list of stocks above are stocks that we believe are safer (but nothing is ever 100% safe) to own with the long-term in mind. Nearly everything else we do at EarningsBeats.com favors short-term momentum trading, so I wanted to explain what we're doing with this list and why it's different.
Also, please keep in mind that I'm not a Registered Investment Advisor (and neither is EarningsBeats.com nor any of its employees) and am only providing (mostly) what I believe to be solid dividend-paying stocks for the long term. Companies periodically go through adjustments, new competition, restructuring, management changes, etc. that can have detrimental long-term impacts. Neither the stock price nor the dividend is ever guaranteed. I simply point out interesting stock candidates for longer-term investors. Do your own due diligence and please consult with your financial advisor before making any purchases or sales of securities.
Looking Ahead
Upcoming Earnings
The following list of companies is NOT a list of all companies scheduled to report quarterly earnings, however, just key reports, so please be sure to check for earnings dates of any companies that you own. Any company in BOLD represents a stock in one of our portfolios and the amount in parenthesis represents the market capitalization of each company listed:
- Monday: None
- Tuesday: NVS ($291 billion), SCHW ($179 billion), IBKR ($156 billion), DHR ($145 billion), COF ($132 billion)
- Wednesday: GOOGL ($4.29 trillion), TSLA ($1.47 trillion), GEV ($278 billion), TXN ($265 billion), IBM ($206 billion)
- Thursday: INTC ($487 billion), RTX ($262 billion), TMUS ($209 billion), TMO ($202 billion), SAP ($199 billion)
- Friday: AXP ($247 billion), NEE ($186 billion), VZ ($183 billion)
Key Economic Reports
- Monday: June leading economic indicators
- Tuesday: None
- Wednesday: None
- Thursday: Initial jobless claims, June retail sales, July Philadelphia Fed manufacturing survey, June pending home sales, May business inventories
- Friday: July PMI manufacturing, July PMI services, June new home sales
Historical Data
I'm a true stock market historian. I am absolutely PASSIONATE about studying stock market history to provide us more clues about likely stock market direction and potential sectors/industries/stocks to trade. While I don't use history as a primary indicator, I'm always very aware of it as a secondary indicator. I love it when history lines up with my technical signals, providing me with much more confidence to make particular trades.
Below you'll find the next two weeks of historical data and tendencies across the three key indices that I follow most closely. The percentage for each calendar day represents the annualized return for that day. An example of how this is calculated is reflected next to the first day under the S&P 500 and in parenthesis:
S&P 500 (since 1950)
- Jul 20: -3.71% (Ex: cumulative gains =
-0.79% over 53 trading days since 1950. -0.79% x 253/53 = -3.71%) - Jul 21: -27.81%
- Jul 22: -9.16%
- Jul 23: -25.38%
- Jul 24: -4.25%
- Jul 25: +19.06%
- Jul 26: +30.43%
- Jul 27: +9.03%
- Jul 28: -21.24%
- Jul 29: +35.55%
- Jul 30: +59.54%
- Jul 31: +19.78%
- Aug 1: -24.59%
- Aug 2: +10.21%
NASDAQ (since 1971)
- Jul 20: +22.38%
- Jul 21: -54.01%
- Jul 22: -2.53%
- Jul 23: -86.23%
- Jul 24: -47.40%
- Jul 25: +32.54%
- Jul 26: +18.91%
- Jul 27: -16.15%
- Jul 28: -50.31%
- Jul 29: +17.57%
- Jul 30: +30.33%
- Jul 31: +12.25%
- Aug 1: -65.00%
- Aug 2: -2.93%
Russell 2000 (since 1987)
- Jul 20: +25.11%
- Jul 21: -95.09%
- Jul 22: +42.13%
- Jul 23: -71.17%
- Jul 24: -91.83%
- Jul 25: +46.35%
- Jul 26: +56.13%
- Jul 27: -61.56%
- Jul 28: +10.09%
- Jul 29: +96.80%
- Jul 30: +59.48%
- Jul 31: -23.30%
- Aug 1: -78.14%
- Aug 2: -88.19%
The S&P 500 data dates back to 1950, while the NASDAQ and Russell 2000 information date back to 1971 and 1987, respectively.
Final Thoughts
Clearly, the market's appetite for risk has diminished in recent weeks. It's evident when we look at the riskiest area of the market - semiconductors - and the plunge they've taken. The long-term trend in the group most definitely remains higher, so I'd be careful growing too pessimistic. I understand the short-term downtrend that's taken place, but as long as price action remains above its rising 20-week EMA, I'd give the benefit of the doubt to the bulls.
This past week was also July monthly options-expiration week. That can create a bearish environment for U.S. stocks, especially those that previously had been up trending. It'll be more telling to watch to see how we end the month as huge earnings reports are released.
Here's what I'll be thinking about this week:
Earnings. We haven't really seen the pre-earnings run up that we typically see during the first half of July. That could be a function of the massive push higher earlier in Q2. It's hard to tack on gains after we see more than a 10% move higher in one month. Consolidation is normal.
Seasonality. We're in a rough week historically. The July 17th close through the July 24th close has been the 3rd worst week of the year, dating back to 1950, trailing only one-week periods in September and October. This certainly doesn't guarantee us lower prices this week, but I'm always aware of historical tendencies.
Technical Conditions. This is a very light week in terms of economic reports. And while earnings reports will be accelerating, the really big companies will mostly start reporting next week. Alphabet (GOOGL) and Tesla (TSLA) are two exceptions as they will both report their latest quarterly results on Wednesday, after the closing bell.
Interest Rates. This is one of our best clues as to what Wall Street is thinking about inflation. If inflation expectations rise, so too should the 10-year treasury yield ($TNX). Currently, I view the TNX to be in a range from 4.25-4.35% to the downside and 4.70-4.80% to the upside. I'd grow much more concerned if the TNX were to pierce 4.80% and begin to challenge major yield resistance at 5.00%, set in October 2023.
Happy trading!
Tom