
EB Weekly Portfolio Report - Sunday, July 19, 2020
Upcoming Earnings Reports
According to Zacks.com, the following companies will be reporting earnings this week and each is a component of one of our portfolios:
Monday, July 20: CDNS
Tuesday, July 21: None
Wednesday, July 22: MSFT, TSLA, CMG
Thursday, July 23: AMZN
Friday, July 24: None
PLEASE NOTE: The above companies were provided after scanning the Zacks Earnings Calendar. My research is limited to what Zacks provides and I also can make a mistake from time to time, so please check for earnings dates for all companies that you own. We do hold our portfolio stocks through one earnings report, but every EarningsBeats.com member must make their own investing/trading decisions about holding stocks into earnings reports as it's the most volatile (risky) time to own a stock.
Portfolio Rules and Objectives
Here are the common traits and objectives of each portfolio, some of these were changed for our May 19th "draft" day recently (changes for the May 19 to August 19 quarter are in bold italics):
- We have removed the Character Change portfolio and added a new Strong AD portfolio
- There are 10 leading stocks from up to 10 leading industries in each portfolio (at the time of selection). Generally, there will only be one stock per industry group, but there could be exceptions.
- They are held for an entire 90 day period, with no stops in place. We strive for consistency, transparency, and simplicity in our portfolios. EB.com members may hold these stocks for the entire 90 days, trade them, use stops, etc., but for purposes of our calculation, we will make no exceptions to our "buy and hold for three months" strategy.
- Every stock will generally be held through ONE earnings report
- The expectation is that relative winners will carry the portfolio to outperformance
- They will all be entered into as of close on Tuesday, May 19th; members may choose to try to time better entries, but EB.com will "purchase" as of May 19th's closing price
- Primary objective is to outperform the benchmark S&P 500
Here are several considerations for EB members:
- I would expect the Strong AD and Aggressive portfolios to be the riskiest, followed by the Model portfolio, and then the Income portfolio
- The Strong AD portfolio will be selected from a combination of rising accumulation/distribution lines and SCTRs above 80 at the time of selection. It will be our only portfolio that does NOT require a revenue and EPS beat in its most recent quarterly earnings report
- The Income portfolio stocks will all pay dividends, with the expected average dividend yield to be at least 1.5%
- Drawdowns (losses) should be much milder on the Income portfolio, with more volatility expected on the other three; please review inception-to-date charts below to gain an idea of the volatility associated with each
- I believe the larger drawdown on the Income portfolio last quarter was an anomaly occurring as a result of the pandemic as many defensive, higher-yielding companies uncharacteristically underperformed during a market decline.
- You should own or trade these stocks in whatever manner is most comfortable for you; while we will buy all 10 stocks in the manner identified above, feel free to trade certain stocks or wait for pullbacks if the stocks are overbought
- We have no idea what risk each member is willing or able to take. We are not registered investment advisors so be sure you understand the risk you take. Please consult your financial advisor.
- EarningsBeats.com shareholders/employees may own all or some of the portfolio stocks from time to time.
Weekly Snapshot
Here's a weekly recap:
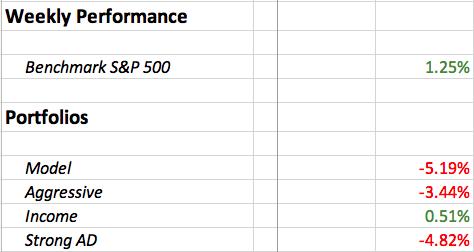
Overall, it was a decent week for U.S. equities. Unfortunately, that strength did not translate into gains in our portfolios, as our portfolios lagged rather badly.
Weekly Summary
Benchmark S&P 500:
The S&P 500 gained 1.25% last week. To an outsider, it might seem as though the market was just doing what it's been doing since the March low. But last week was different if you study the stock market closely. Leadership was completely different. Three of the worst performing sectors were technology (XLK), communication services (XLC), and consumer discretionary (XLY). The XLK and the XLC were the only two sectors that finished the week lower than it started. In particular, software ($DJUSSW) and internet ($DJUSNS), were the primary reasons for such underperformance. The former fell nearly 5% as it suffered through easily its worst week since the March low.
Meanwhile, the sectors gaining 3% or more included: industrials (XLI), materials (XLB), health care (XLV), utilities (XLU), and energy (XLE). Of these five, health care broke out and is poised to regain the leadership role it had during the first month of this pandemic. Materials are also gaining strength, though their longer-term health will depend quite heavily on whether the long-term uptrend in the U.S. Dollar ($USD) holds trendline support. We're approaching that support now.
Our portfolios and much of our strategy is based on growth stocks outperforming their value counterparts. Our portfolio weakness this past week can be summed up in the following growth vs. income chart:
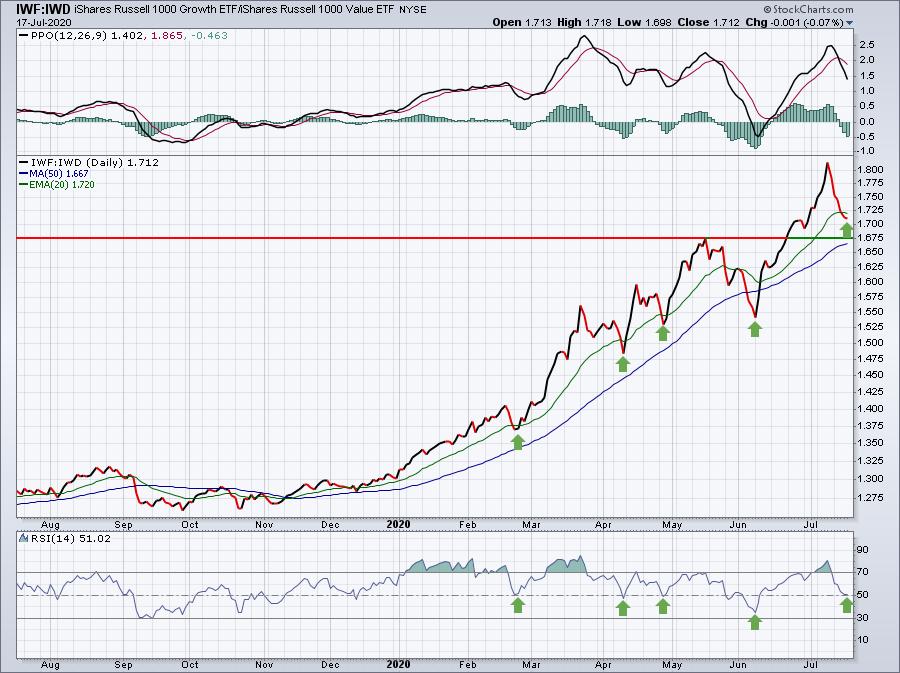
When this IWF:IWD ratio's RSI reaches overbought (above 70, especially at 80), our portfolios are set up to show short-term relative weakness. However, when this ratio's RSI falls to 50 or below, that's previously suggested buy points for growth stocks.
Model Portfolio:
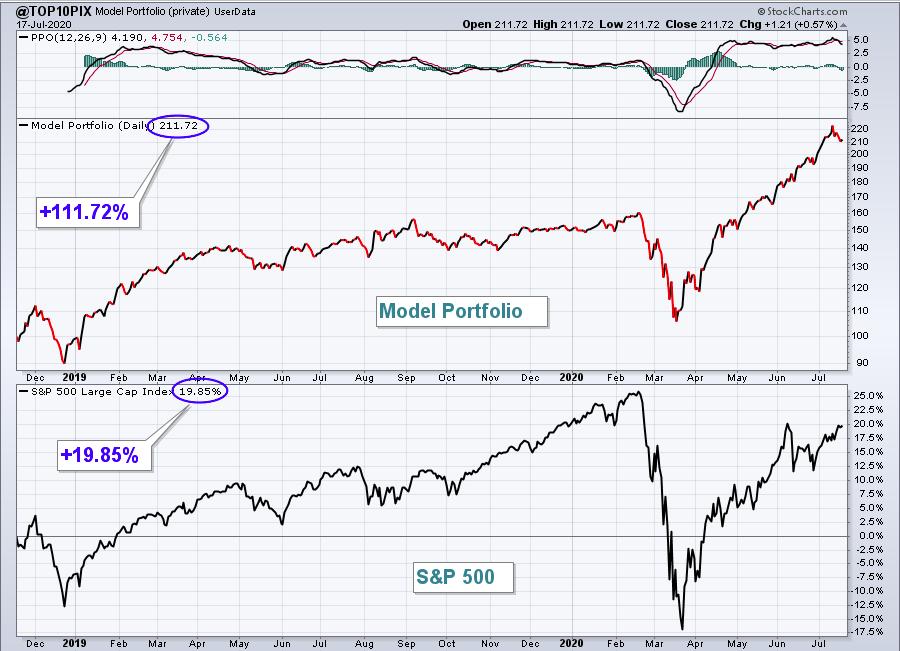
The Model portfolio had its worst week since March, dropping 5.19%. Here's the updated inception-to-date chart of the portfolio:
Here are how the Model portfolio component stocks performed last week:
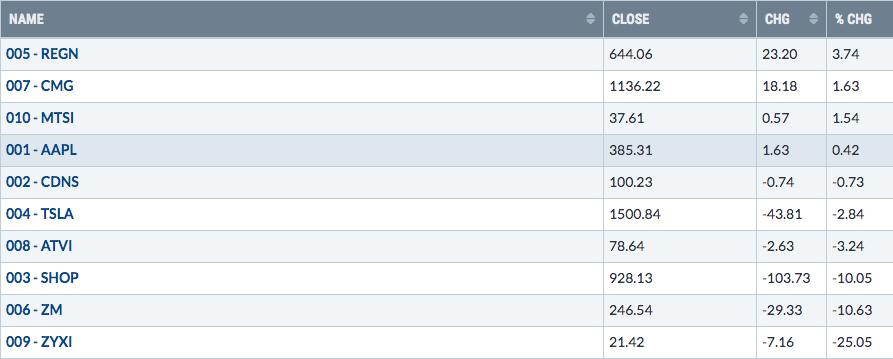
The big hit here came from ZYXI, which announced a secondary offering, and two technology high-flyers, SHOP and ZM, which saw its first meaningful profit taking in over a month. The other 7 components, on a net basis, were relatively flat.
Aggressive Portfolio:
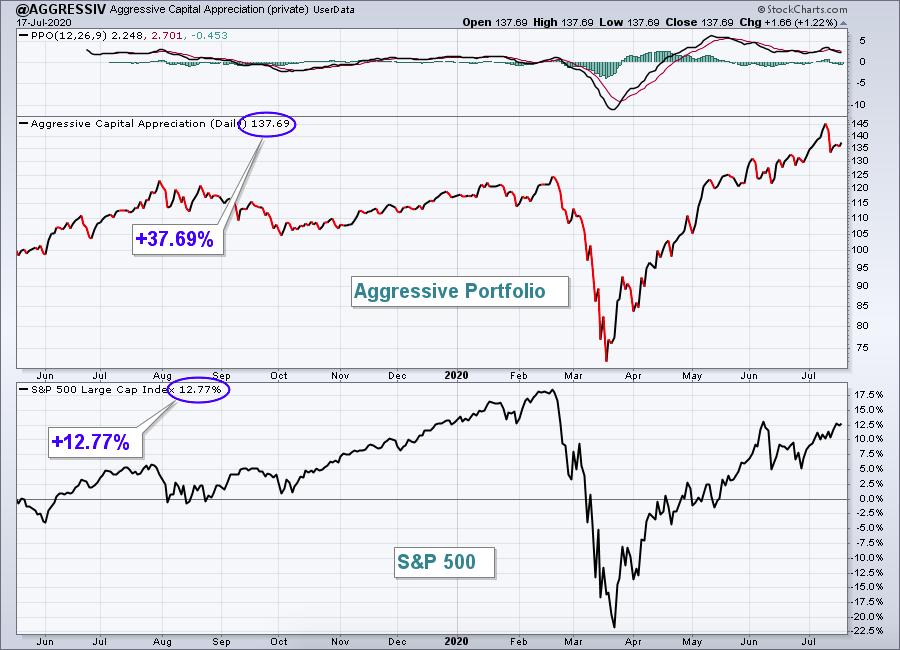
The Aggressive portfolio dropped 3.44% last week, ending its recent relative winning streak vs. the S&P 500. Here's the Aggressive portfolio chart since its inception on May 19, 2019:
Here are how the Aggressive portfolio component stocks performed last week:
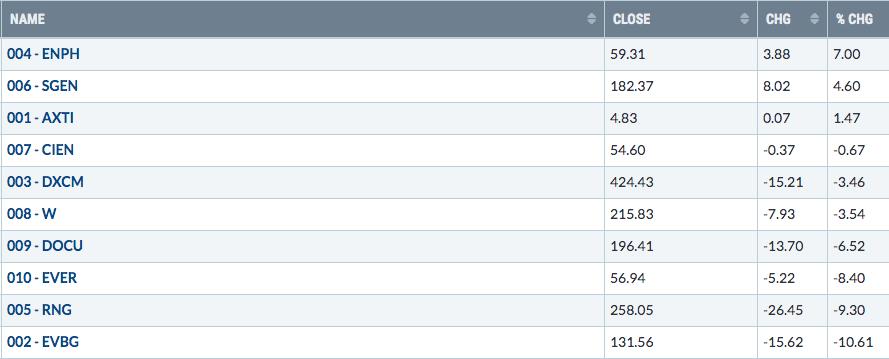
EVBG was the big loser, but it's a part of software and, unfortunately, most software stocks were shunned by traders last week.
Income Portfolio:
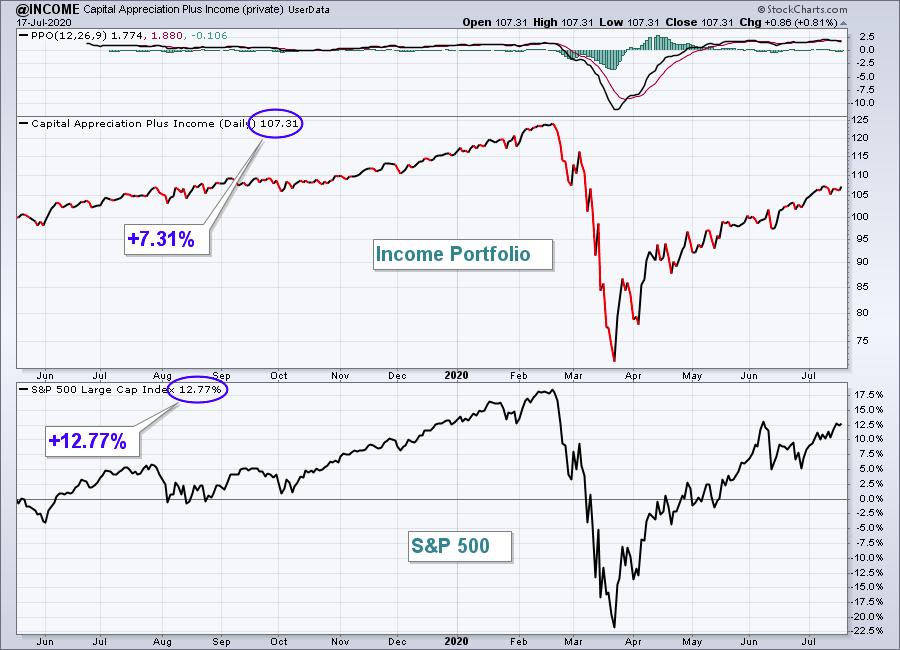
The Income portfolio was the only portfolio that managed to stay near the benchmark, rising 0.51%. Here's a look at the inception-to-date chart:
Here are how the Income portfolio component stocks performed last week:
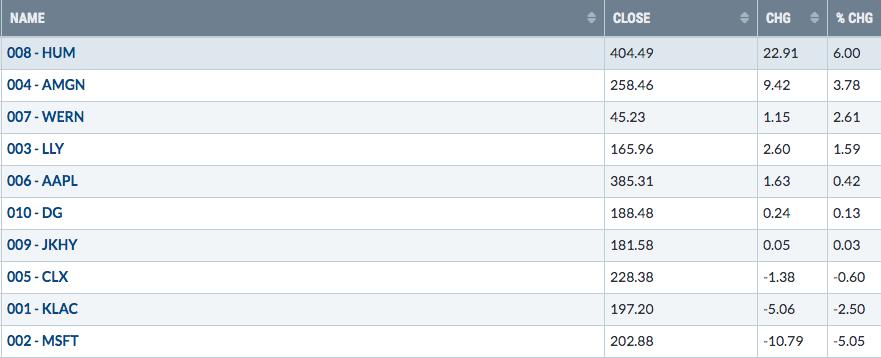
If it weren't for the lone software stock here, MSFT, the Income Portfolio would have kept pace with the S&P 500. 7 of the 10 components here gained ground.
Strong AD Portfolio:
The Strong AD Portfolio tumbled 4.82%, also suffering from the rotation out of growth stocks. Here's a look at the inception-to-date chart:
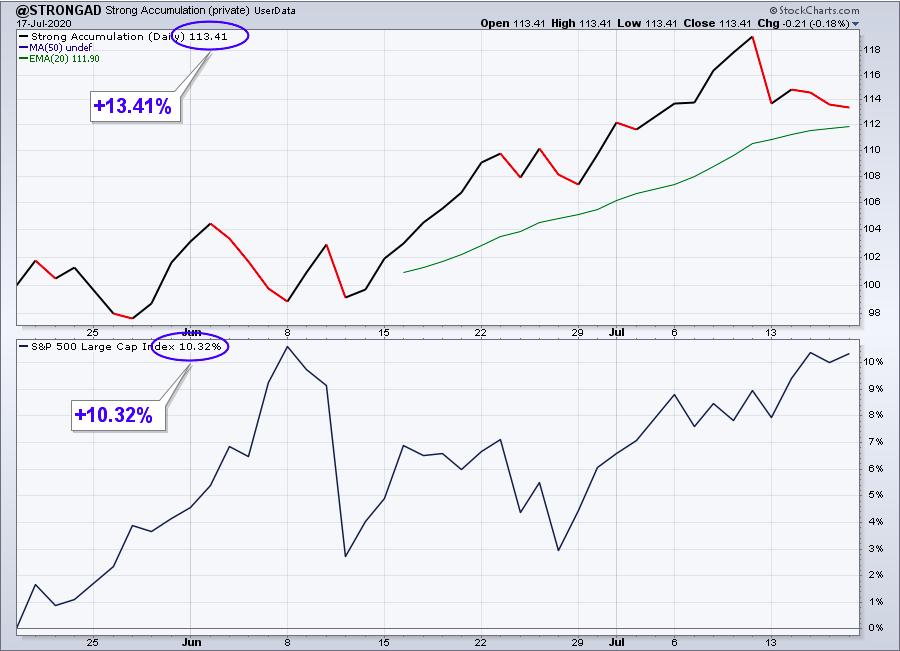
Here are how the Strong AD portfolio component stocks performed last week:
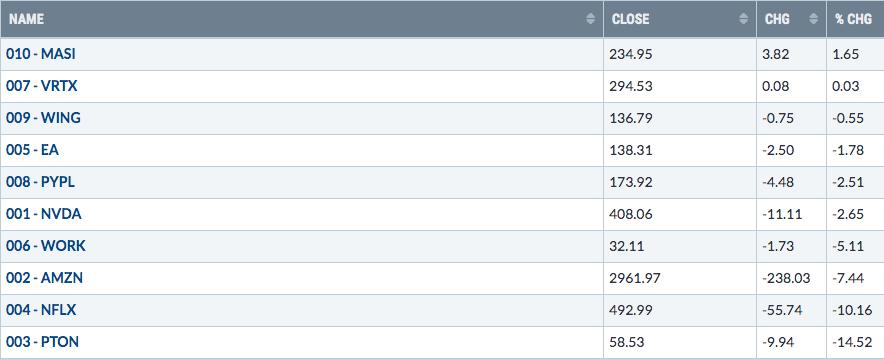
Netflix (NFLX) definitely contributed to the Strong AD Portfolio's relative weakness last week, posting uninspiring quarterly results on Thursday after the closing bell. I was surprised it didn't fall further after it came up short on its EPS estimate. PTON's big drop was its first significant selling since the second half of May:
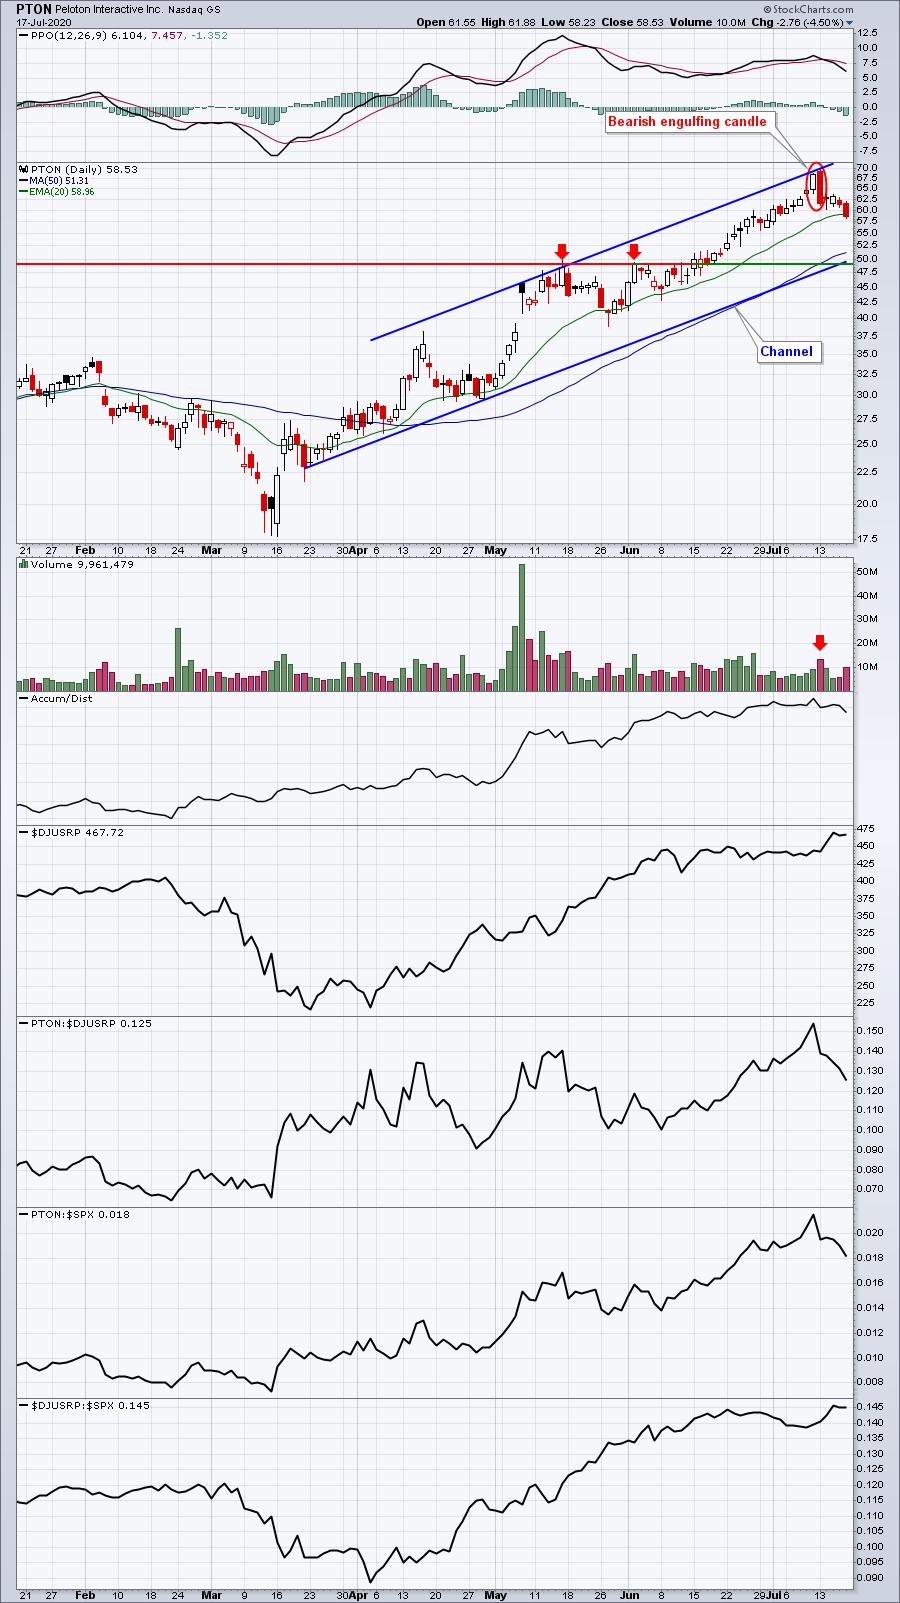
I remain a big fan of PTON, but more short-term selling cannot be ruled out. If PTON were to move back into the low-50s, there'd be a lot of panic among those that bought near 70. I believe buyers would absolutely return in droves to accumulate shares at that level, should PTON drop that far.
Summary
The weakness in our portfolios on a relative basis was inevitable. You simply cannot expect to outperform the benchmark S&P 500 the way that our portfolios had for weeks on end. The party had to come to an end, or at least a pause. That's what we saw last week. I reported a week ago Friday and throughout this past week that rotation was taking place and that had a detrimental impact on our portfolio performance. While that may continue in the very short-term, I do believe that it's nearing its completion.
I love the breakout last week in health care stocks (XLV). One piece of very good news is that we currently have significant portfolio exposure to that area of the market, as 9 of our 40 portfolio stocks represent the health care sector. Assuming health care resumes a leadership role, which I expect it will, that should help to soften any blow from further weakness in technology and communication services.
Happy trading!
Tom Bowley, Chief Market Strategist
EarningsBeats.com
"Better timing. Better trades."