
EB Daily Market Report - Tuesday, October 8, 2019
Executive Market Summary
- September PPI falls 0.3%, way below expected rise of 0.1%; Core PPI also down 0.3%
- The Fed MUST cut rates later this month given the big miss in PPI
- Major indices down over 1% as selling kicks in
- Financials, especially banks ($DJUSBK, -2.28%), hit hard as "deflationary" data suggests further rate cuts ahead
- Defensive sectors leading....as they usually do on down days
- 5 active alerts now: They're currently mixed today, but remain fine technically (more below)
Market Outlook
This month's FOMC meeting will be interesting. One voting Fed member wanted a 50 basis point reduction in the fed funds rate last month (I did too) and it turns out he was probably right. My biggest concern is NOT the weakness in the economy. It is about stabilizing prices. With a strengthening dollar over the past 8 years, commodities ($CRB) have suffered. They've suffered to the point that the Fed should be worried about deflation:
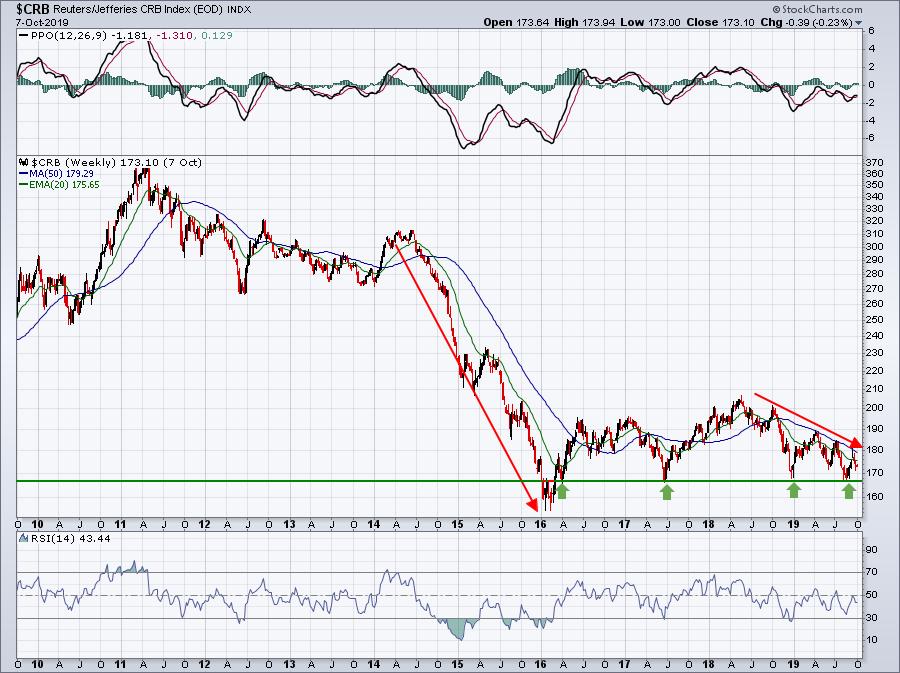
Over the past 15 months, the CRB Index has been tumbling once again. The initial top, back in 2011, occurred when the U.S. Dollar Index ($USD) bottomed. Since then, a surging dollar has kept constant pressure on commodity prices. The CRB is now approaching a key level of support near 167. Failure to hold that support level will only add to further disinflationary (or deflationary) pressures. The Fed needs to act BOLDLY to "inflate" prices. Again, this has NOTHING to do with economic weakness, although the Fed also has last week's ISM manufacturing index (which came in well below 50 indicating economic contraction) to further promote an aggressive rate cut of 50 basis points. Such a cut will weaken the dollar, allowing the CRB to rebound. It also will provide our economy a cushion against further deterioration.
I have been outspoken against Fed Chair Jerome Powell. I believe he's been WAY slow to act and been flat out wrong on a few occasions already. I hope he gets this one right.
Sector/Industry Focus
Sticking with the commodities theme today, let's check out copper prices ($COPPER). Among gold, silver and copper, copper is the one that has the strongest positive correlation with global equity markets. When foreign markets are strong or strengthening, the market for copper picks up and prices rise. When economic demand is weak, the opposite holds true. Here's a current look at the COPPER chart:
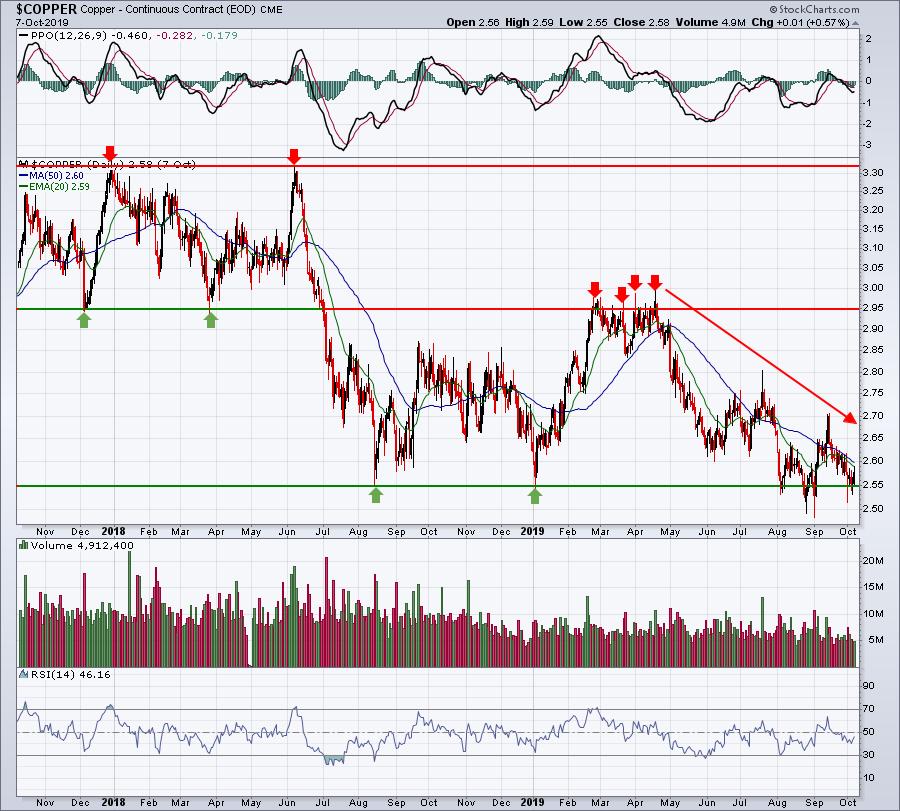
Do you remember Powell saying that lower inflation was "transitory" (meaning temporary) back in the spring? Do you see anything "transitory" about the drop in copper prices? In 2011, copper prices were 4.70. Now they're 2.58!!! The Fed NEEDS to weaken the U.S. Dollar ($USD) to "inflate" prices. There is nothing worse than deflation for equities. The PPI report will twist Powell's arm.
Strong Earnings ChartList (SECL)
I am avoiding the temptation of buying more stocks into today's weakness. We already have 5 trades that are active and the Volatility Index ($VIX) is on the rise. Let's see that sentiment indicator settle down a bit. Here's a current look at the VIX and the recent uptrend:
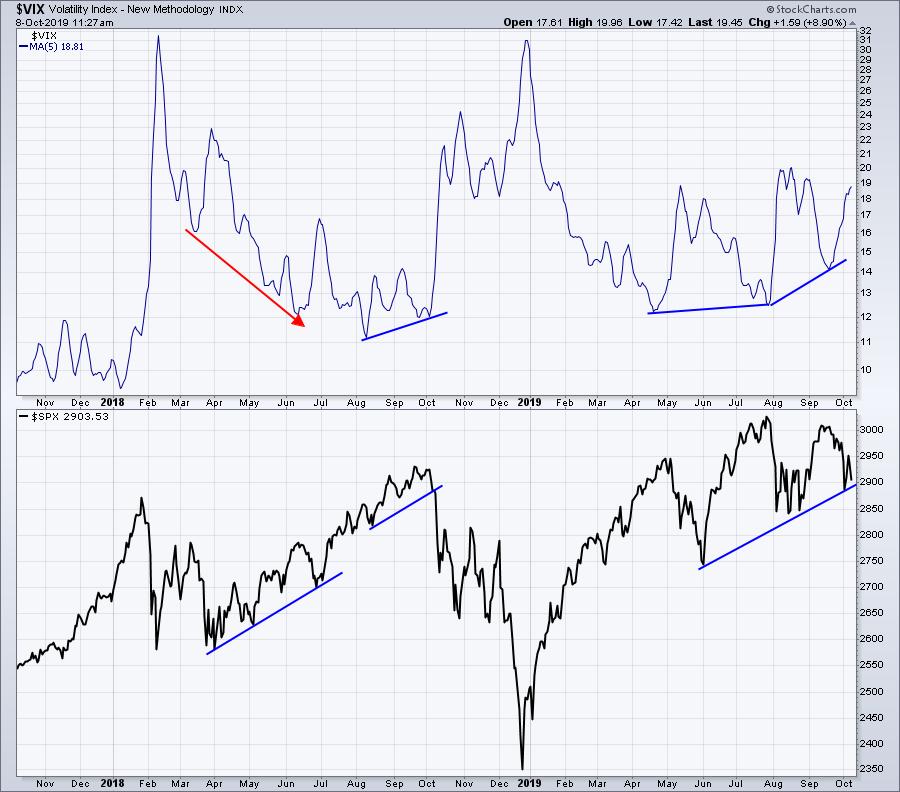
The uptrend in the S&P 500 from April through July 2018 resulted in a downtrend in the VIX, which is exactly what should happen. However, check out the S&P 500 uptrend in August/September. It coincided with a rising VIX and more selling ensued. I'm not sure we see much more selling this year, but what the rising VIX tells us is that the market remains nervous and fearful. That suggests that stops remain fairly tight and in place in the event the market rolls over for another selling episode.
Current Alerts
Here are our current active trade alerts:
ROKU (+0.39%) - up this morning, which is a good thing given the market's overall weakness. A very conservative approach (and a guarantee to lock in profits) would be an INTRADAY stop beneath 104. Since we saw heavier volume accompany a break above 104, we have not seen any intraday move below that level.
NOC (+0.00%) - defense stocks ($DJUSDN) have rallied a bit today and NOC continues to be a relatively strong performer in the group. Not bad action.
ZBH (-2.25%) - medical equipment stocks ($DJUSAM) were weak yesterday and are weak again today. ZBH was spared yesterday with an upgrade. Today, however, ZBH is caught up in the industry's weakness.
TWTR (-1.84%) - internet stocks ($DJUSNS) have been weak since the opening bell. October is generally very kind to this group, so we're fine giving TWTR a bit more rope and leeway.
ZUMZ (-2.16%) - down on very light volume. I see no significant distribution at this point, just normal back and forth action. A second entry remains in play here at 29.50 with a closing stop beneath 29.00.
All 5 alerts remain fine technically.
Today's Movers
Here are two large cap stocks worth mentioning given today's market selloff:
NVDA:
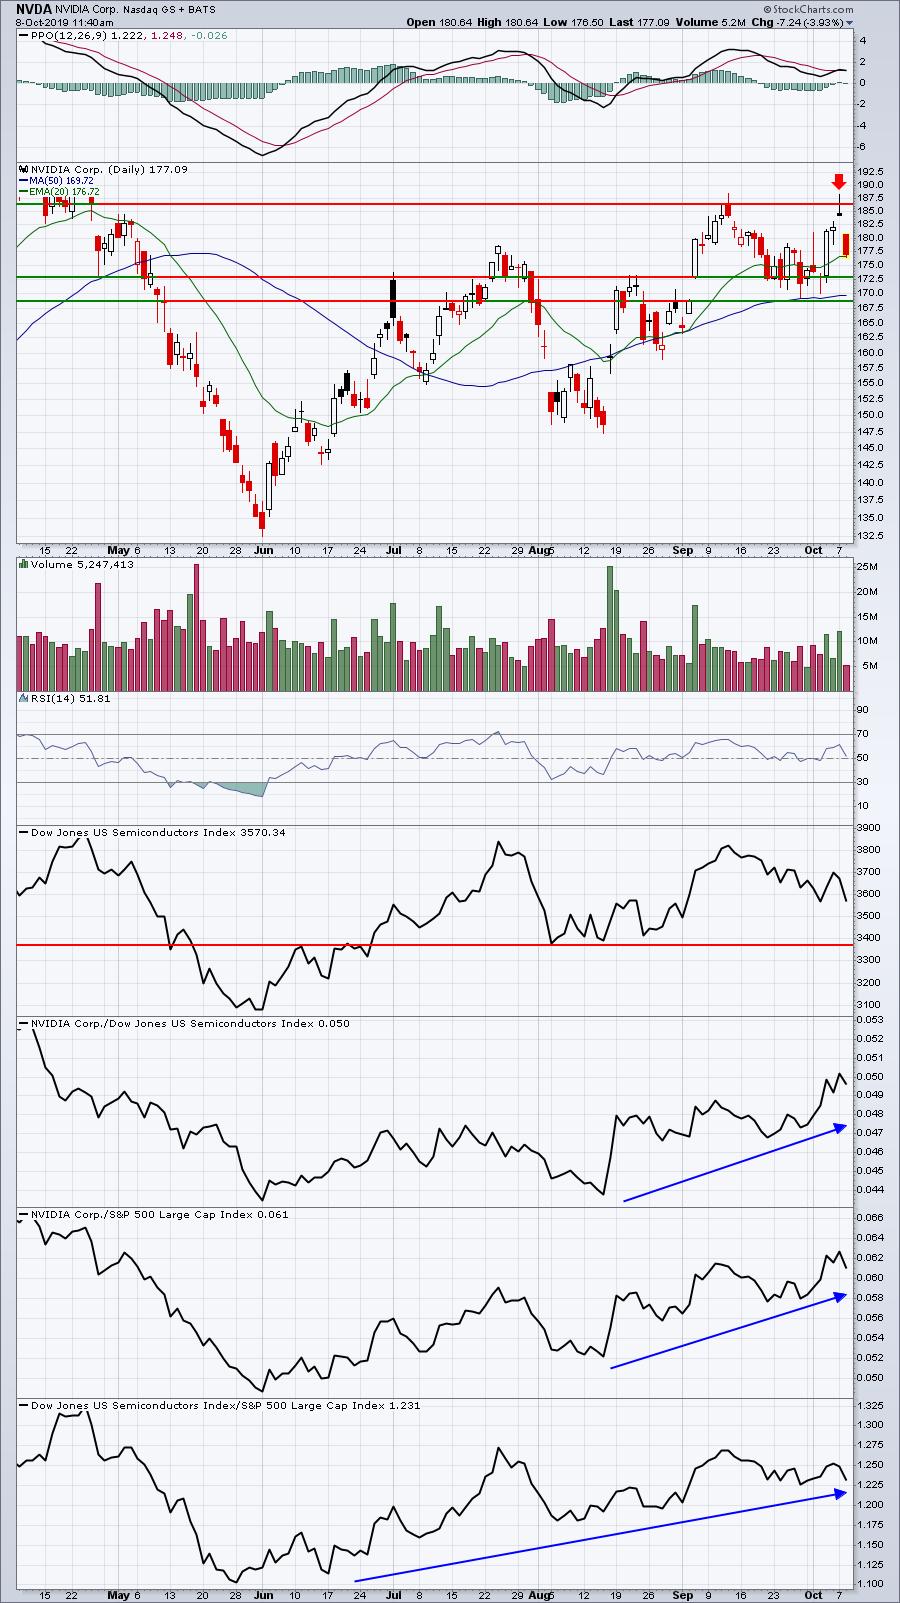
NVDA is beginning to show much better relative strength, but that failure on yesterday's breakout attempt is usually bearish short-term and that's certainly been the case today. I'd look for buyers to be waiting in the 169-173 zone.
ILMN:
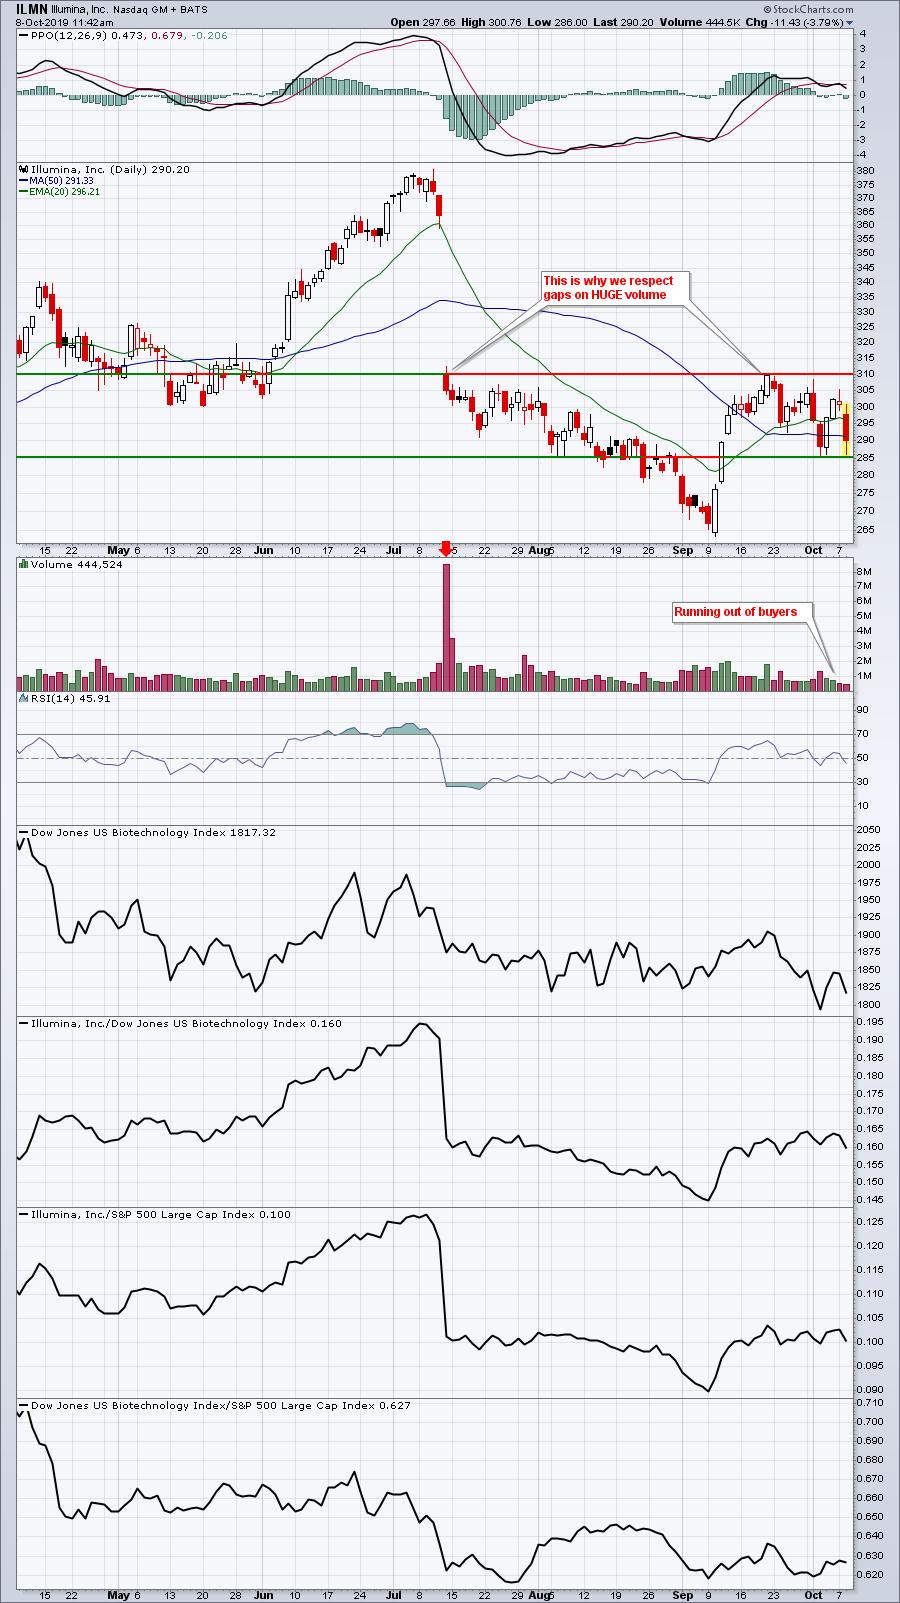
I wanted to first point out how important it is to keep prior gaps in view when evaluating the technical outlook of a stock or index. ILMN recently moved up and looked much better technically in mid-September, right? The PPO was positive and price action moved above key moving averages. We even saw a golden cross with the 20 day EMA moving above the 50 day SMA. Then it hit the gap resistance WALL and reversed lower. ILMN is part of the weak biotech group, so we want to be extra careful with any stocks in that space. ILMN remains an AVOID in my view for now. A move below 285 and selling will likely accelerate to test the 265 low.
Earnings Reports
Here are the key earnings reports for this week:
Tuesday, October 8:
DPZ, LEVI, HELE, AZZ
Wednesday, October 9:
None
Thursday, October 10:
DAL
Friday, October 11:
C, FAST
Economic Reports
September PPI: -0.3% (actual) vs. +0.1% (estimate)
September Core PPI: -0.3% (actual) vs. +0.2% (estimate)
Happy trading!
Tom