
EB Daily Market Report - Thursday, October 24, 2019
Executive Market Summary
- Earnings continue to pour in; Microsoft (MSFT) posts excellent results, Tesla (TSLA) shocks Wall Street with a huge earnings beat, while Twitter's (TWTR) report provides a "trick" rather than a "tweet"
- Economic news was mostly strong, but the 10 year treasury yield ($TNX) is lower by 2 basis points to 1.74%
- Technology (XLK) is easily the best performing sector, while communication services (XLC) underperforms
- Our major indices are bifurcated, however, with the NASDAQ leading
- Transports ($TRAN) struggling as overhead price resistance at 10800 approaches
- Our two Active Trade Alerts are both lower on the session
Market Outlook
I have long contended that what's going on in China really doesn't have a lot of bearing on U.S. stocks. From a common sense perspective, that might be hard to grasp as China's economy is HUGE and many large U.S. companies do a very high percentage of business there. But in reality, U.S. stocks tend to perform much more in line with German stocks ($DAX) as correlation will show:
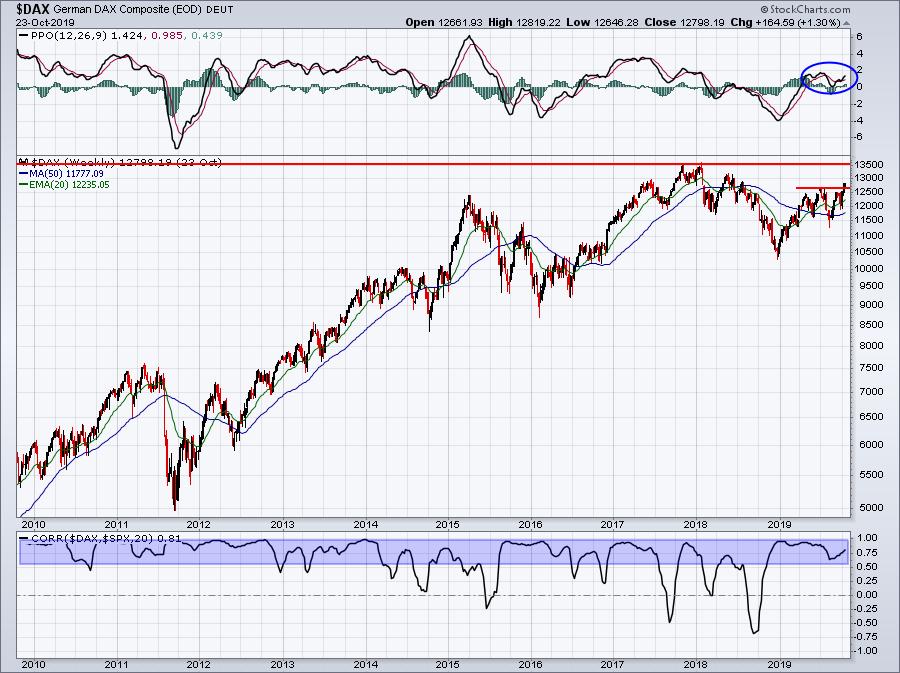
The DAX has broken out to a multi-month high and the correlation between the DAX and the S&P 500 is generally positive (blue-shaded area above). Any reading above 0 means there's positive correlation and nearly all of the weekly correlation readings between these two indices have been above 0.50 throughout the bull market. How can we construe the breakout to multi-month highs in Germany as anything other than bullish for U.S. stocks?
Sector/Industry Focus
Semiconductors ($DJUSSC) got rocked yesterday with Texas Instruments (TXN) gapping lower with its quarterly results, despite a very strong report from Teradyne (TER). Today, the group is surging higher to essentially wipe out the losses experienced on Wednesday:
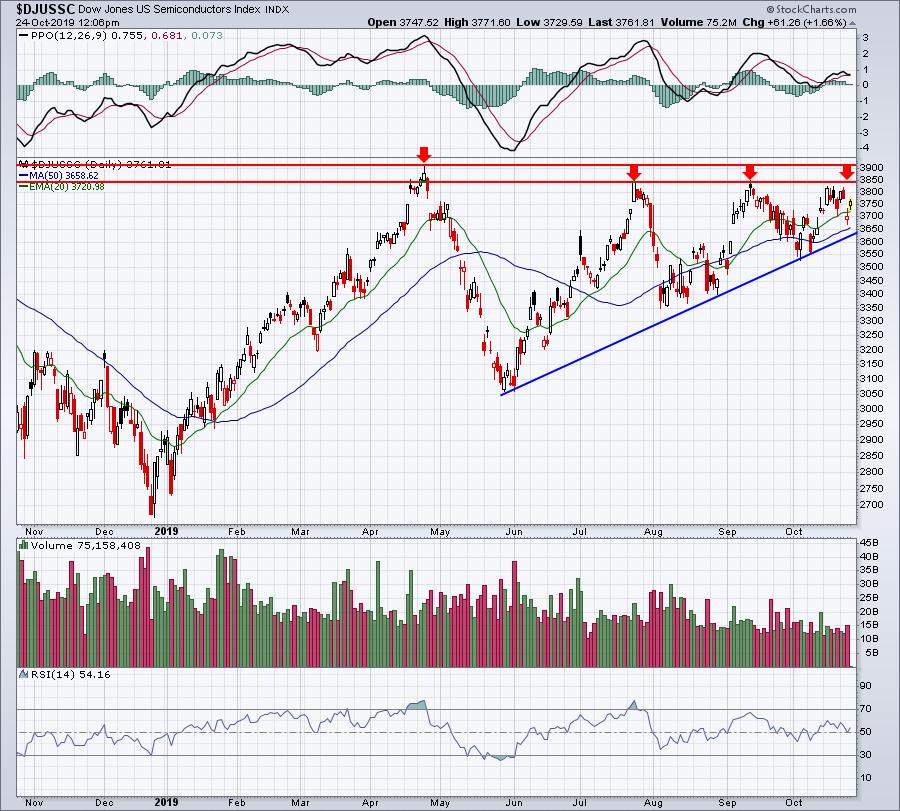
There remains key overhead price resistance, but it's very important to keep a close eye on this group. Major S&P 500 advances typically coincide with a strengthening semiconductor group. A breakout above 3900 should be viewed very bullishly not only for this industry, but also for the benchmark S&P 500.
Strong Earnings ChartList (SECL)
Here are the SECL stocks setting new 52 week highs today (as of 11:50am EST):
AIZ, AMAT, BAC, CTAS, JPM, KEYS, O, PDD, RH, SEDG, SNX, VIPS.
I'd be careful with the attempted breakout on AIZ, but most of the others look quite strong.
AIZ:
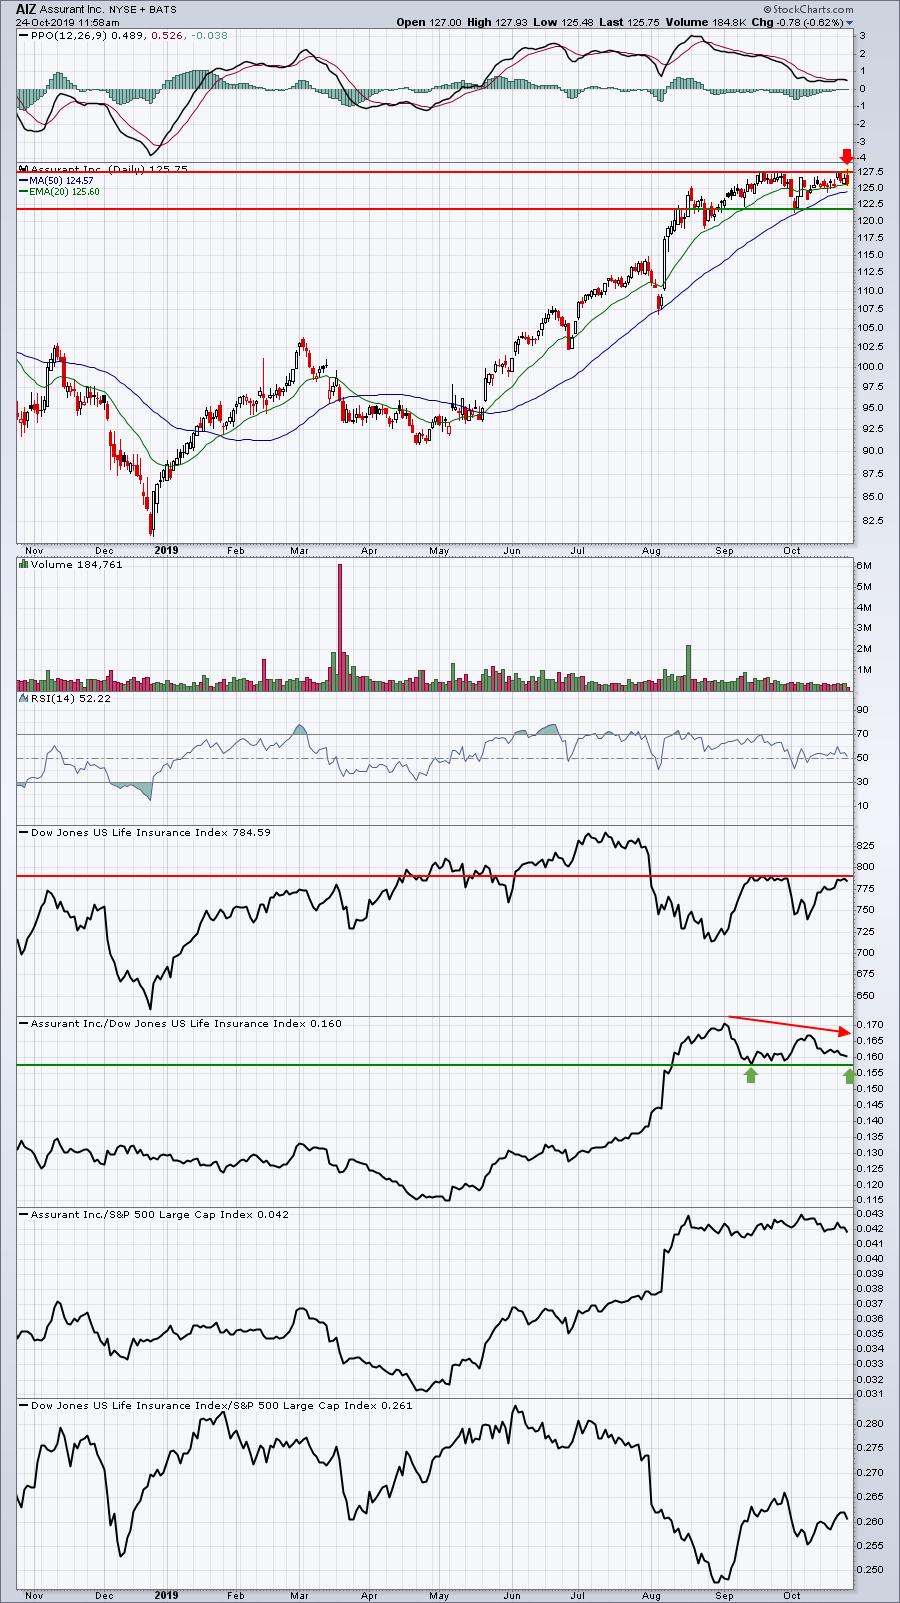
I like AIZ further down the road, but there are enough warning signs here to make me cautious near-term. Today's breakout attempt has, thus far, failed and it's on light volume. Also, AIZ has been downtrending relative to its life insurance peers ($DJUSIL).
AMAT:
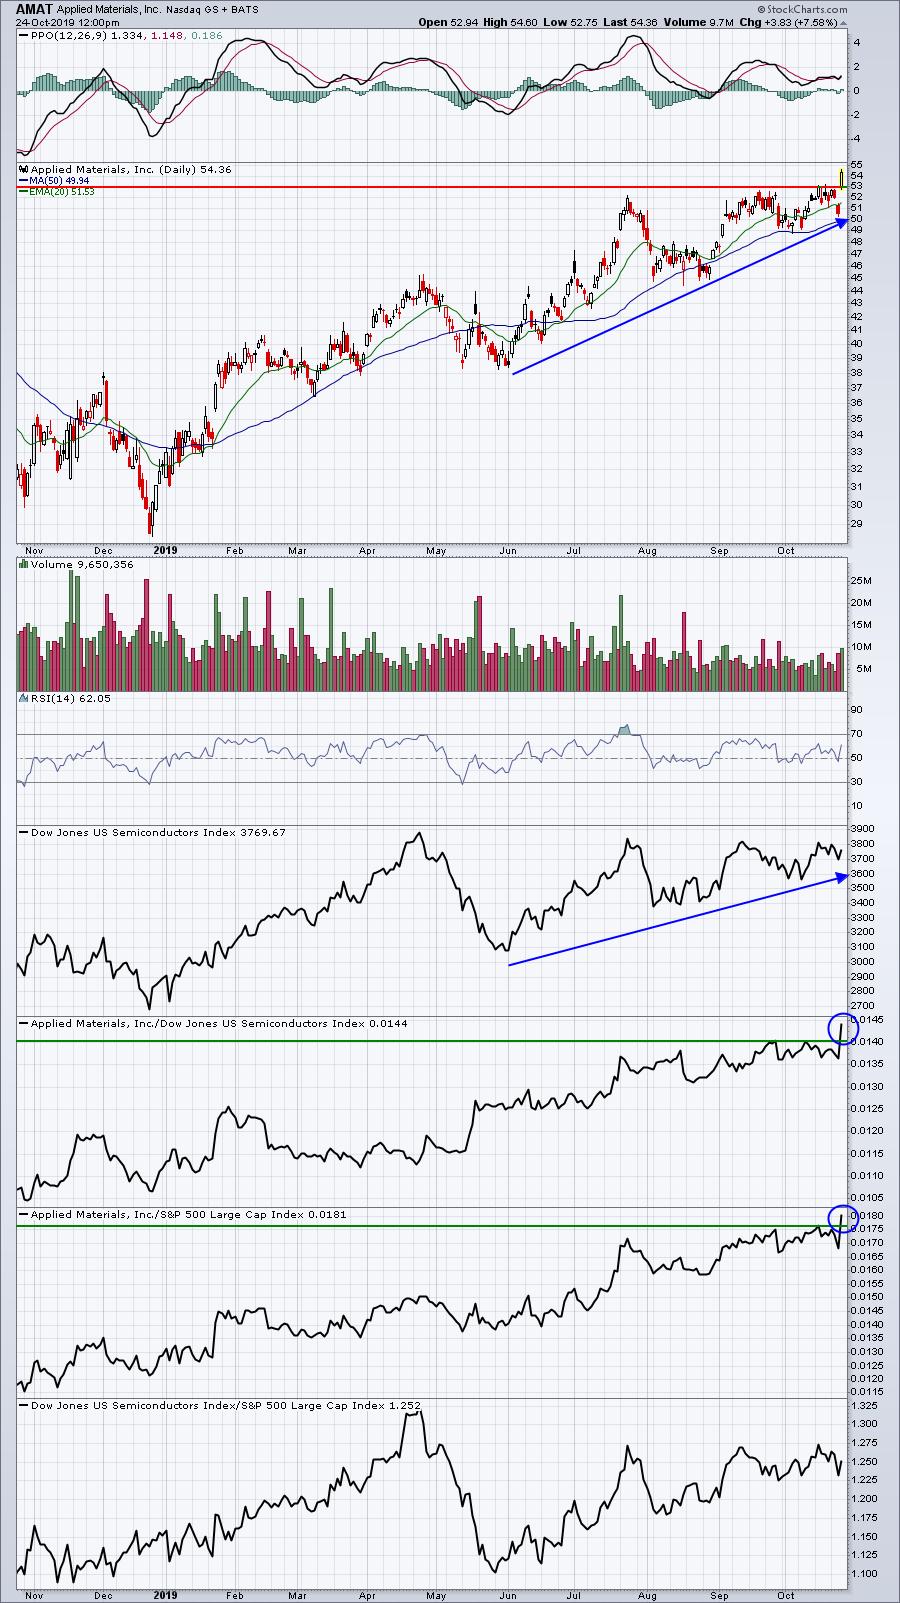
A competitor of AMAT's, Lam Research (LRCX), blew out its EPS estimates and is soaring today. AMAT is breaking out in sympathy and doing so on excellent volume. I believe AMAT will be a solid trade into its earnings report in mid-November.
CTAS:
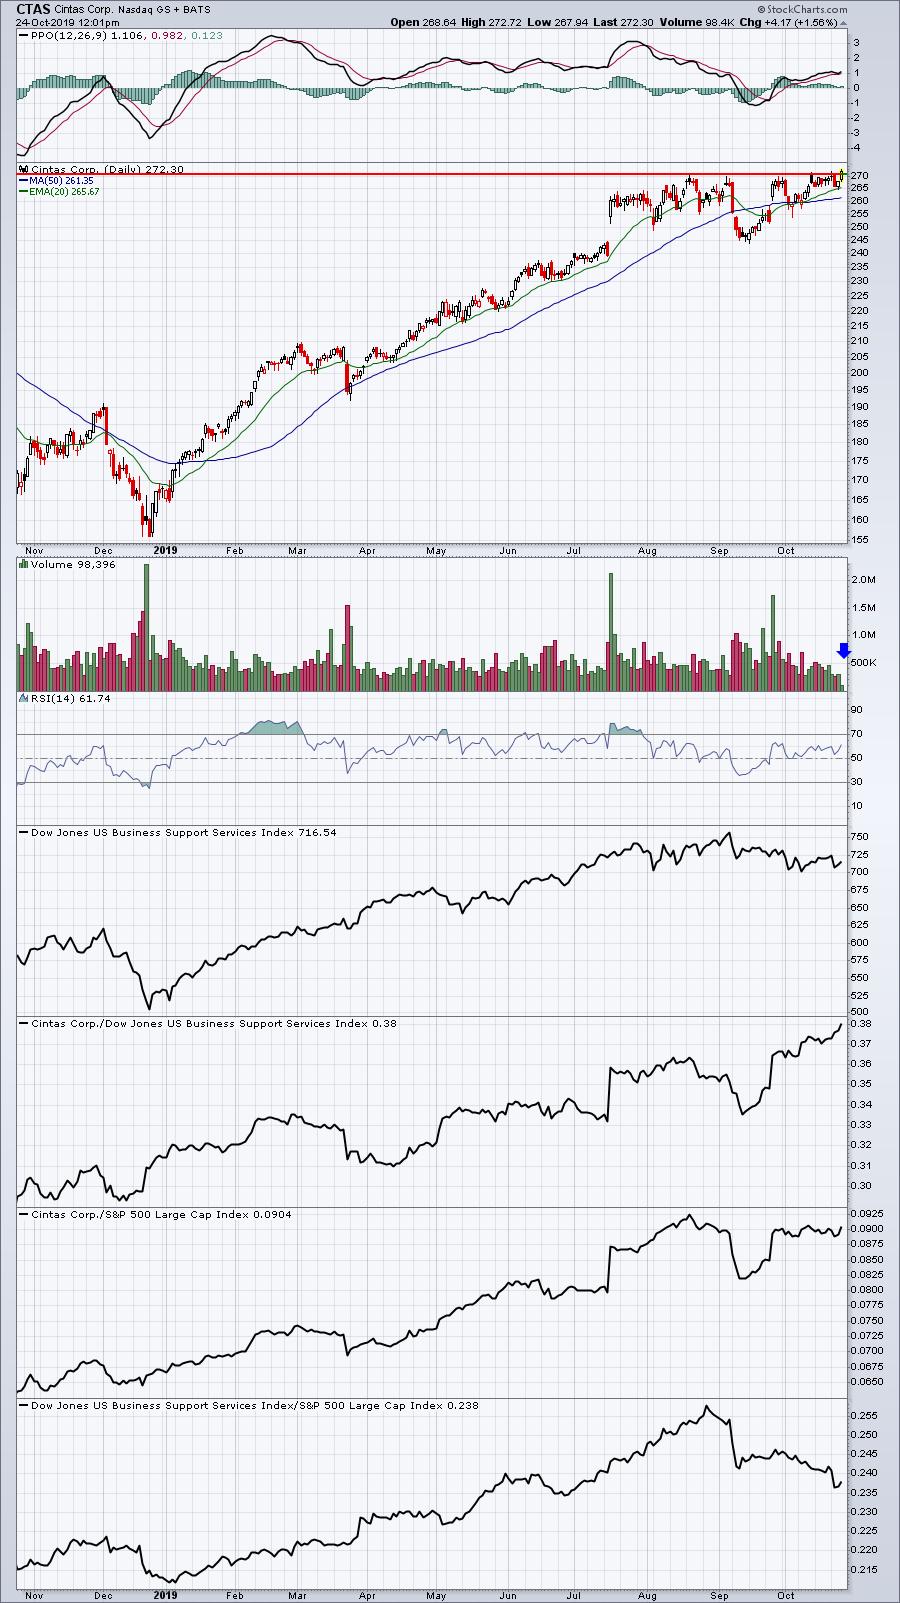
I was bullish CTAS in yesterday's DMR as I noted it was testing its 20 day EMA. It's bounced solidly off that moving average, but today's breakout attempt is on rather light volume so far. If CTAS fails to close above 270, we could see a bit more consolidation near-term. I believe CTAS is headed higher, but today's close might dictate whether that strength is likely to occur now or perhaps a few days to a few weeks down the road.
Active Trade Alerts
We have significantly lowered our trading exposure given the historical bearishness this week (The S&P 500 has a -43% annualized return from October 21st close to October 27th close since 1950). We added one alert yesterday (NKE) and may add more this afternoon or tomorrow. Here's a brief update of our current Active Trade Alerts:
ZUMZ (-3.43%) - earnings date is December 5th. ZUMZ is selling off today on light to moderate volume. Prior resistance (now closing support) was 33.04. So a recovery this afternoon and close back above 33.04 would be best technically in the short-term. Failure there could lead to a rising 20 day EMA test, currently at 31.82.
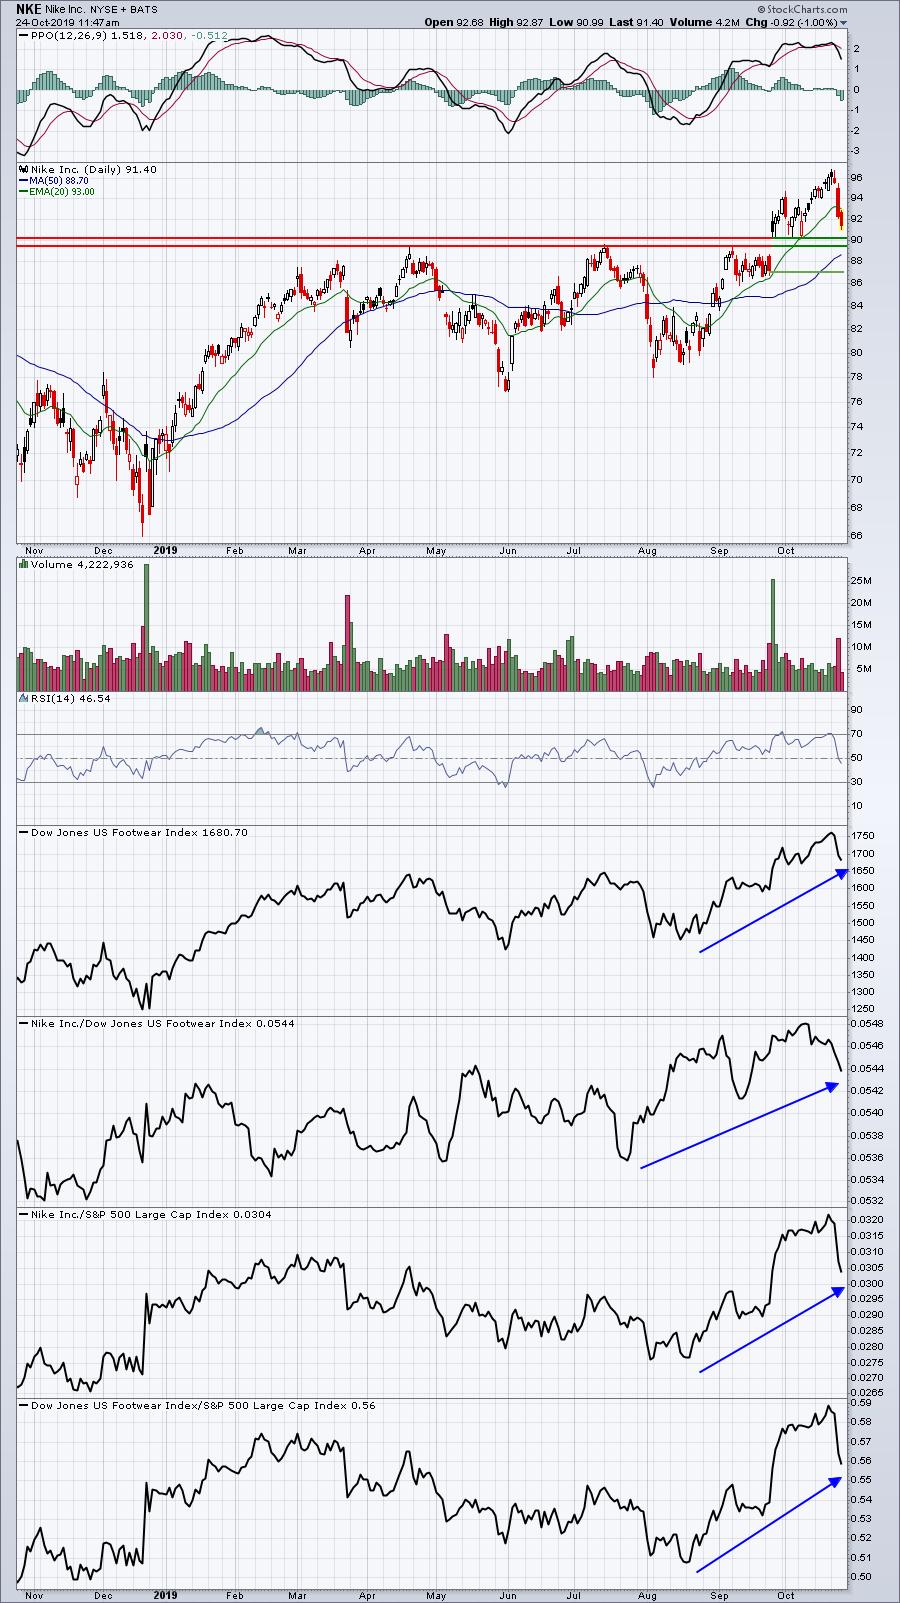
NKE (-1.00%) - recently reported earnings so the next earnings date won't be for another couple months. Footwear ($DJUSFT) is a strong industry group, so we're using weakness to accumulate here. Our first entry yesterday was near the 20 day EMA and our second entry is at 90.50 - close to recent price support. As long as we hold onto gap support from earnings, which is at 87.18, we'll be ok with the short-term selling. Our closing stop is 87.
Today's Movers
Earnings can be "character changers" on the charts. Here are a couple of earnings reactions today worth noting:
LRCX:
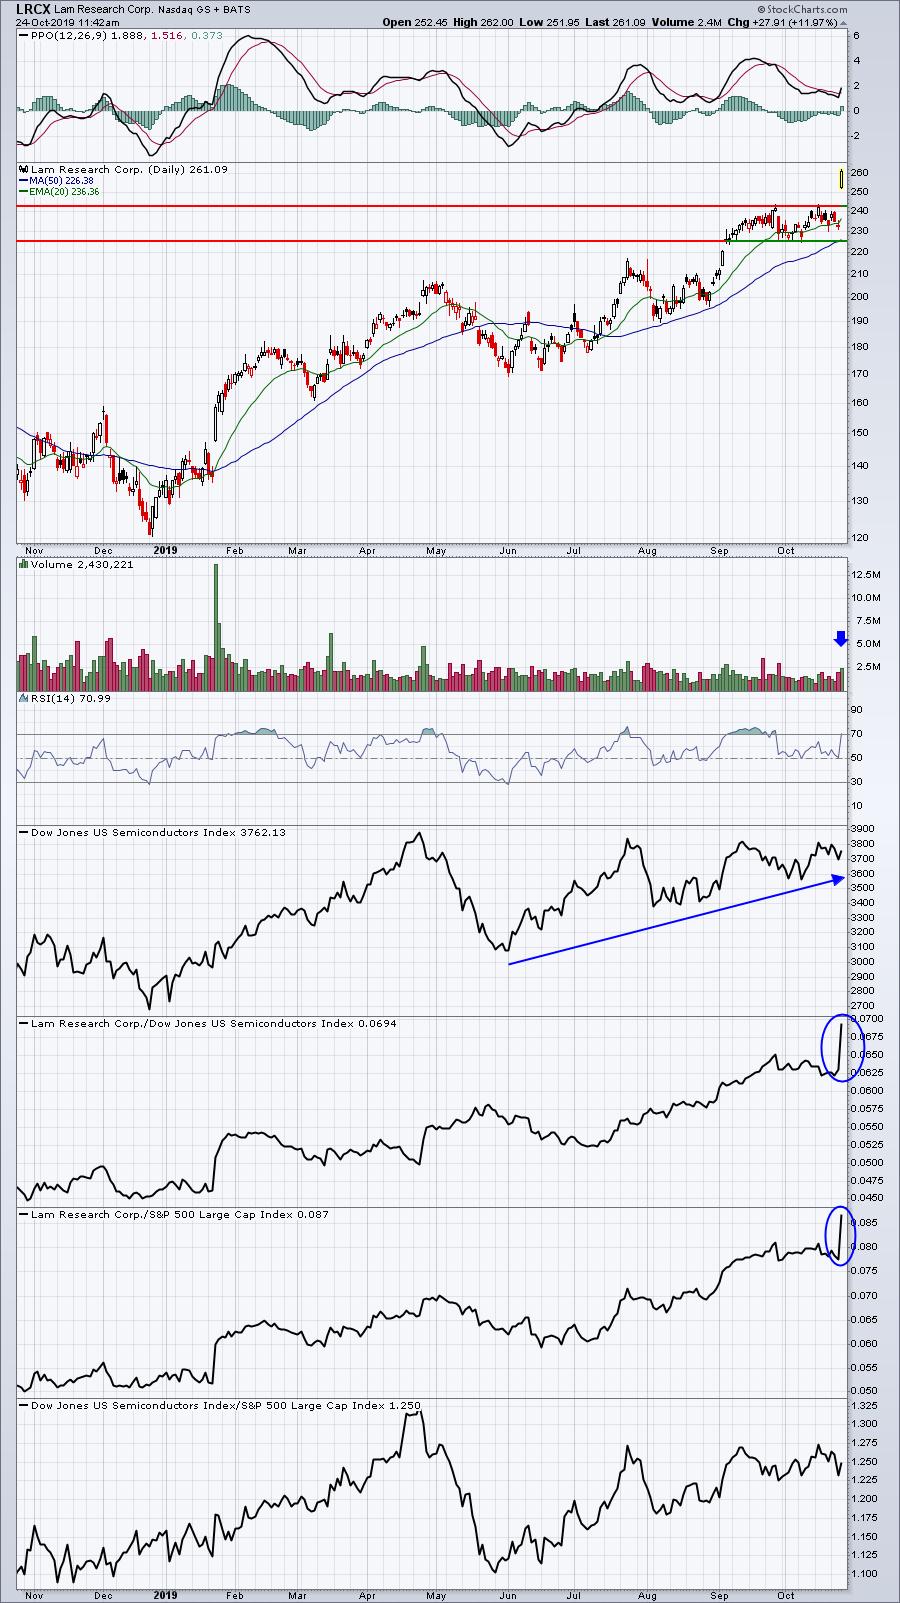
This is simply a continuation of an already very strong chart. LRCX has been a leader in the semis and, based on this report, I don't see it changing any time soon. This bodes very well for other semi equipment manufacturers like KLA Corp (KLAC) and Applied Materials (AMAT).
FFIV:
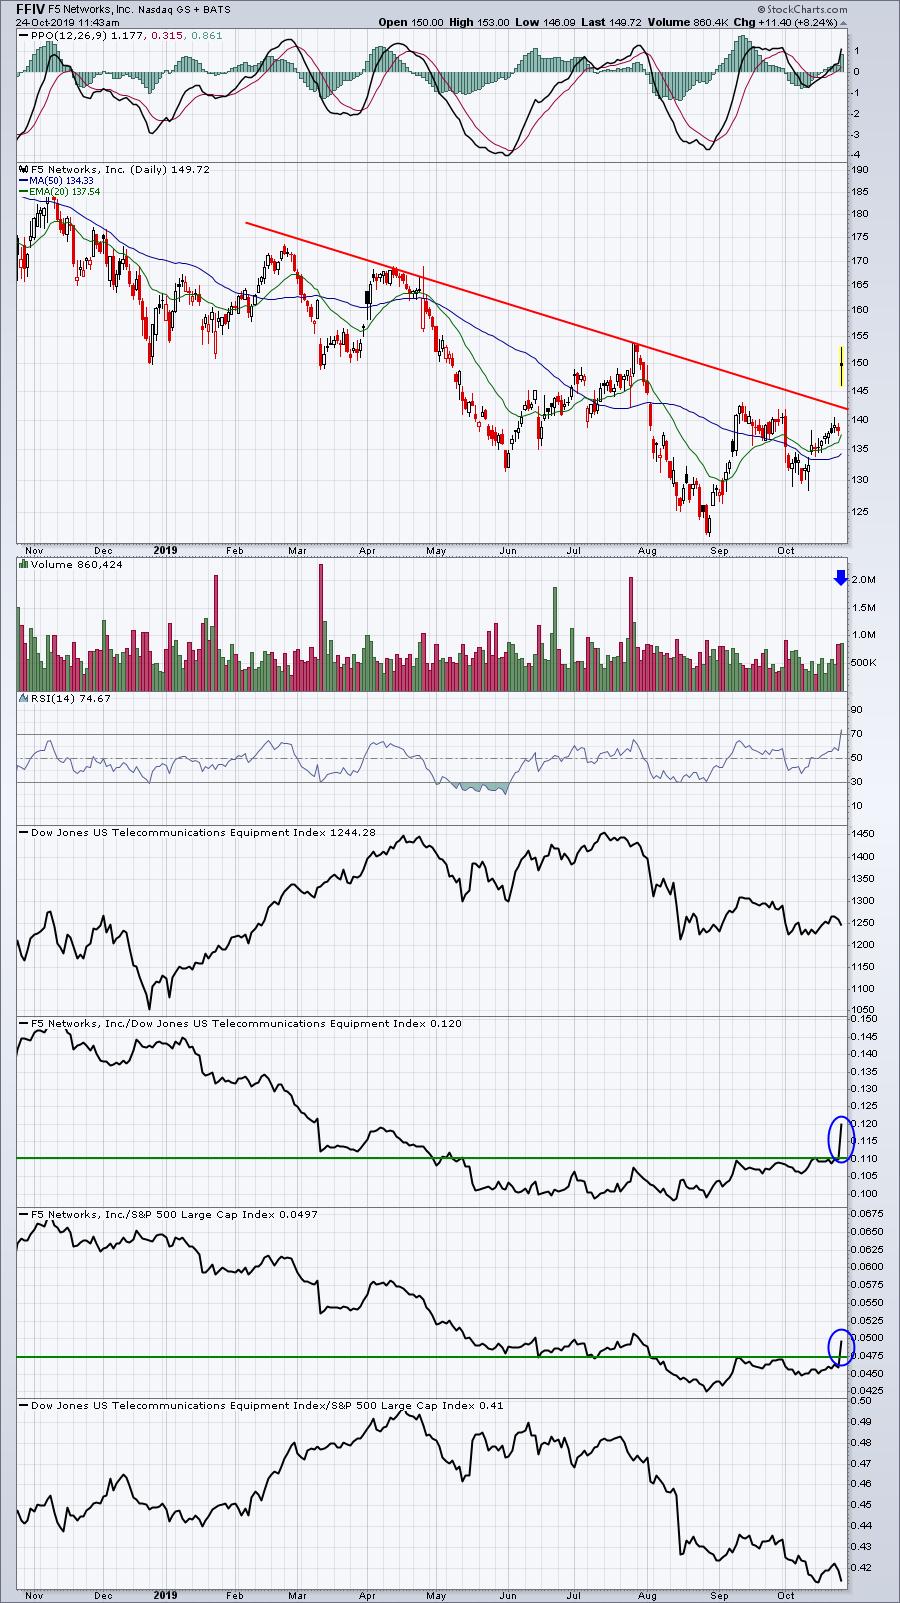
This is a very good example of a potential game changer. FFIV had been mired in a big slump and was one of the worst stocks in a very depressed group - telecommunications equipment ($DJUSCT). While the group may hold FFIV near-term, I expect we'll see much higher prices on FFIV later in Q4 and into 2020 based on the reaction to its earnings last night.
Earnings Reports
Here are the key earnings reports for the balance of this week, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that are reporting are highlighted in BOLD. The number of companies reporting will increase significantly over the next few weeks so please make sure you check for earnings dates for any companies you own or are considering owning:
Thursday, October 24:
AMZN, V, INTC, CMCSA, AZN, DHR, MMM, GILD, ABEV, NOC, RTN, AEP, ILMN, BAX, COF, AFL, VLO, RBS, DOW, ROP, XEL, HSY, TWTR, NOK, LUV, CAJ, CCEP, FE, TROW, FTV, RCL, SWK, TAL, VRSN, CERN, STM, RMD, CINF, CMS, LH, AJG, PFG, HBAN, ODFL, CTXS, UHS, COF, AAL, TSCO, SIVB, WST. Others below $10 bil: CY, JNPR, FSLR, DECK, ELY, EHTH, BOOT
Friday, October 25:
VZ, BUD, TOT, CHTR, ITW, PSX, AON, IBN, VFC, VTR, VIV, WY, BEN. Others below $10 bil: HUN
Economic Reports
Initial jobless claims: 212,000 (actual) vs. 214,000 (estimate)
September durable goods: -1.1% (actual) vs. -0.7% (estimate)
September durable goods ex-transports: -0.3% (actual) vs. -0.1% (estimate)
September PMI composite flash: 51.2 (actual) vs. 50.9 (estimate)
August new home sales: 701,000 (actual) vs. 698,000 (estimate)
Happy trading!
Tom