
EB Daily Market Report - Tuesday, October 29, 2019
Executive Market Summary
- Healthcare (XLV) is adding to recent gains and leading the S&P 500 higher; NASDAQ is lower, however, in bifurcated action today
- Merck (MRK) and Pfizer (PFE) both posted excellent quarterly results and reacting favorably
- Alphabet (GOOGL) disappoints on its earnings, but both the stock and the internet group ($DJUSNS) handling it fairly well - bullish behavior
- Pending home sales were very strong for September, helping to offset a weaker-than-expected October consumer confidence
- The 10 year treasury yield ($TNX) is relative flat, bouncing back after an earlier slow start
- Commodities are weak with gold (GLD) and crude oil ($WTIC) both lower
- Our two Active Trade Alerts are mixed today
Market Outlook
I know there are still plenty of gold bulls out there, but I don't like the yellow metal. It was ok for a short-term trade, which I've said during its 2019 strength. But the long-term is not conducive to outperformance in commodities, not while the U.S. Dollar Index ($USD) remains in an uptrend. The Fed is meeting today and tomorrow and could give commodities a lift if they surprise everyone with a 50 basis point rate cut, which is exactly what I believe they should do. Why should they lower 50 basis points when GDP is still positive? Well, two reasons. First, it's about inflation trending below the Fed's target level at 2%. Commodity prices have been suffering for 8 years because of a strong dollar. We could use a break in dollar strength quite honestly. It would help us to inflate our economy. While runaway inflation is a problem, a bigger problem is deflation. The Fed needs to act to ensure we don't head in that direction. A 25 basis point cut is good, a 50 basis point cut would be better. We'll know the result of their meeting at 2pm EST tomorrow afternoon. The second reason for a 50 basis point cut is that economic reports have suggested that things have softened a bit. Recently, we saw the ISM manufacturing number fall below 50. Last month's retail sales also were very weak. The lingering trade war has definitely had an impact, even though I believe it's just temporary. U.S. stocks will benefit from the eventual resolution, in my opinion.
Getting back to gold, check out this GLD chart:
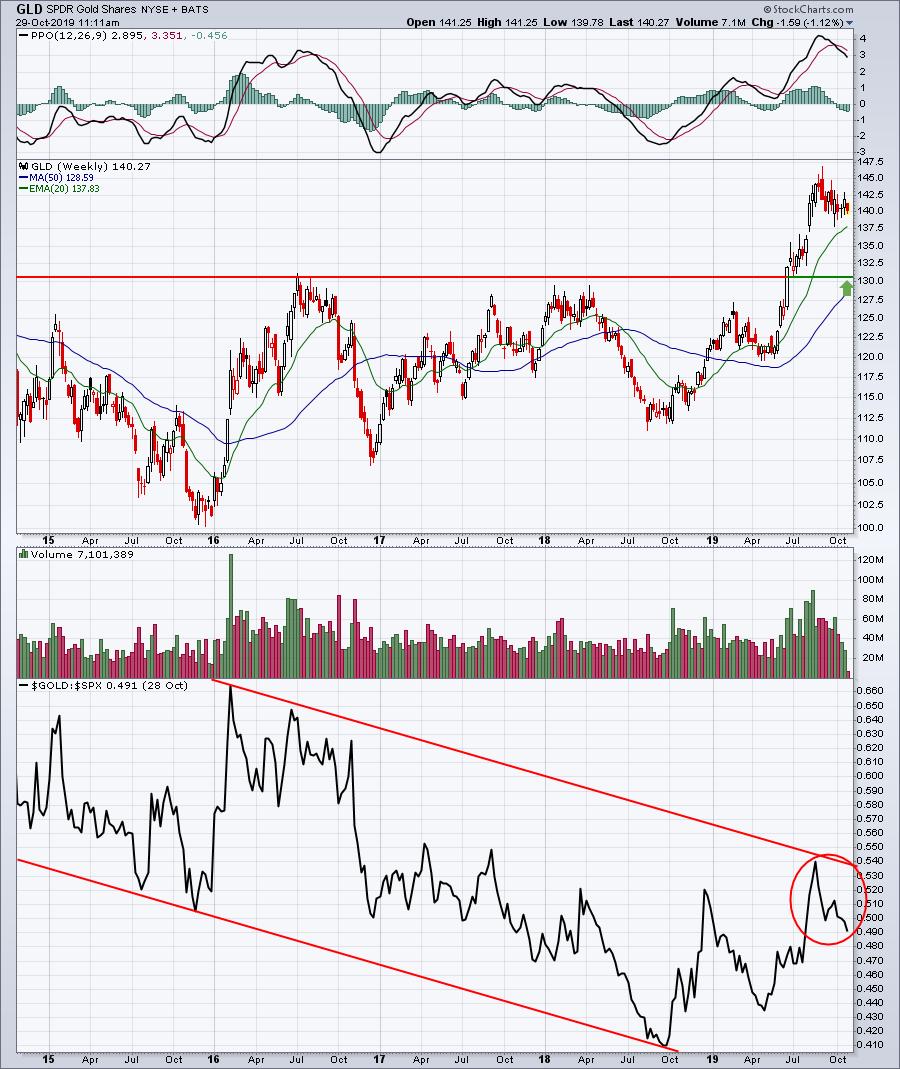
The absolute price chart for GLD doesn't really look bad, but that's not what worries me. I want to outperform the benchmark S&P 500. You can see from the bottom panel above, GLD doesn't have a very good history of doing this and it's rolled over and trending lower once again on a relative basis. I believe it's in a relative down channel. Until that breaks, I'd keep my money parked in stocks.
Sector/Industry Focus
Consumer staples (XLP) has been a weak sector of late, but it's once again testing the lower uptrend line in a channel. I'd expect to see a nice bounce from here:
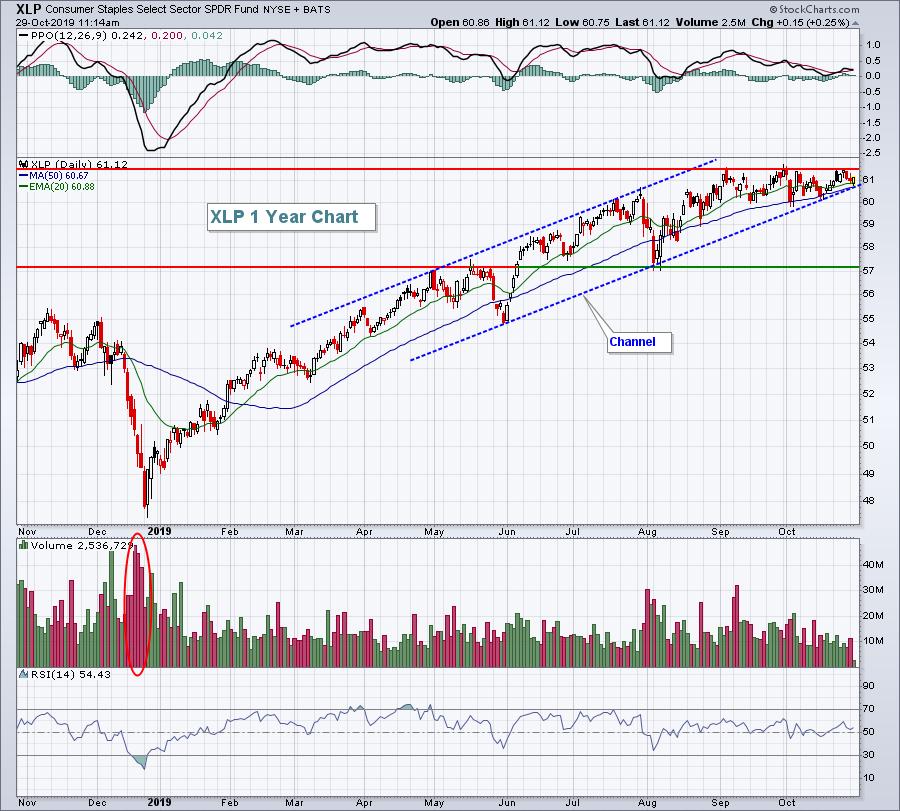
The XLP has traded above 61.50 on a few occasions, but it hasn't managed to close there. I believe a close above 61.50 would encourage more buyers in this sector. While I don't expect the XLP to be a leading sector over the next few months, I do expect it to participate and move higher.
Strong Earnings ChartList (SECL)
As of 11:00am EST, there were 11 SECL stocks that had already traded at least 35% of daily volume. They are on a pace to trade more than their normal average daily volume. Here are two that look interesting:
ELF:
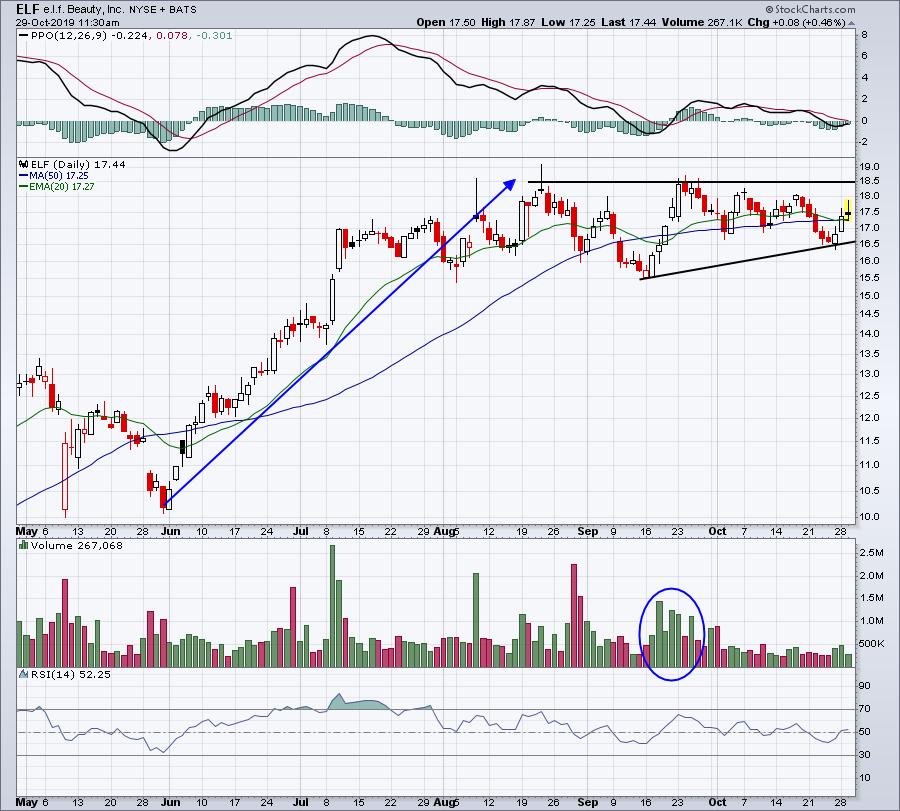
ELF is in a very nice ascending triangle continuation pattern so I'm expecting a breakout here. The last push higher to test overhead resistance came on expanding volume. The signs are there for accumulation. A breakout above 18.50 on increasing volume would confirm measurement to 21.50.
BDX:
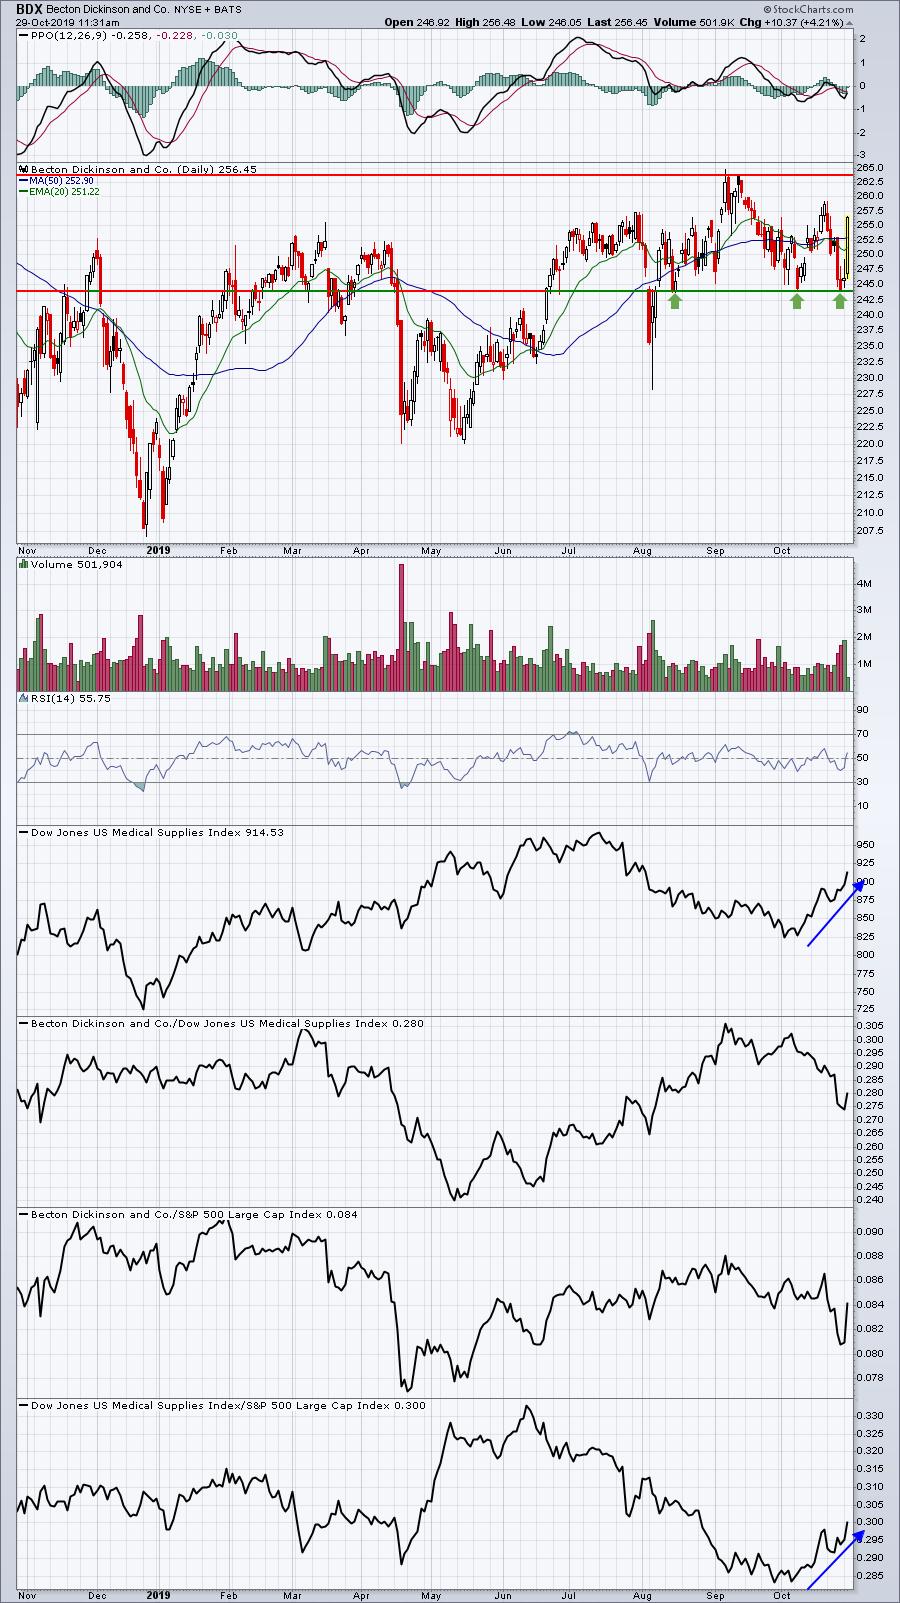
Medical supplies stocks ($DJUSMS), which had been quite dormant for the three months heading into October, are all of a sudden back on track. That's good news for stocks like BDX. BDX held up well during the DJUSMS selling. It's been lagging on the October strength. But of all of this is simply a part of consolidation. Today's increasing volume and 4.21% rise is very encouraging and could be a signal of an impending breakout. That would confirm on a close above 264.
Active Trade Alerts
We have entered a very bullish historical period for U.S. stocks. In fact, the S&P 500's close on January 18 has been higher than its close on October 27 in 56 of the past 68 years. Unless history is proven wrong, we're going to break out to new highs throughout Q4. We have two alerts out right now and will be looking to add more this week:
ZUMZ (+0.68%) - earnings date is December 5th. ZUMZ continues to trend just above its 20 day EMA. It's pulled back from earlier highs, but there's still distance between current price of 32.80 and the rising 20 day EMA, currently at 32.01.
NKE (-0.88%) - recently reported earnings so the next earnings date won't be for another couple months. NKE's weakness allowed us our second entry at 90.50 yesterday. The short-term downtrend remains in play with NKE's move lower today. After gapping higher with earnings on September 25th, NKE printed an intraday low of 90.15. Today's move lower takes out that support area and could be an accumulation area. It would be very bullish to see an afternoon reversal off of this fresh post-earnings low. Failure to bounce, however, would likely mean a 50 day SMA test, currently at 89.34.
Today's Movers
I wanted to share a biotech stock ($DJUSBT) that you should be aware of in the event that biotechs continue to strengthen. Syneos Health (SYNH) is not really a mover today as it's flat on the session, but it has reversed intraday off earlier weakness in what could be a very bullish pattern:
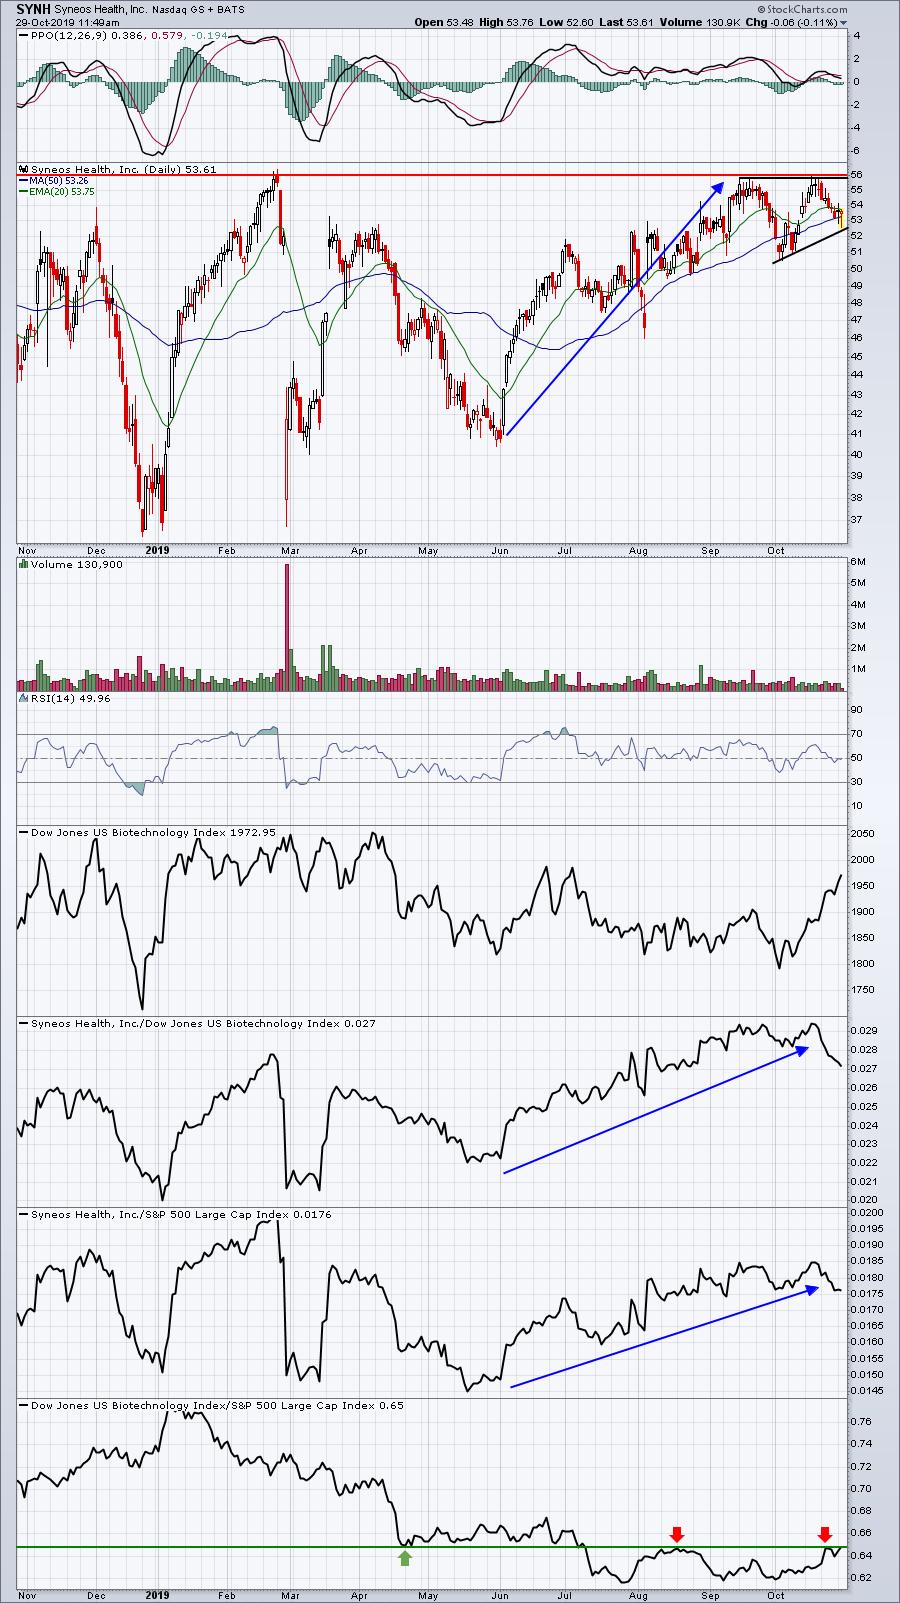
A word of caution: Biotechs can be extremely volatile, especially individual stocks. So if you have a very low risk tolerance, this type of stock should be avoided. However, if you enjoy taking risks looking for a potential grand slam, SYNH deserves attention. Also, SYNH reports earnings on Thursday, October 31st.
Earnings Reports
Here are the key earnings reports for this week, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that are reporting are highlighted in BOLD. The number of companies reporting will be significant over the next two weeks, so please make sure you check for earnings dates for any companies you own or are considering owning:
Tuesday, October 29:
MA, MRK, PFE, BP, AMGN, PTR, SYK, MDLZ, CB, COP, SPGI, ECL, GM, MMC, HCA, PSA, SHOP, EC, ALL, ETN, AMD, OKE, IR, EA, DLR, CMI, EIX, VRSK, GLW, K, BXP, FMS, ACGL, INCY, INVH, MLM, YUMC, SGEN, AGR, MXIM, MKL, KKR, EXR, UDR, WAT, CXO, FNF, IEX, PAYC, CHRW, EXAS, LDOS, ZBRA, FMC. Others below $10 bil: ZEN, AN, MRCY, ENPH, LSCC, DENN
Wednesday, October 30:
AAPL, FB, GSK, SBUX, GE, SNE, CME, ADP, SO, VRTX, SPG, SU, EQIX, LHX, MET, MCO, CTSH, YUM, TEL, IQV, WMB, RSG, MSI, MCK, KLAC, S, ETR, BKR, RCL, APTV, AWK, HES, HCP, WDC, GRMN, MAA, MGM, TWLO, WCG, NLY, BSAC, LYFT, MAS, TAP, DRE, LNC, TS, REG, MLCO, CLR, NI, FRT, TYL. Others below $10 bil: OLED, ETSY, CREE, CRUS, TMHC, EVTC, CROX, ELY, HTLD, BOOT, DDD
Thursday, October 31:
RDS.A, SNY, AMT, BMY, MO, CELG, EL, CI, ICE, DD, EXC, MPC, BCE, KHC, TRI, PEG, SIRI, MPLX, MELI, FCAU, GPN, WLTW, PH, BLL, IDXX, ADM, AME, CTVA, CLX, MSCI, CHD, ANET, CDW, IP, TFX, XYL, LYV, MMP, PINS, FTNT, WAB, IT, SSNC, CPT, VICI, CVE, OTEX, W, WU, BIO. Others below $10 bil: DNKN, AYX, GNRC, SRCL, JCOM, YETI, X, FLWS, FNKO
Friday, November 1:
BRK.B, BABA, XOM, CVX, ABBV, HDB, D, CL, TRP, AIG, SRE, LYB, IMO, PBA, FTS, LNG, WPC, STX, CBOE. Others below $10 bil: FND, TDS
Economic Reports
August Case-Shiller HPI: -0.2% (actual) vs. -0.1% (estimate)
October consumer confidence: 125.9 (actual) vs. 128.8 (estimate)
September pending home sales: +1.5% (actual) vs. +0.7% (estimate)
Happy trading!
Tom