
EB Daily Market Report - Thursday, October 31, 2019
Executive Market Summary
- The Federal Reserve cut the fed funds rate by 25 basis points yesterday
- Utilities (XLU) is the only sector in positive territory; industrials (XLI) and materials (XLB) are lagging
- Apple (AAPL) and Facebook (FB) both delivered solid quarters, but that has failed to lift our major indices
- Initial jobless claims were weaker than expected this morning
- Defensive treasuries are gaining with the 10 year treasury yield ($TNX) dropping 9 basis points to 1.71%
- Our three Active Trade Alerts are down, though NKE is the only one down more than 1% as it struggles to hang onto 50 day SMA support
Market Outlook
Well, the Fed has come and gone. There were no huge surprises, which is great if you're bullish like me. They cut the fed funds rate by 25 basis points and that was widely expected. My pipe dream was for a 50 basis point cut, but I'm not shocked I didn't get that. The Fed has clearly turned much more accommodative throughout 2019 and indicated that they stood ready to cut rates again, but only if data supported it. Three cuts might do the trick. I believe our economy will be fine in time, I'm much more concerned about disinflation or, worse yet, deflation. I hope our Fed is smart enough to recognize that as the bigger issue.
Disinflation is the slowing of inflation and is considered temporary. If you recall back in the Spring, Fed Chief Powell talked about lower inflation being "transitory". He was referring to "disinflation". Deflation is when there's an outright drop in prices for goods and services. Normally, deflationary fears occur when there's economic uncertainty and unemployment is high. The unemployment level being high is important because that aids the lack of demand for goods and services. If everyone is working, there's generally solid demand. Still, the worst environment for equities is one in which deflation becomes problematic. That's why I wanted a 50 basis point cut to weaken the U.S. Dollar ($USD) and inflate commodity prices. Here's a chart that shows this relationship quite clearly:
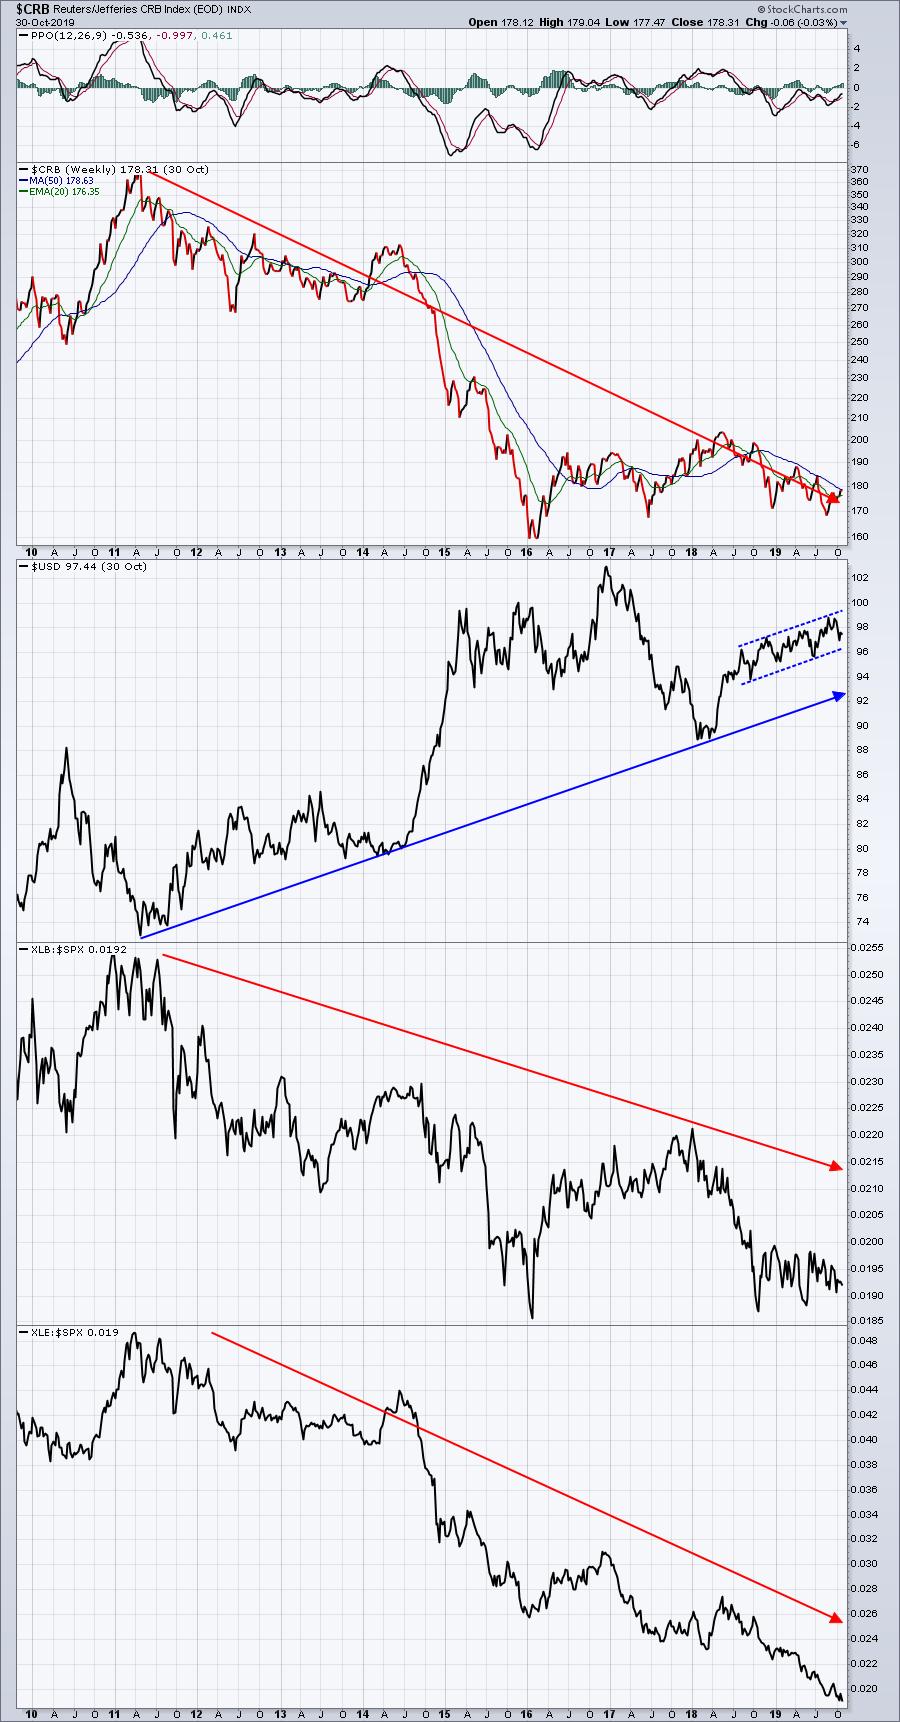
The top panel is the CRB Index ($CRB) and it shows that commodities have been under pressure for 8 years, exactly when the uptrend in the U.S. Dollar Index began. The primary impact with a strong dollar is that both materials (XLB) and energy (XLE) face stiff headwinds and tend to underperform during such periods. That's quite evident from the bottom two panels. Until the Fed decides that weakening the dollar becomes an important short-term objective, we need to follow the charts and they currently suggest to mostly avoid materials and energy - especially on a relative basis.
Sector/Industry Focus
Semiconductors ($DJUSSC) cleared 3900 earlier this week and has seen some profit taking the past few sessions. KLA Corp (KLAC) reported excellent quarterly results, but is trading lower today in a sign that perhaps the group needs a breather. Still, there are other semiconductors that have performed extremely well after reporting their results. Two examples today are Cirrus Logic (CRUS) and Ultra Clean Holdings (UCTT) which, as of 11:15am EST, were higher by 16.95% and 12.87%, respectively, after posting blowout numbers.
The DJUSSC remains one of the best areas of the market to own/trade:
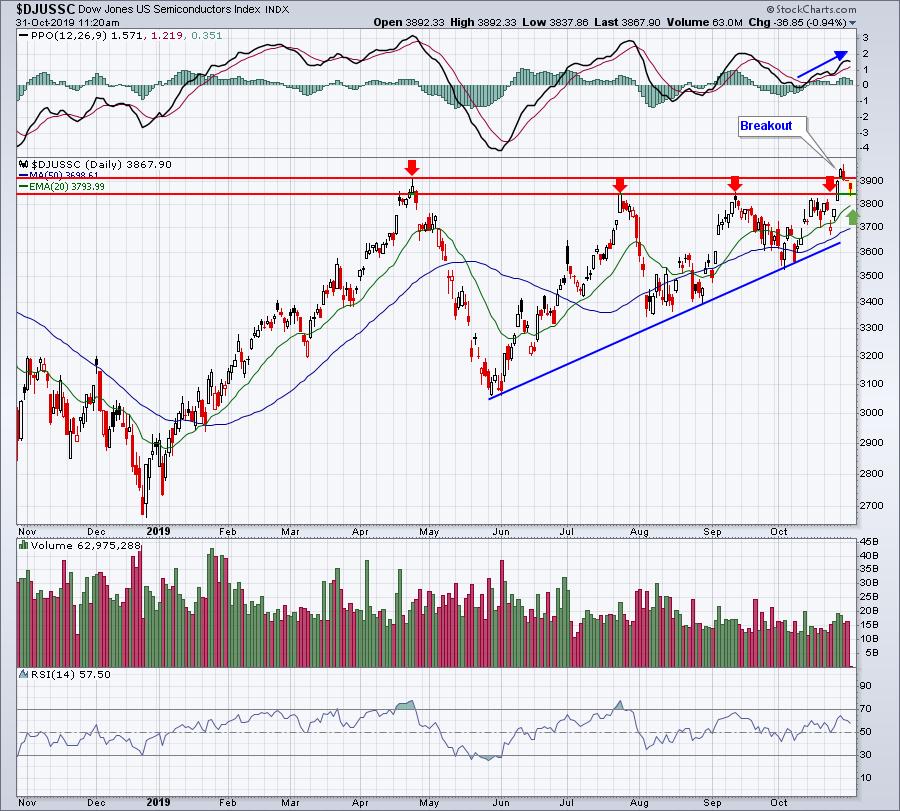
This was a chart provided in a DMR a week or so ago, I simply added the breakout and the green arrow showing that the 20 day EMA should be watched for short-term support given the strong PPO (blue directional arrow).
Strong Earnings ChartList (SECL)
I ran a scan of our SECL, looking for stocks that opened today above their respective 20 day EMAs, but are currently beneath that key short-term moving average. The idea here is to possibly uncover companies poised to recover off of a successful 20 day EMA test. There were 17 candidates listed in SCTR order:
KLAC, APPS, RH, ARMK, OMI, GMS, LCI, ELF, KEYS, ELY, LEN, ROST, FNB, PEP, BBT, PAYX, GDS
There are several that look enticing, but these two really stood out to me:
KEYS:
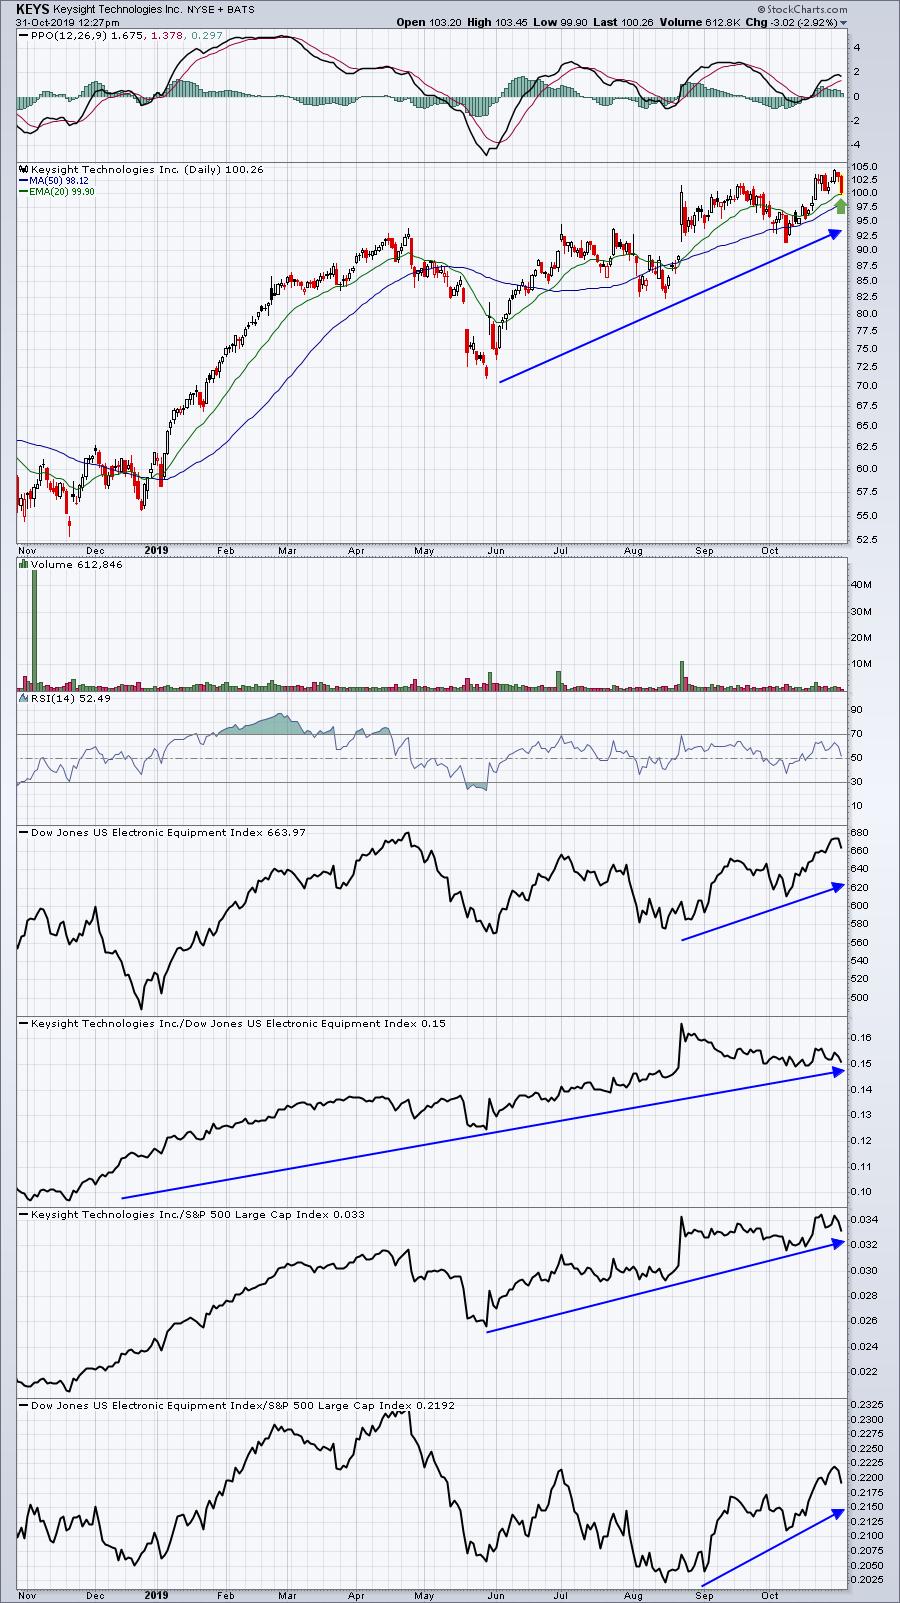
KEYS has been a very strong stock in recent months and today's weakness could be providing a solid reward to risk trading opportunity. Failure to close above its 20 day EMA could result in further selling so a tight stop could be used here.
ELY:
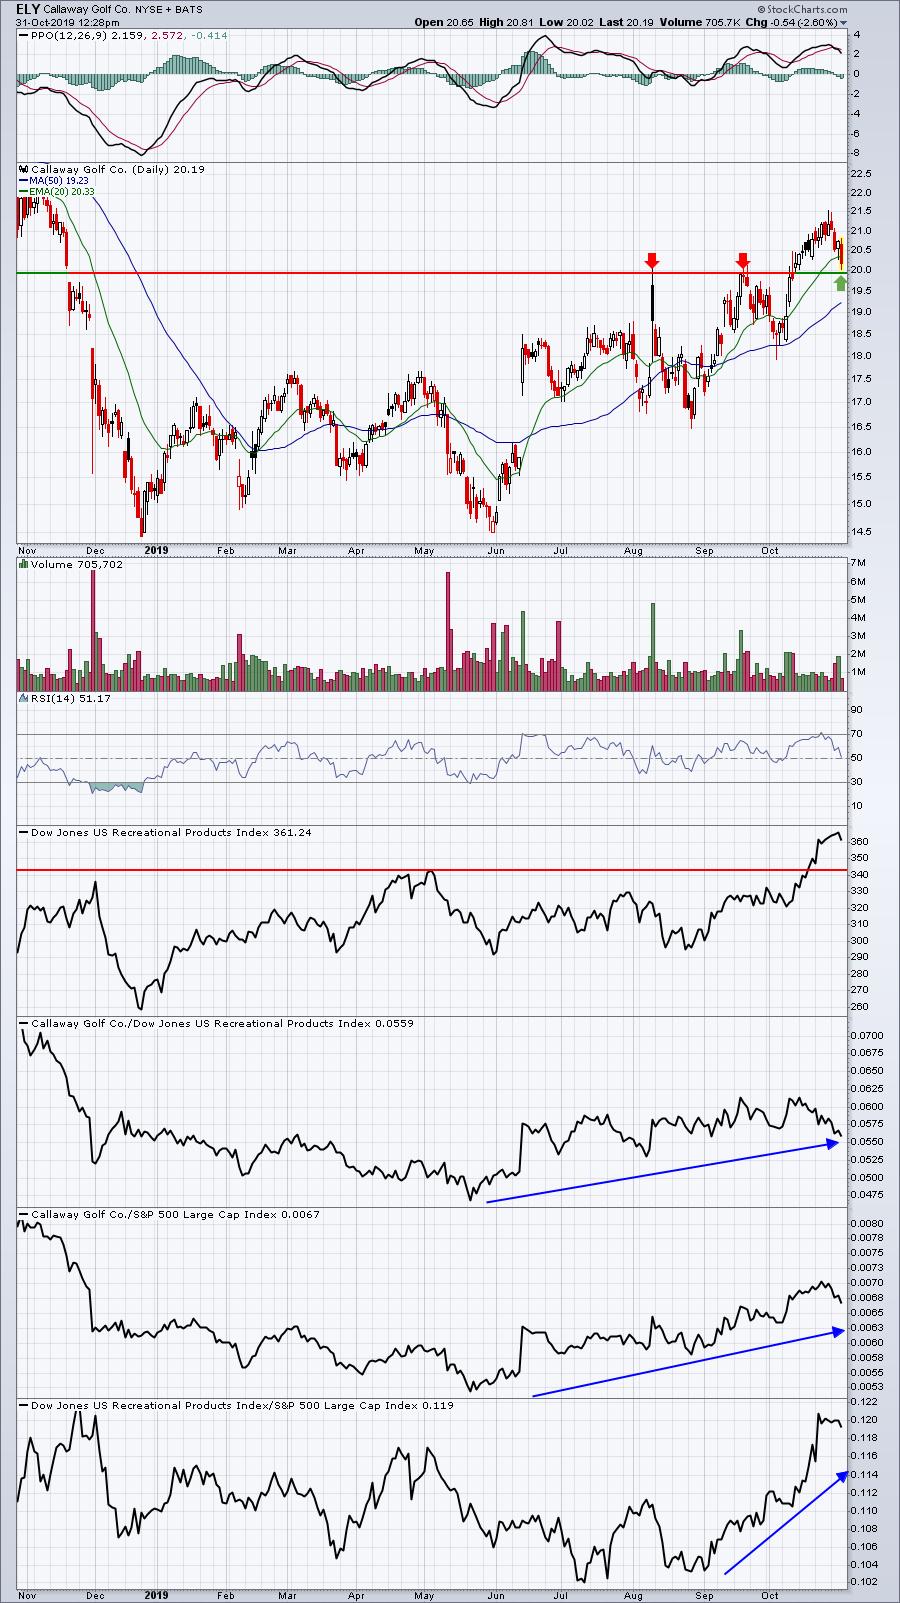
After ELY's double top near 20, it broke through in October. Selling this week has carried the stock back toward that 20.00 support area. Volume trends are solid and ELY resides in the recreational products group ($DJUSRP), which has been one of the most solid industry groups over the past month.
Active Trade Alerts
Here are our three current active alerts after issuing an alert on ROST:
ZUMZ (-0.22%) - earnings date is December 5th. ZUMZ is printing lower highs and lower lows for third consecutive day, so our first objective will be to reverse that.
NKE (-1.15%) - recently reported earnings so the next earnings date won't be for another couple months. Hovering near its 50 day SMA and recent lows.
ROST (-0.62%) - earnings date is November 22nd. Opened slightly higher, now trading lower with its industry peers. A close back above the 20 day EMA, currently at 110.18, would be a good first step today.
Today's Movers
Two heavy volume stocks caught my attention this morning:
KHC:
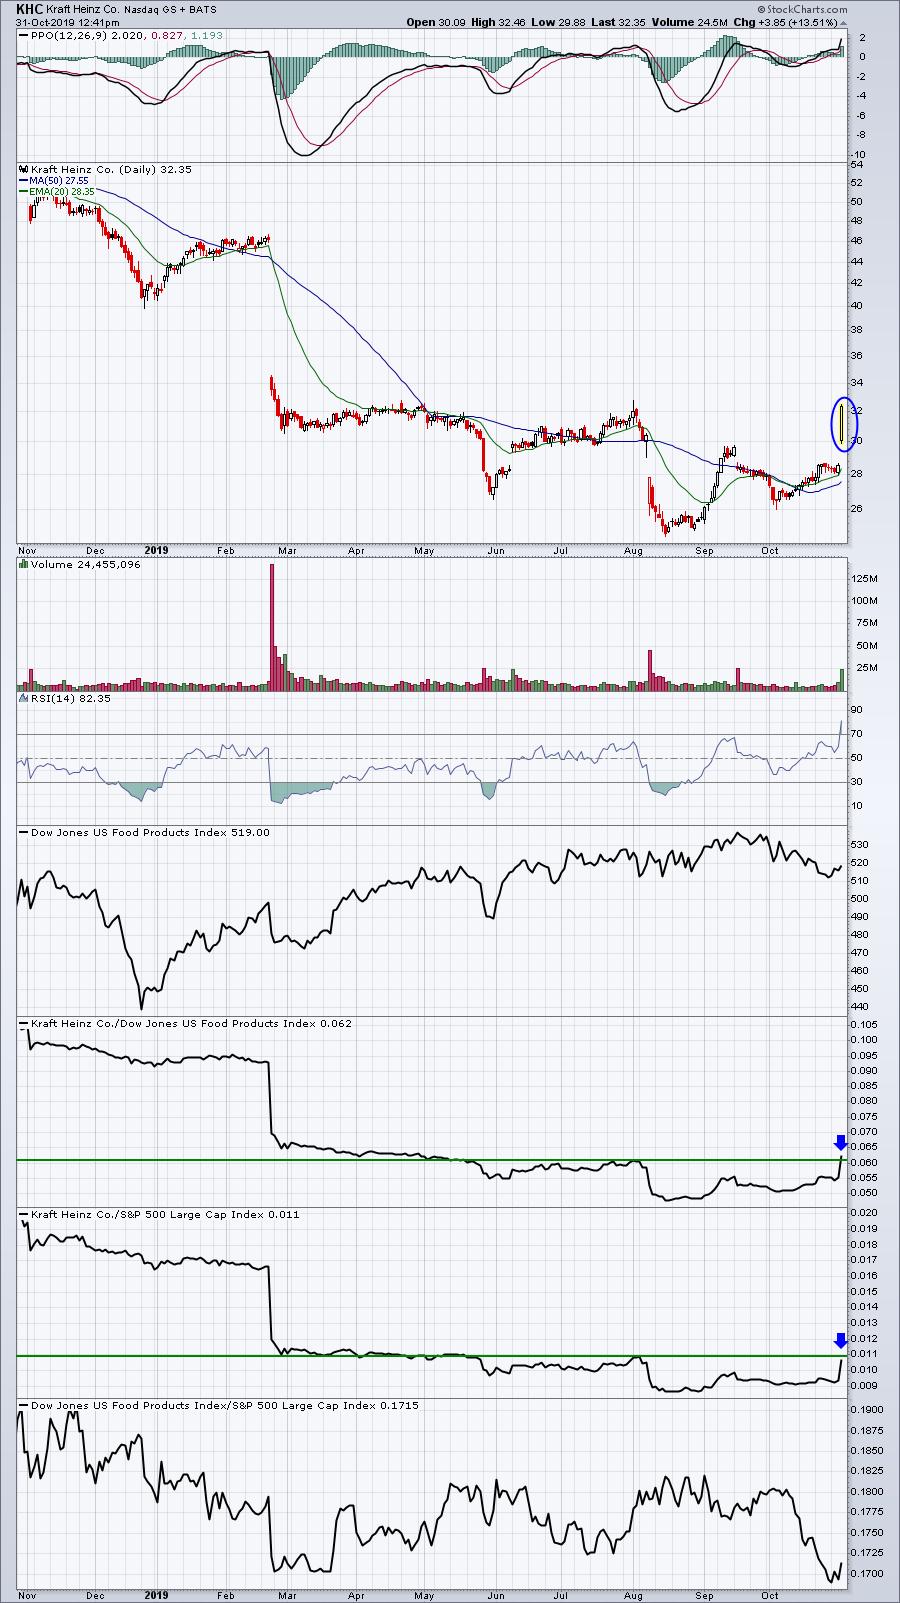
Today's candle looks like a character change to me. I'd begin treating KHC as though it's in an uptrend. KHC posted better than expected EPS this morning, although revenues fell a bit short.
AMD:
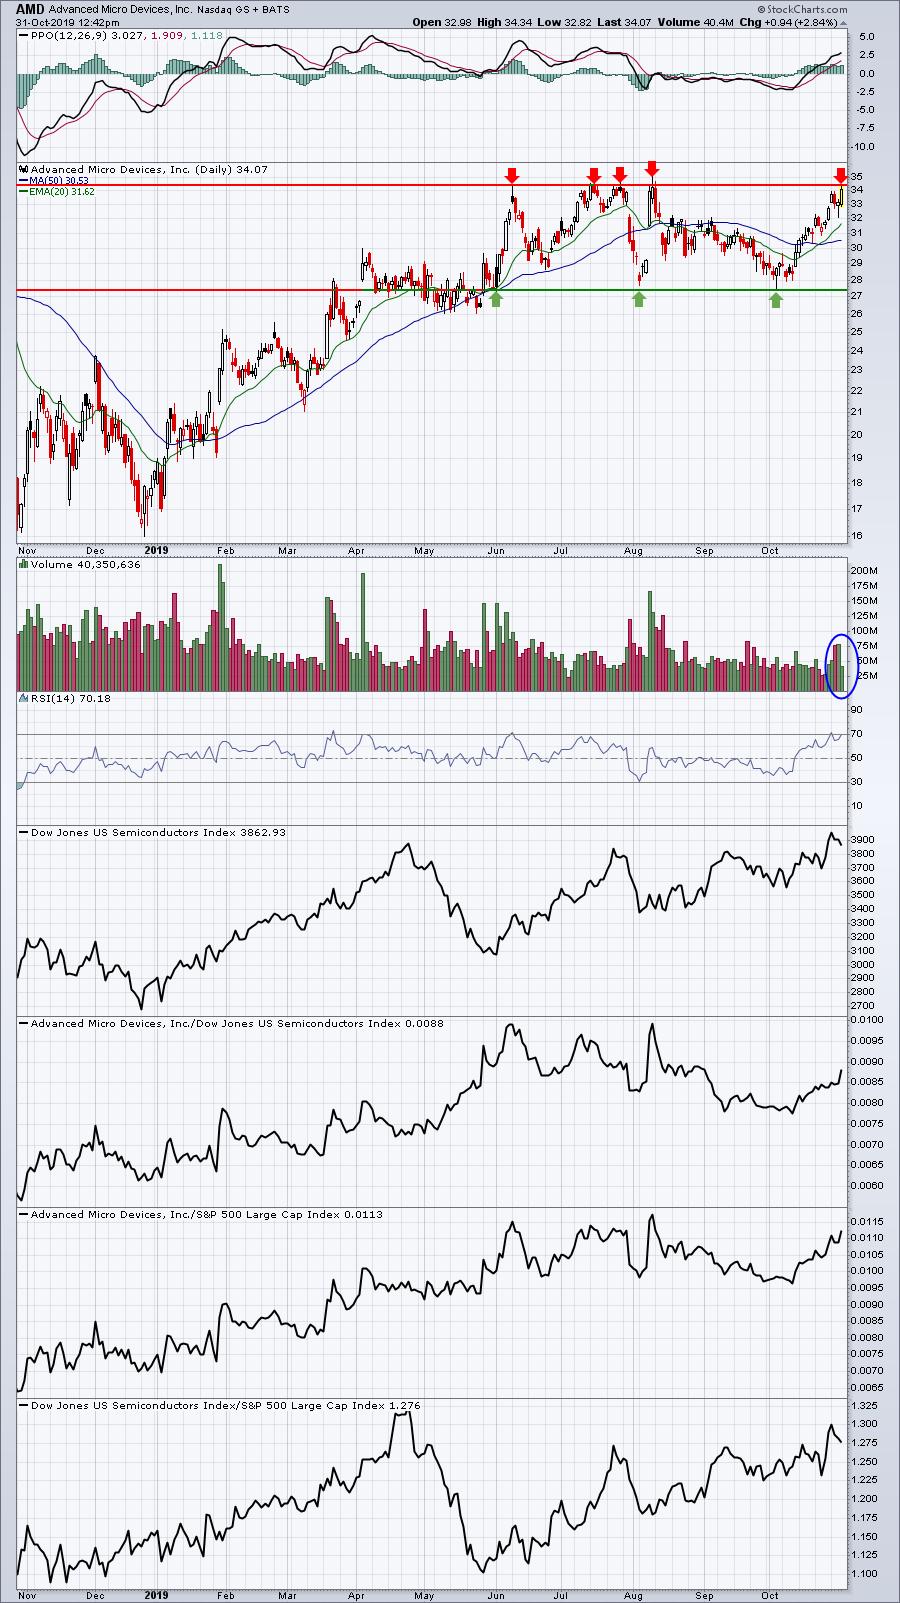
I featured AMD on October 9th when it was trading near the bottom of its rectangular consolidation range. Today, it's hitting the top. If I was trading AMD (I don't own shares), I'd sell here against price resistance. They just reported less than stellar results so selling at price resistance makes sense. I love the semis so a breakout here could certainly be in the cards, but I'd need to see it first.
Earnings Reports
Here are the key earnings reports for this week, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that are reporting are highlighted in BOLD. The number of companies reporting will be significant over the next two weeks, so please make sure you check for earnings dates for any companies you own or are considering owning:
Thursday, October 31:
RDS.A, SNY, AMT, BMY, MO, CELG, EL, CI, ICE, DD, EXC, MPC, BCE, KHC, TRI, PEG, SIRI, MPLX, MELI, FCAU, GPN, WLTW, PH, BLL, IDXX, ADM, AME, CTVA, CLX, MSCI, CHD, ANET, CDW, IP, TFX, XYL, LYV, MMP, PINS, FTNT, WAB, IT, SSNC, CPT, VICI, CVE, OTEX, W, WU, BIO. Others below $10 bil: DNKN, AYX, GNRC, SRCL, JCOM, YETI, X, FLWS, FNKO
Friday, November 1:
BRK.B, BABA, XOM, CVX, ABBV, HDB, D, CL, TRP, AIG, SRE, LYB, IMO, PBA, FTS, LNG, WPC, STX, CBOE. Others below $10 bil: FND, TDS
Economic Reports
Initial jobless claims: 218,000 (actual) vs. 213,000 (estimate)
September personal income: +0.3% (actual) vs. +0.3% (estimate)
September personal spending: +0.2% (actual) vs. +0.2% (estimate)
Q3 employment cost index: +0.7% (actual) vs. +0.7% (estimate)
October Chicago PMI: 43.2 (actual) vs. 48.3 (estimate)
Happy Halloween and happy trading!
Tom