
EB Daily Market Report - Friday, December 6, 2019
Executive Market Summary
- A robust jobs number is behind a big surge in U.S. equities today; the Dow Jones is back above 28000
- Unemployment rate fell to 3.5%, just below 3.6% expectations
- Energy (XLE) is having a strong session, followed by financials (XLF) and industrials (XLI)
- Small caps ($SML) are showing relative leadership as Volatility ($VIX) tumbles more than 7%
- The 10 year treasury yield ($TNX) has jumped 5 basis points to 1.84% on the strong jobs report
- Transportation services ($DJUSTS) and banks ($DJUSBK) are adding to their recent relative strength gains
- Our alert TPX is higher today after closing above its 20 day EMA yesterday
Market Outlook
The strong jobs report is lifting many areas of the stock market, but perhaps none more so than the S&P 600 Small Cap Index ($SML). This could be a continuing theme for quite awhile, so I'll continue to keep you updated. For today, the breakout above last week's closing high of 999.99 is noteworthy. Earlier we hit 1006.07 and, at last check, was at 1004.45:
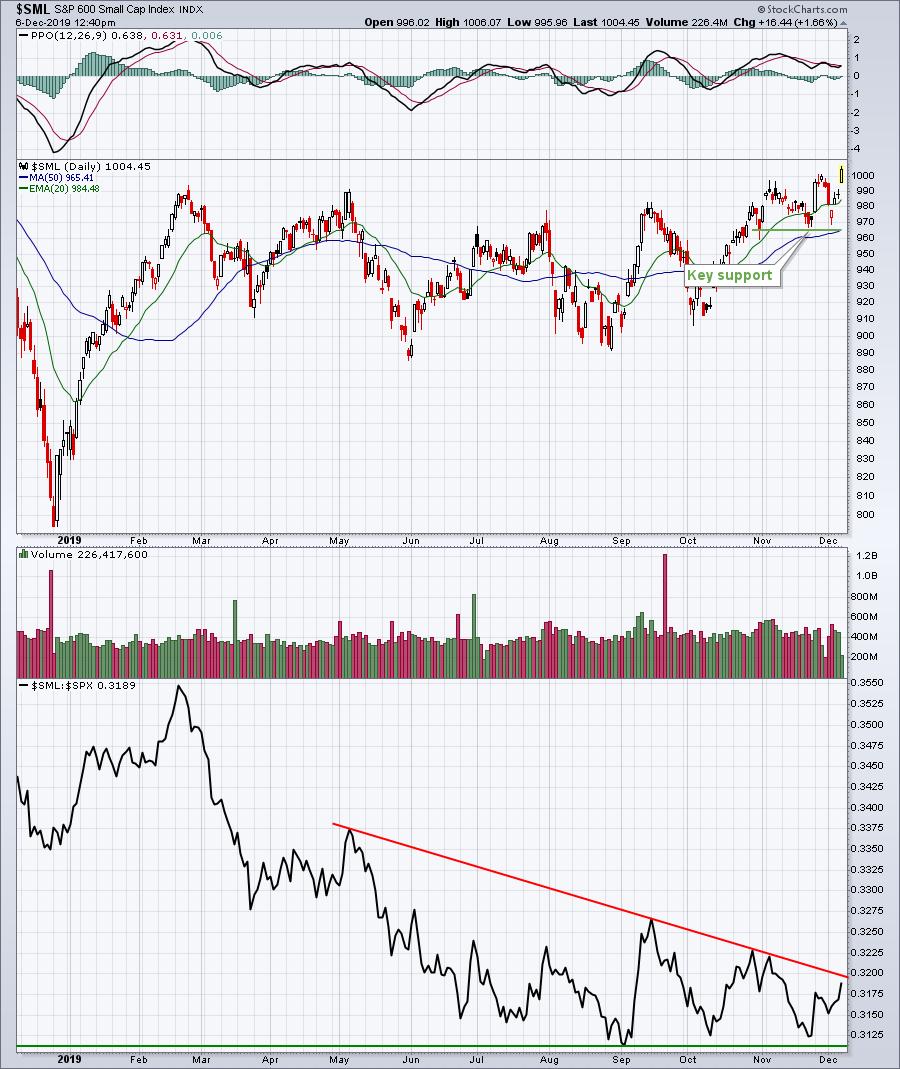
While the negative divergences remain a very short-term concern, make no mistake about it. I am extremely bullish about the next 12 months and a relative strength breakout in the SML vs. the SPX would only add to it.
Sector/Industry Focus
Financials (XLF) should be part of your portfolio, especially as long as we continue to see the following relative strength trend higher:
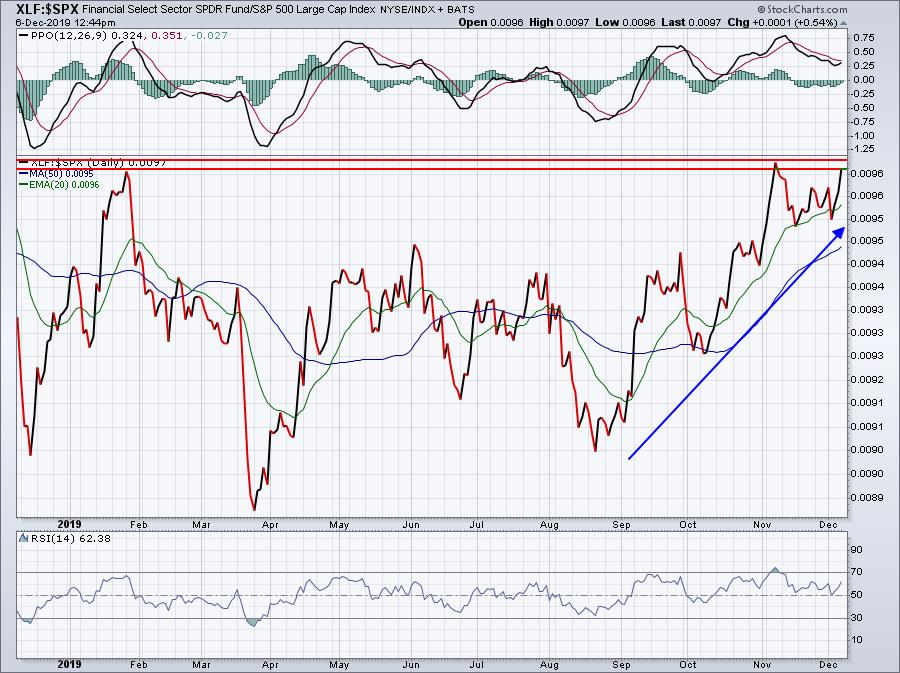
Financials have been in a relative uptrend since August and are on the verge of a major relative breakout. The Fed is buying short-term treasury bills, which will keep shorter-term maturities artificially low, helping net interest margins in banks ($DJUSBK). We added a couple banks to our portfolios this quarter for that reason. Lesson #1: Don't fight the Fed.
Strong Earnings ChartList (SECL)
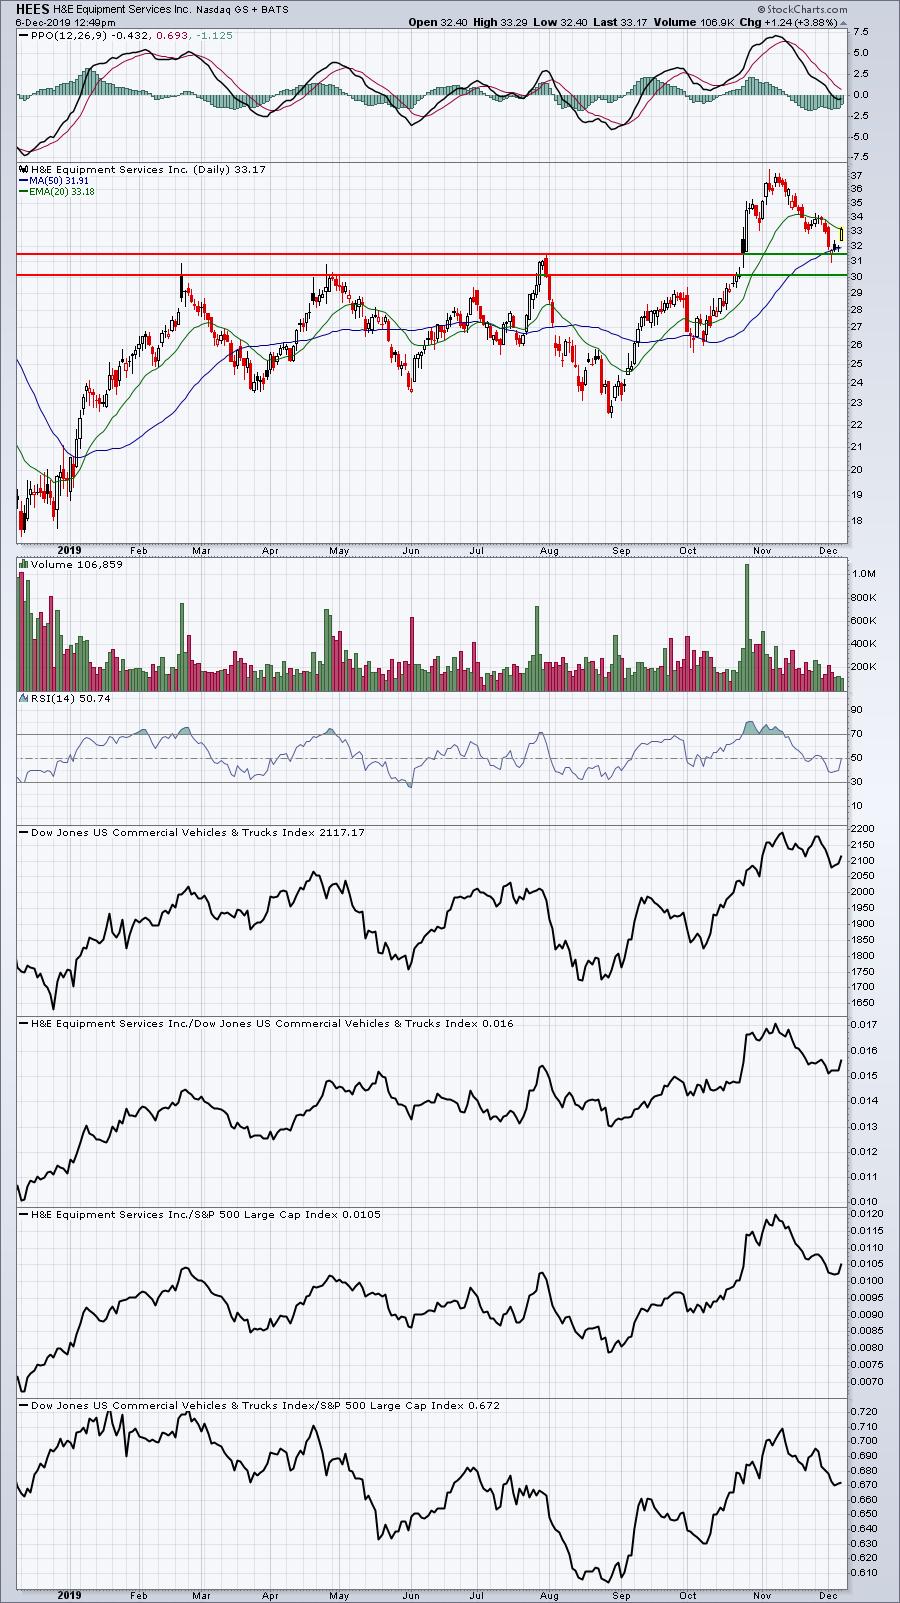
Yesterday, I highlighted portfolio stocks that were at or recently had been at major support areas during an uptrend. One stock identified was H&E Equipment Services, Inc. (HEES), a small cap stock in the commercial vehicles & trucks industry ($DJUSHR). It's bouncing beautifully today, but needs to clear that 20 day EMA in order to begin to resume its prior strength:
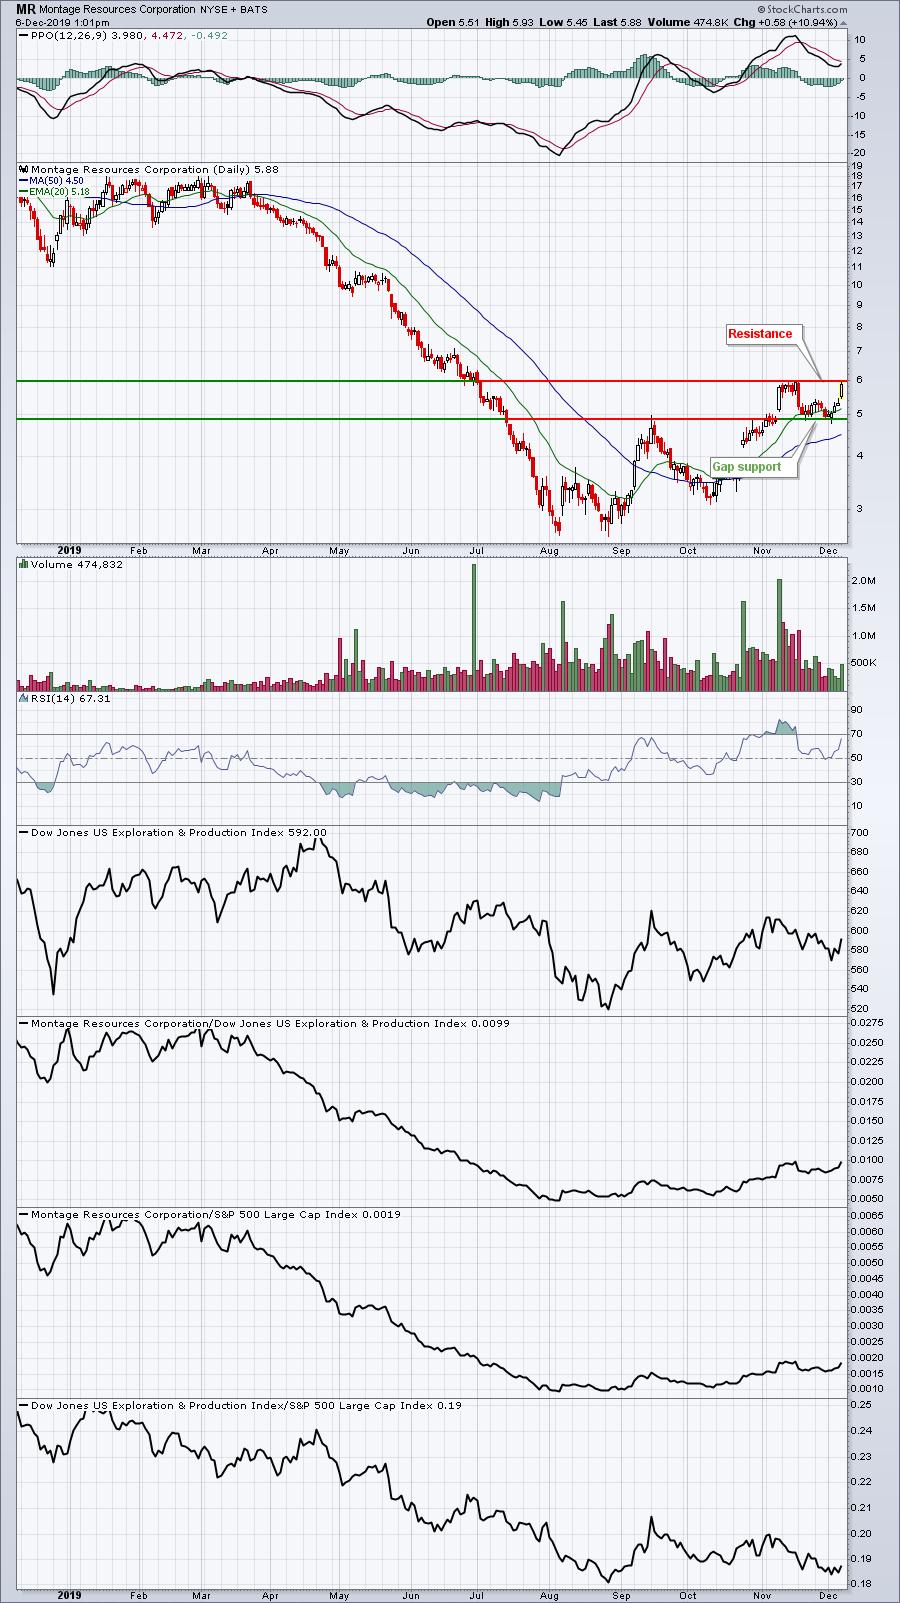
Another stock in the SECL that's moving today (and on big volume) is Montage Resources Corp (MR), an oil exploration & production ($DJUSOS) stock. After consolidating near gap support, it's back on the move and a close above 6 could really trigger a big advance:
Active Trade Alerts
We have one active trade alert currently:
TPX (+1.24%) - reports earnings on February 12. TPX closed yesterday above its 20 day EMA, a positive technical development. It's higher again today, though it's pulled back from its intraday high. The furnishings index ($DJUSFH) has rebounded this week, aiding stocks like TPX.
Movers and Shakers
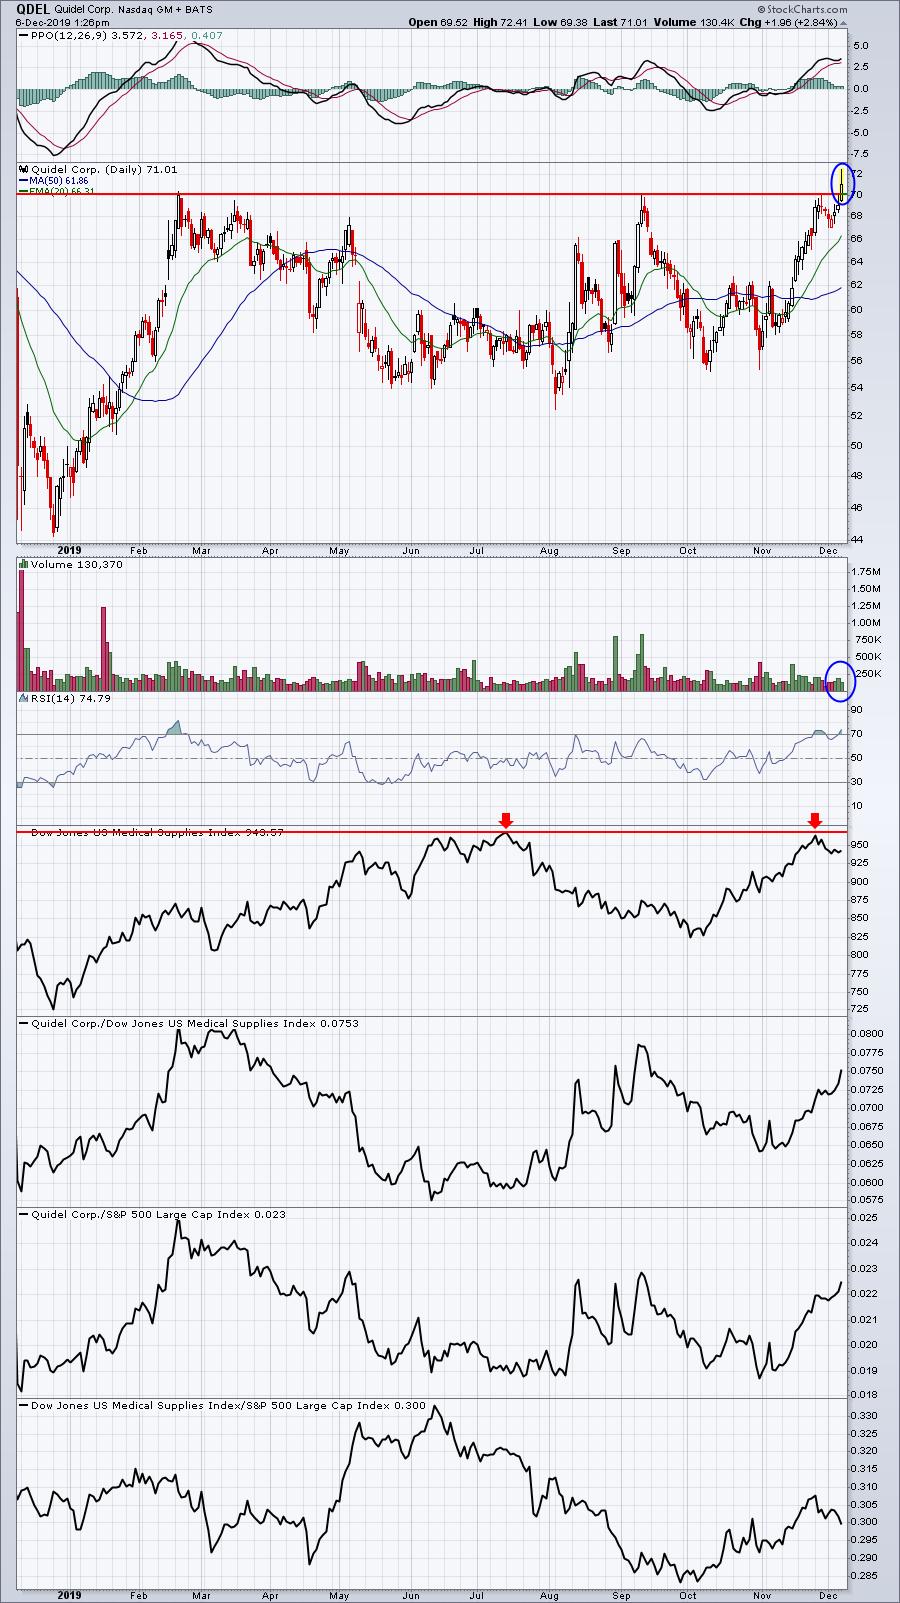
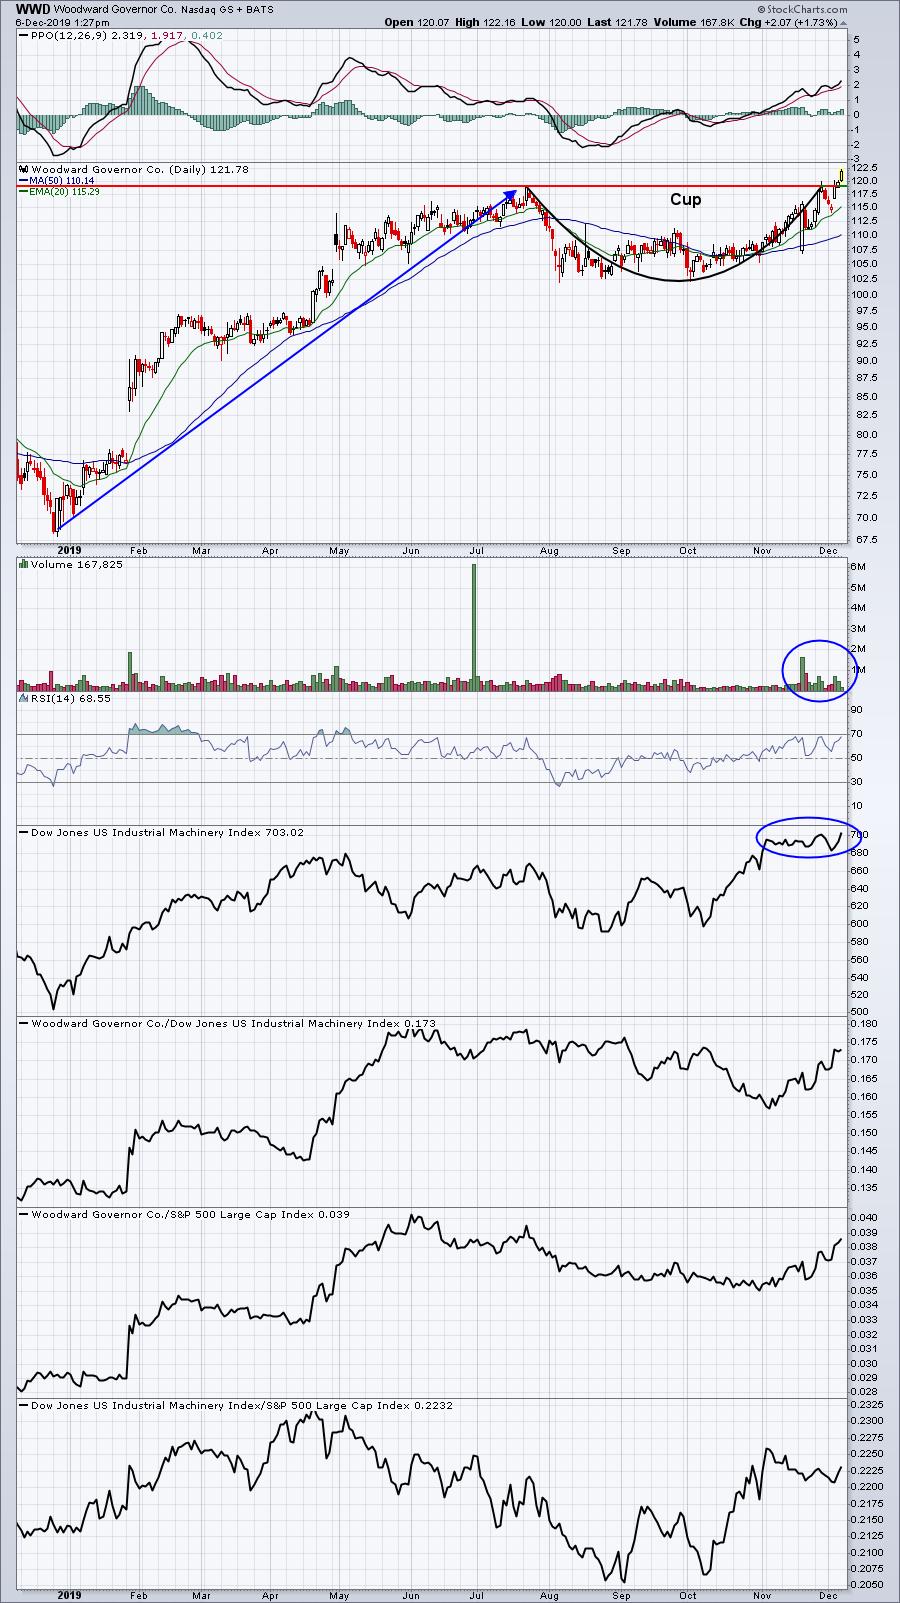
Here are stocks breaking out to 52 week highs that show strong technical formations:
QDEL:
WWD:
HOLX:
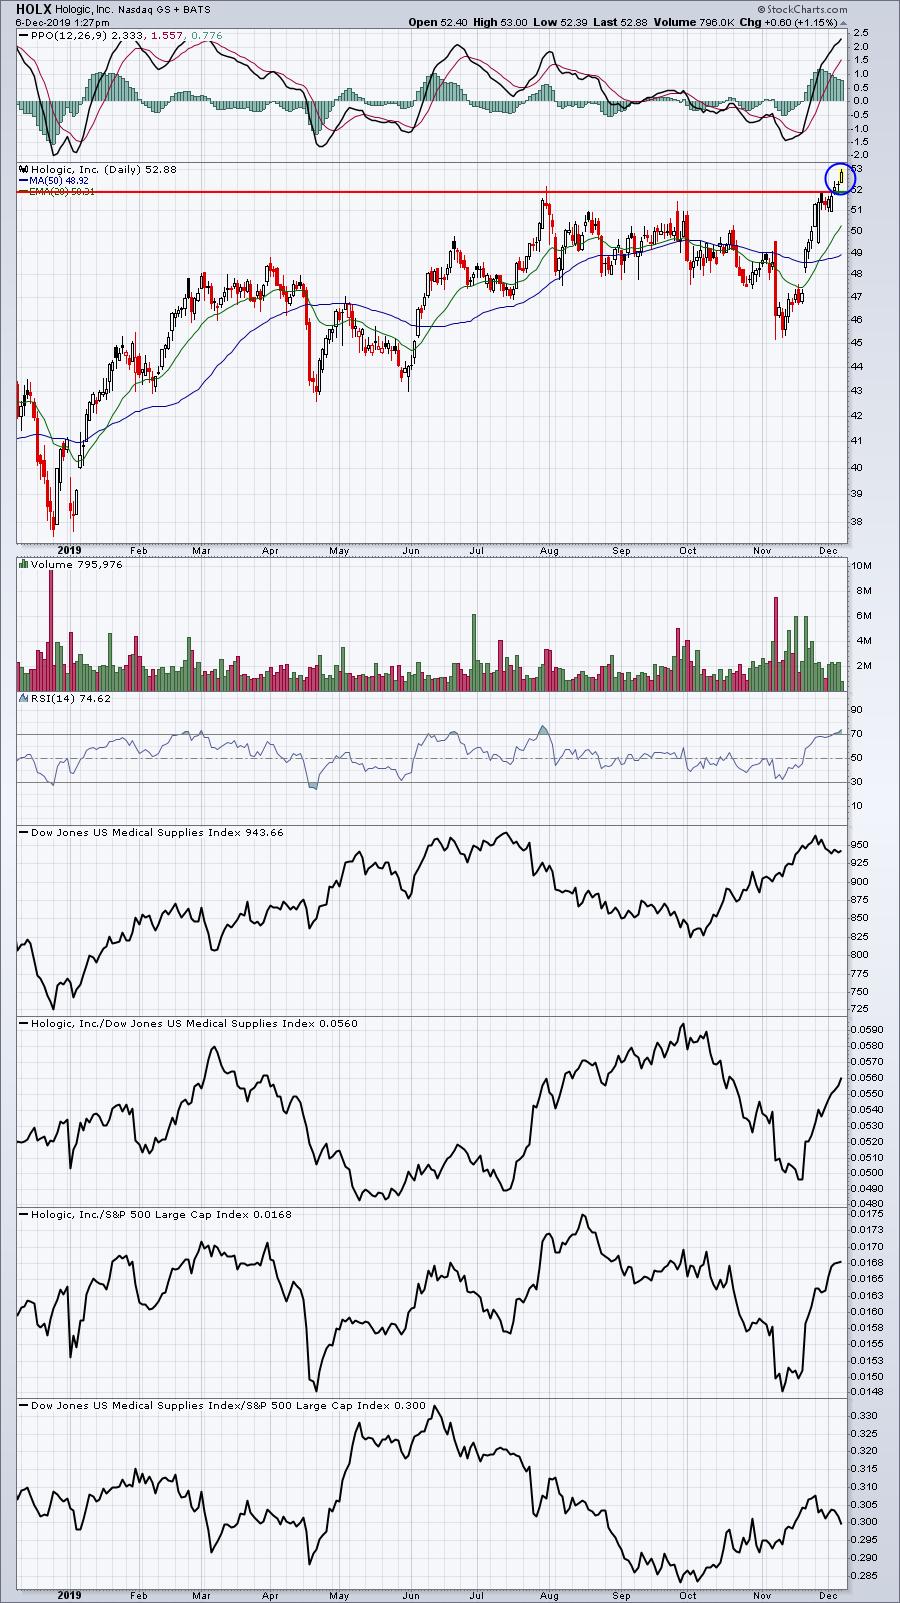
One common denominator in these three breakouts is that they occurred after lengthy basing, or consolidation, periods. That is generally a much better signal that these breakouts are likely to be followed by a further advance. I'd consider the rising 20 day EMAs to be excellent support on any pullbacks.
Earnings Reports
Here are the key earnings reports for this week, featuring stocks with market caps of more than $5 billion. I also include a few select companies with market caps below $5 billion. Finally, any portfolio stocks (or active trade alerts) that will be reporting results are highlighted in BOLD. Please make sure you check for earnings dates for any companies you own or are considering owning:
Friday, December 6:
None
Monday, December 9:
MTN, CHWY, MDB, CASY, TOL. Others below $5 bil: THO, SFIX
Economic Reports
November nonfarm payrolls: 266,000 (actual) vs. 180,000 (estimate)
Nonfarm private payrolls: 254,000 (actual) vs. 168,000 (estimate)
November unemployment rate: 3.5% (actual) vs. 3.6% (estimate)
November average hourly earnings: +0.2% (actual) vs. +0.3% (estimate)
December consumer sentiment: 99.2 (actual) vs. 96.9 (estimate)
Happy trading!
Tom