
EB Daily Market Report - Wednesday, January 15, 2020
Executive Market Summary
- December PPI was released this morning and it mirrored CPI yesterday, coming in below expectations
- The 10 year treasury yield ($TNX) is down 3 basis points to 1.79%; it's been a rough 5 days here
- This week's advance is being led mostly by defensive sectors, see Sector/Industry focus below
- Healthcare (XLV), utilities (XLU), and real estate (XLRE) are leading today
- Energy (XLE) and financials (XLF) are lagging; crude oil ($WTIC) has been free-falling the past 5-6 days
- Our only active trade alert VC is down fractionally today, but has definitely been on the improve
Special Event
We are having a special impromptu webinar today at 4:30pm EST that will likely last 45 minutes or so. It will be recorded for those who cannot make it. I'm seeing a number of warning signs, all short-term in nature, that I want to communicate to our members. Those with a long-term trading/investing mentality may not find the webinar as useful as shorter-term traders. There are inefficiencies in the stock market that can drive short-term action and I'll be discussing that.
Here's a link to today's webinar room:
The room will be open no later than 4:00pm EST.
Market Outlook
I've written previously about the October 27th (close) through January 18th (close) period as being the most bullish period of the year. We've gone up nearly every year since 1950 (57 of 69 years) during this period. Barring a collapse of mega proportions, this period will end at Friday's close in positive territory once again. Looking into next week, however, suggests a different outcome. January 20th (Monday) is the 3rd worst calendar day of the year, trailing only October 19th (think Black Monday 1987) and October 22nd. It has an annualized return of -83%. Mondays that fall after options expiration are also typically very poor stock market days.
We've had a huge runup in the stock market since the early-October low. It wouldn't be a bad thing to see some profit taking over the next couple days to couple weeks. We'll see.
Sector/Industry Focus
While aggressive sectors have been the driving force behind this latest secular bull market advance, which is very encouraging, there's been a shift lately that's worth noting:
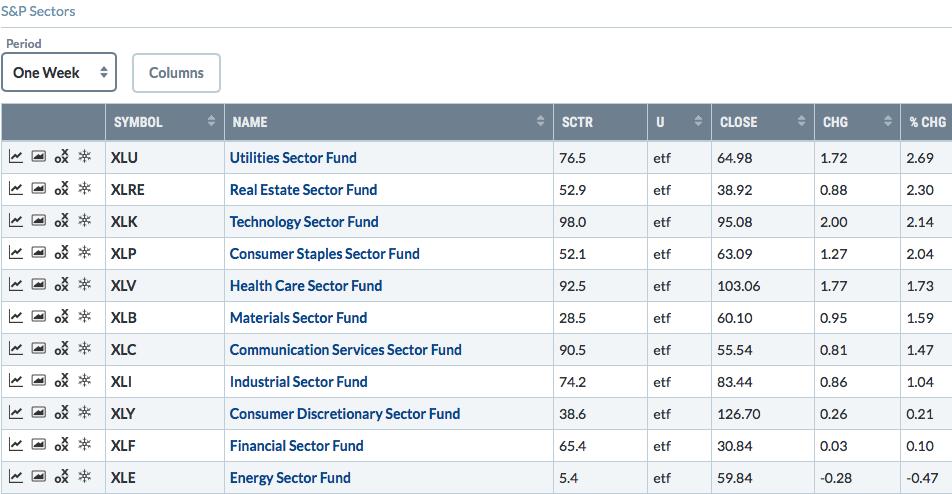
This shows sector leadership over the past week and it's suggesting this rally could be nearing an end. I get nervous when Wall Street starts moving into defensive areas. We've seen treasury prices rising over the past week and that, combined with strength from defensive sectors, is painting a picture that this rally is growing tired. We've been rallying for months in anticipation of strong quarterly reports. Now that those reports are beginning to be released, it appears Wall Street wants to limit its risk. We may want to do the same.
Again, I want to emphasize this is a short-term, temporary concern of mine - perhaps a few days to 2-3 weeks. I believe we go much higher in 2020.
Active Trade Alerts
We have just one active alert right now:
VC (-0.10%) - reports earnings on February 19. VC didn't run higher with the rest of the market the past couple months, so I'm not as concerned about a big selloff. Plus, we have a fairly tight closing stop of 83.50, just beneath our final entry price of 84.00. We finally managed to close above the 20 day EMA yesterday, so another close there today would add to the recent bullishness.
Strong Earnings ChartList (SECL)
I'm not looking to buy anything as we approach options expiration this Friday and I'll talk more about that in this afternoon's webinar. If I did buy, I'd only do so if I could keep a very tight stop in place.
Movers & Shakers
Once again, I'm not adding anything. However, a big SCTR mover to the downside has an interesting chart:
NKTR:
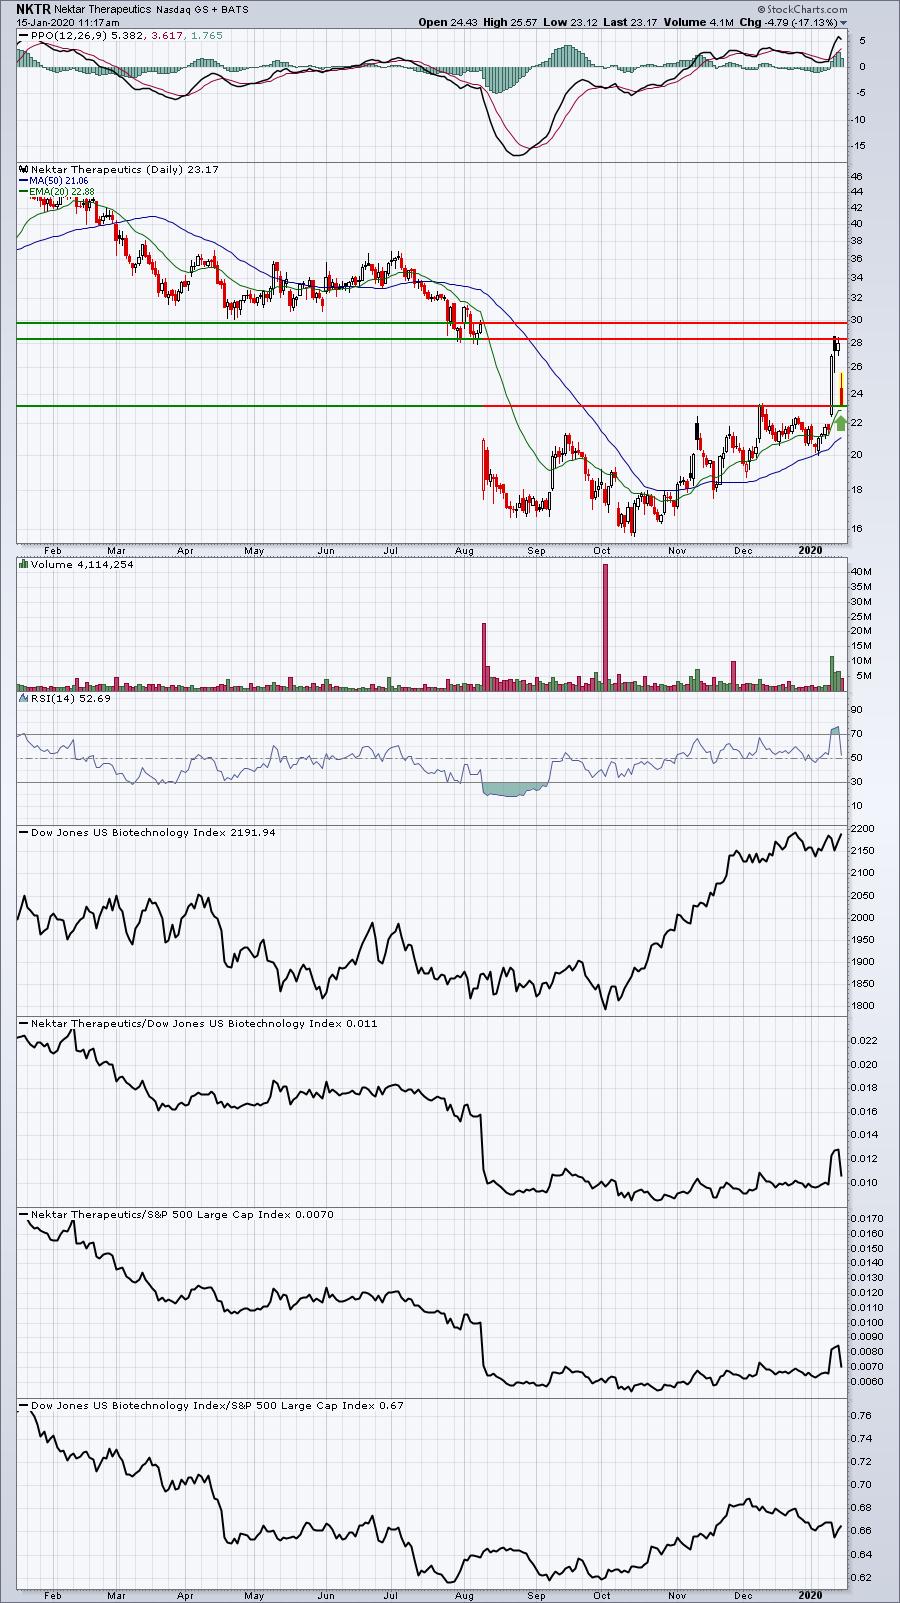
It's been a rough day for NKTR thus far, but price support and the rising 20 day EMA are close at hand. Will they hold?
Earnings Reports
Here are the key earnings reports for this week, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks (or active trade alerts) that will be reporting results are highlighted in BOLD. Please make sure you check for earnings dates for any companies you own or are considering owning:
Wednesday, January 15:
BAC, UNH, USB, GS, BLK, PNC, SCHW, KMI
Thursday, January 16:
TSM, MS, CSX, BK, PPG. Others less than $10 bil: OZK, PRGS
Friday, January 17:
HDB, SLB, STT, FAST, CFG, RF, KSU, JBHT
Economic Reports
December PPI: +0.1% (actual) vs. +0.2% (estimate)
December Core PPI: +0.1% (actual) vs. +0.2% (estimate)
January empire state manufacturing survey: 4.8 (actual) vs. 3.6 (estimate)
Happy trading!
Tom