
EB Daily Market Report - Tuesday, February 18, 2020
Executive Market Summary
- Wall Street opened lower after Apple (AAPL) warned that its quarterly revenues would be adversely impacted by the coronavirus
- Commodities are mixed, but gold ($GOLD) is up more than 1% and above $1600 per ounce
- Crude oil prices ($WTIC) have moved back below $52 per barrel
- The 10 year treasury yield ($TNX) is down 3 basis points to 1.55%, keeping a lid on U.S. equities
- All of our major indices are lower today, with slight underperformance by small caps ($SML)
- Defensive utilities (XLU, +0.86%) is the best sector today, but communication services (XLC, +0.54%) is also higher; energy (XLE, -1.23%) lags
- We have one active trade alert, which failed at its 20 day EMA earlier today
Market Outlook
At the end of last week, we were battling a short-term concern - a 60 minute negative divergence on our key indices. I suggested that we could see short-term selling, maybe 1% or so, to simply relieve the short-term momentum issue. Today, we're seeing that selling:
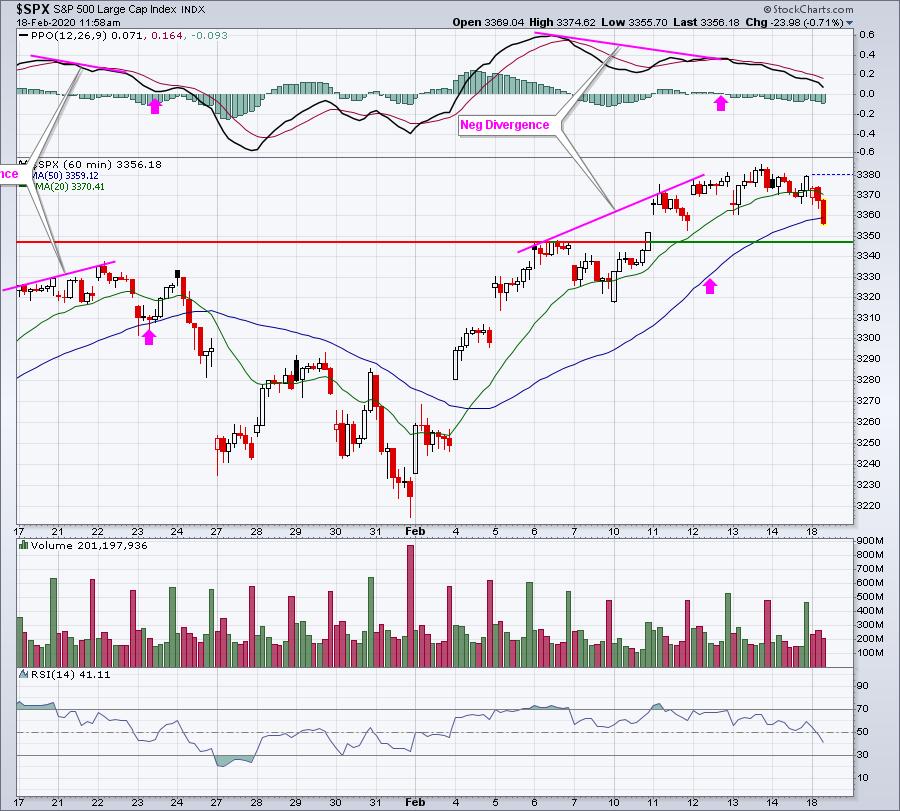
We can't predict whether the short-term support level just below 3350 will hold, but I'll definitely be watching to see if it does. Keep in mind that today is the 18th of February and that the 19th through the 25th of ALL calendar months is historically the worst time for equities. Much of that weakness can likely be attributed to the expiration of monthly options. That occurs the 3rd Friday of every month, which is this Friday, February 21st.
Sector/Industry Focus
Despite some selling today, internet stocks ($DJUSNS) are holding up well and in full breakout mode:
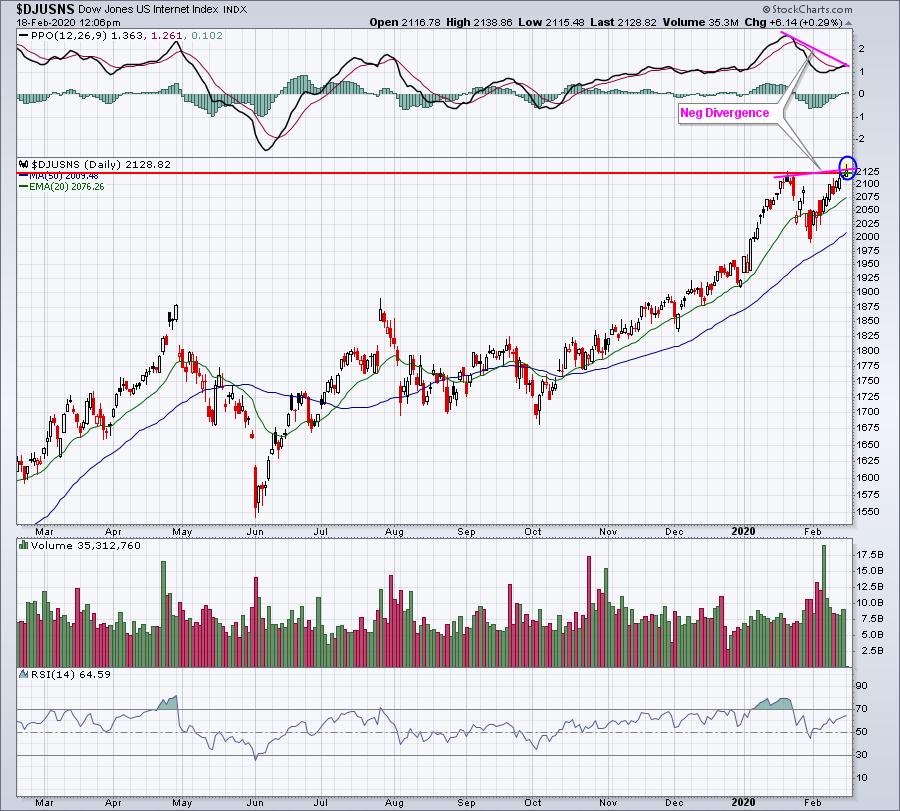
Let's see how the DJUSNS finishes today. A big reversal and false breakout could lead to further short-term selling and consolidation, which wouldn't be a horrible thing at all.
Active Trade Alerts
Currently, we have one active trade alert, as follows:
DKS (-1.77%) - reports its next earnings on March 10th. Since DKS became an alert last week, it's tried twice to clear 20 day EMA resistance without success. Today, it's down and challenging a key short-term price support level, actually breaking below it on an intraday basis. We want to keep a tight leash on trades, so our closing stop is at 43.25. DKS is threatening to violate our stop. Here's a quick look at the chart:
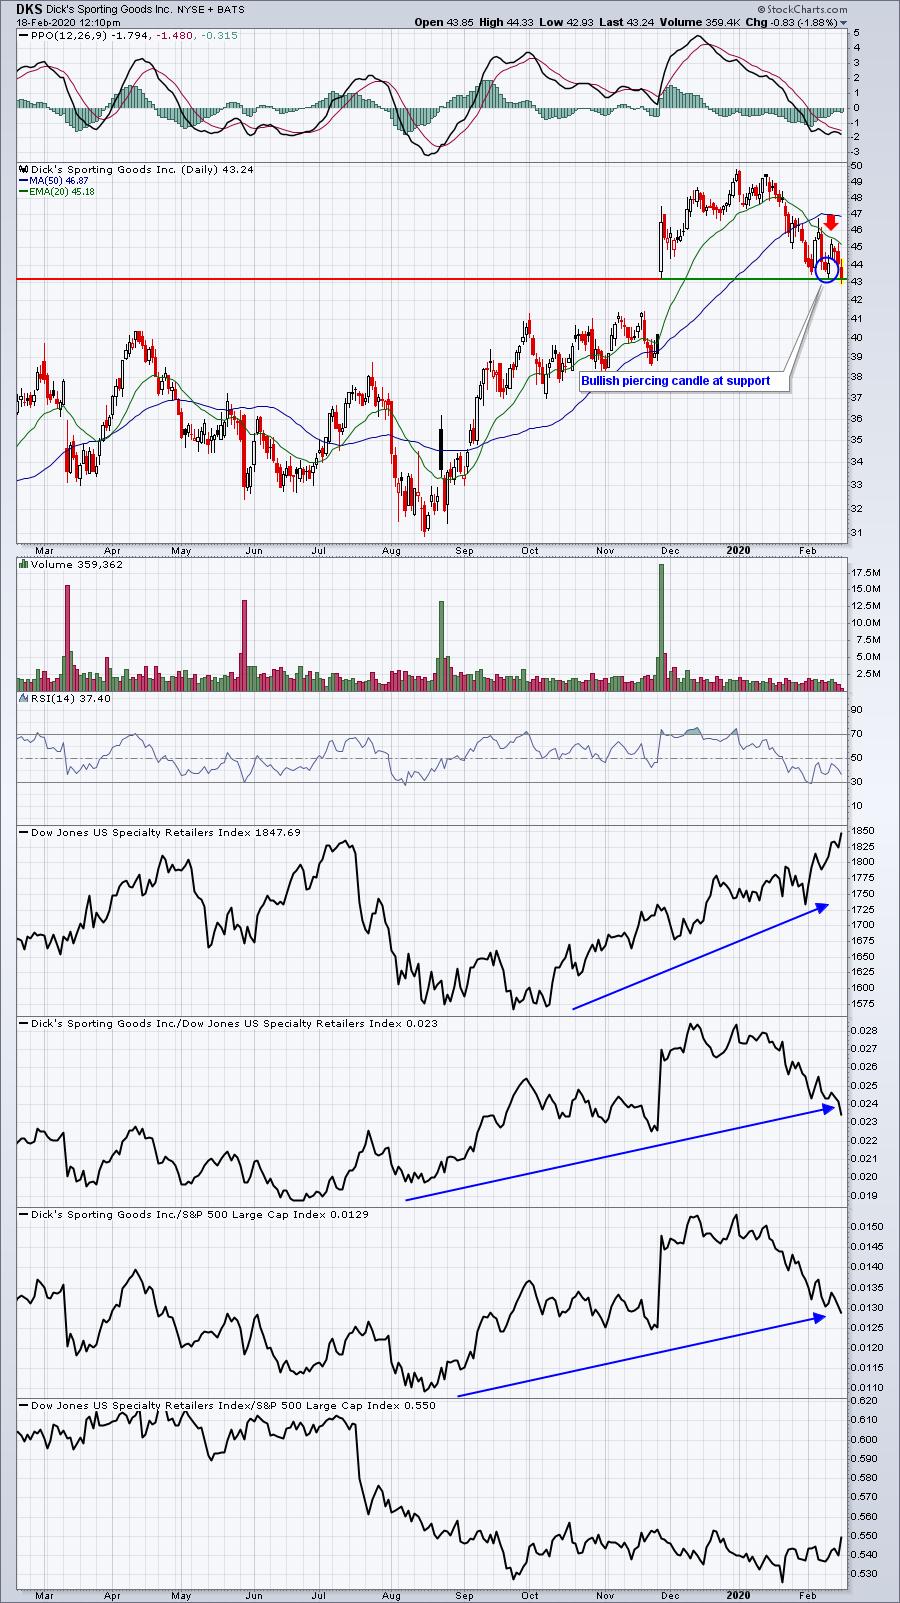
You can see it's right at our closing stop at 43.25 and there was an earlier low at 42.93. A more conservative approach could be to use an intraday stop below today's earlier low. That would be to avoid a larger loss. However, the flip side, is that market makers build inventory by creating false breakdowns. In my opinion, the absolute most difficult trading decision to make is whether to use intraday or closing stops. There are arguments to support both. My preference most of the time is to buy close to key support and use a closing stop. But it's truly a personal choice based on the amount of risk you are willing to take.
Strong Earnings ChartList (SECL)
I looked at the best performers today, given that the overall market is weak. Here were three stocks off our SECL that are technically solid:
TSLA:
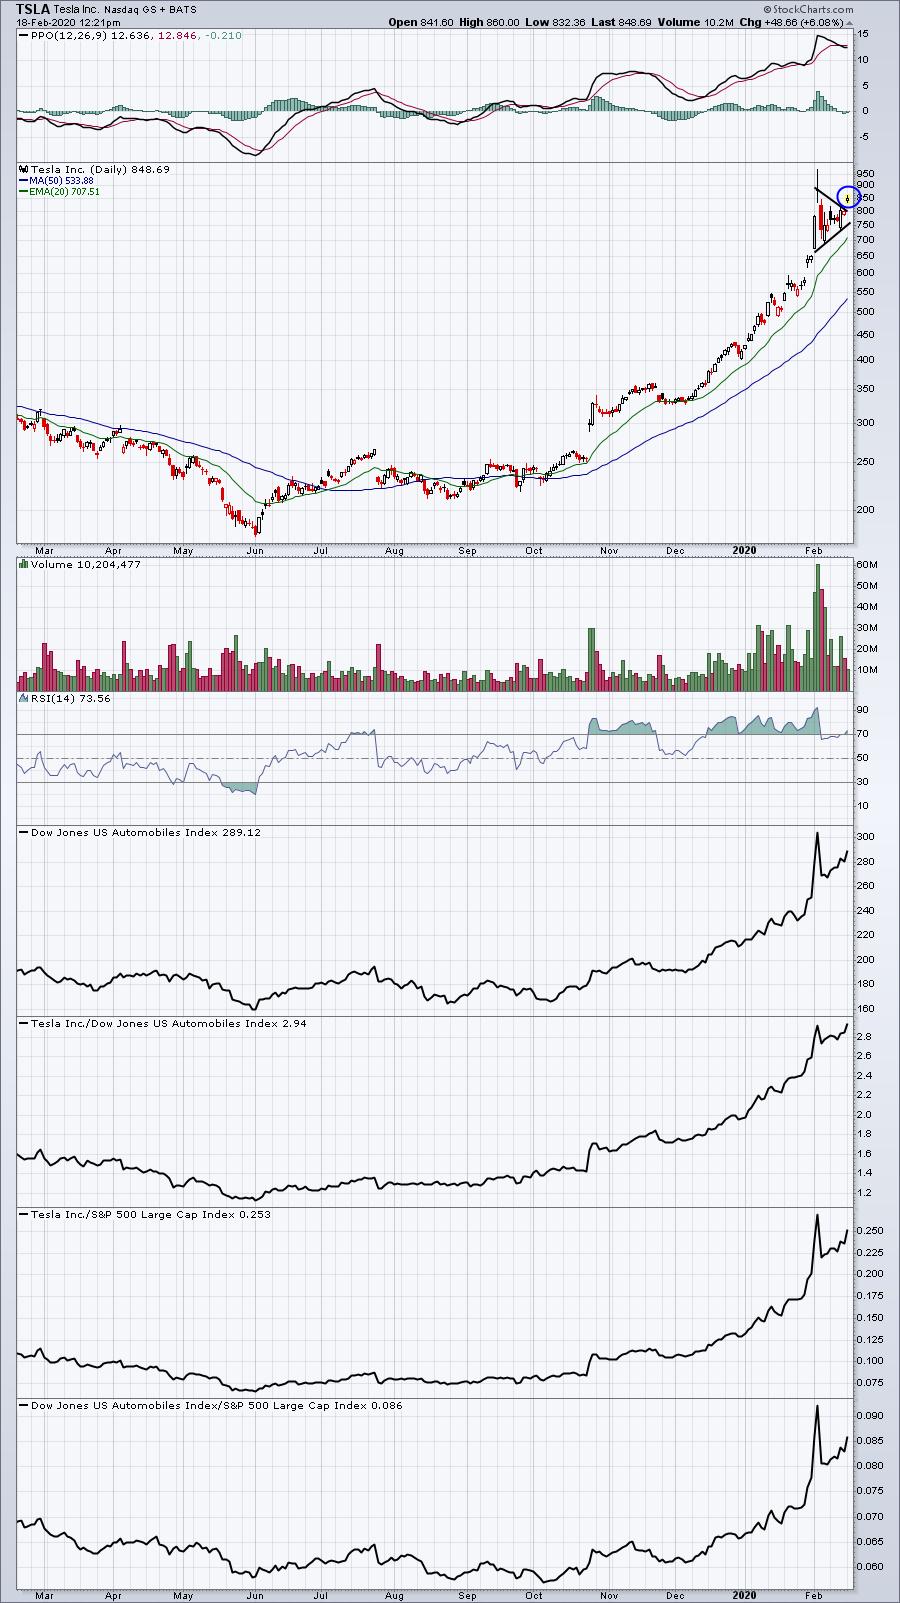
Listen, I know that TSLA is extremely volatile and it's difficult for many to fathom paying 850 for a stock that was less than half that price 5-6 weeks ago. But there is tremendous demand for a company that, all of a sudden, is experiencing significant EPS growth. Today's gap higher appears to be breaking its symmetrical triangle pattern. These patterns typically break in the direction of the prior trend, which is higher. Those who cannot stomach the higher risk and volatility should avoid TSLA. But those who can tolerate the risk should consider it. I believe TSLA is heading much higher given the current economic environment. It's going to be a very bumpy and volatile road ahead, but I wouldn't be surprised at all to see TSLA double from its current level in 2020.
AKAM:
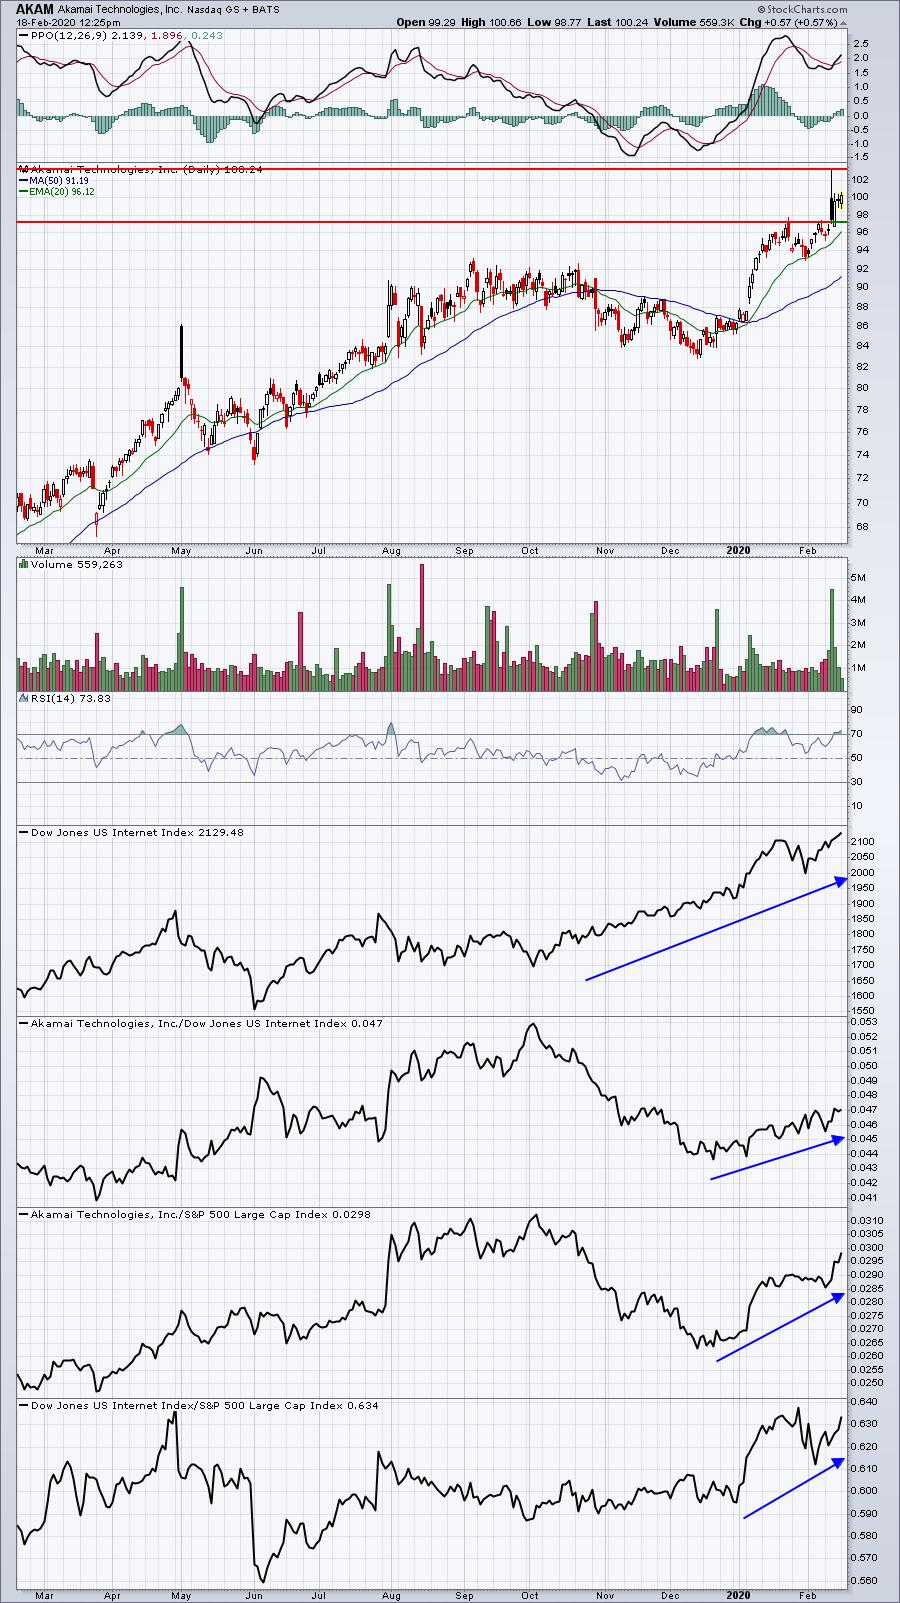
AKAM is in a position to benefit from the strength in internet stocks. While internet still has a long way to go to reach its initial pattern measurement (discussed here previously), there are short-term concerns like the one mentioned above in the Sector/Industry Focus.
SYNA:
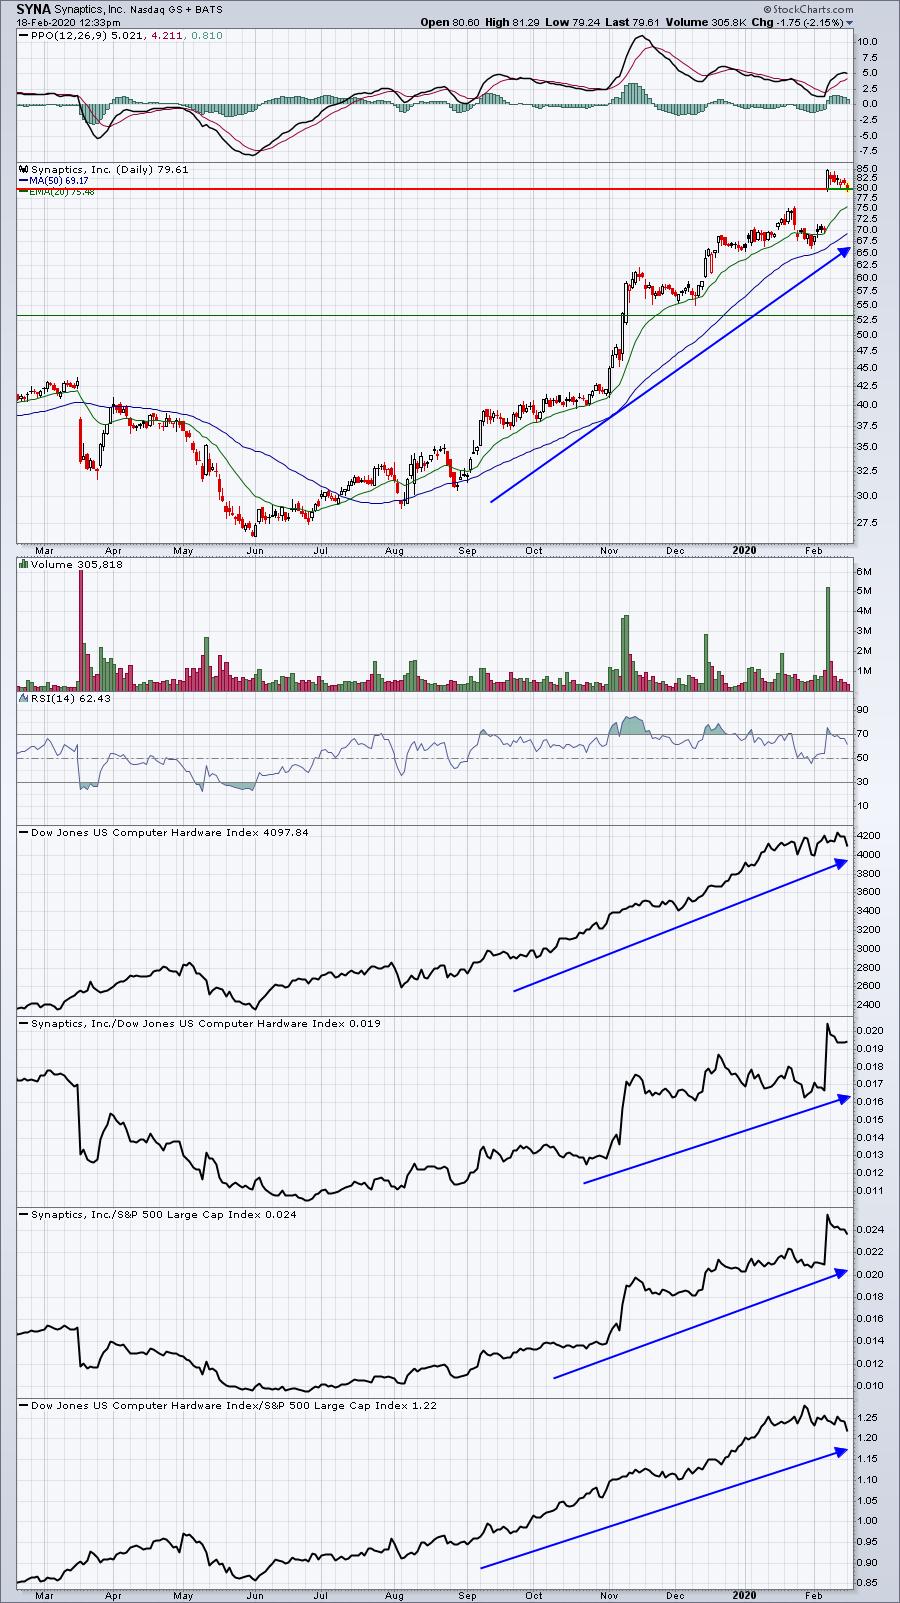
SYNA is one of the best stocks in the computer hardware space ($DJUSCR). After its recent blowout quarterly earnings report, SYNA gapped up to 80.00 and traded intraday down to 79.10. Entering at the current level could provide a very tight stop on any close below 79.00. A reversal and close today above 80.00 would be short-term bullish. I had posted about SYNA recently as it moved beneath 82, but now it has completely returned to the top of gap support.
Movers & Shakers
Before considering further trades, especially those outside the SECL, I think it's a good idea that we watch the S&P 500 for now. Last week's negative divergence on the hourly chart, combined with today's weakness and the upcoming bearish historical period simply says to be a little bit careful here. I'll likely be ready to provide some additional trading candidates tomorrow, but let's watch the SPX first.
Earnings Reports
Here are the key earnings reports for this week, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks (or active trade alerts) that will be reporting results are highlighted in BOLD. Please make sure you check for earnings dates for any companies you own or are considering owning:
Monday, February 17:
None. Others less than $10 bil: SCI, GDI, FLS, RIG
Tuesday, February 18:
WMT, MDT, ECL, VRSK, A, AWK, NTR, VMC, TRU, INVH, LDOS, CXO, EXR, WAB, VNO, ALLE, EXPD, FANG. Others less than $10 bil: AAP, AMED, HLF, CHH, ENPH, EVBG
Wednesday, February 19:
PBR, ADI, ET, ETR, O, WMB, SNPS, CPRT, PXD, VIV, DISH, GRMN, SUI, GPC, TS, HST, Y, ELAN, ZG, NDSN. Others less than $10 bil: ALB, CONE, SEDG, ALSN, FIVN, WING, JACK, SNBR
Thursday, February 20:
SO, AEP, NEM, SBAC, ED, ES, HRL, VTR, TFX, CIB, VIAC, EPAM, VICI, DPZ, NCLH, GLPI, HSIC, LKQ. Others less than $10 bil: LAMR, OLED, ZS, DBX, FSLR, NUVA, APPN, AAN, EHTH, ACIA, VC, FIT, HEES
Friday, February 21:
RY, DE, MGA, WPC, PNW. Others less than $10 bil: ITT, CFX, B, HMSY, SOGO
Economic Reports
February empire state manufacturing report: 12.9 vs. 4.0
February housing market index: 74 vs. 75
Happy trading!
Tom