
EB Daily Market Report - Friday, July 24, 2020
Executive Market Summary
- Futures were rough and all of our major indices opened lower
- Asian stocks were lower overnight and that selling pressure carried over to Europe; the German DAX is currently lower by 2%
- June new home sales topped expectations by more than 10%
- The S&P 500 appears to have lost its short-term support at 3232, next up is its 20 day EMA at 3189
- Technology shares (XLK, -0.64%) are among the weak after Intel (INTC, -15%) disappointed investors with its sub-par quarterly report; INTC's loss is AMD's gain (+15.68%)
- Health care (XLV, -1.10%) is today's worst sector as biotechnology stocks ($DJUSBT, -1.82%) are a target of sellers
- Tesla (TSLA, -5.18%), while off its intraday low, has weakened today to test its rising 20 day EMA
- The big story with the falling dollar (UUP, -0.35%) hasn't changed, it's weak again today
- Consumer discretionary (XLY, +0.29%) is the only sector higher on today's session
Market Outlook
The following is a chart that illustrates the rotation between growth and value stocks throughout this pandemic. As the line moves higher, growth is outperforming. When the line moves lower, value is outperforming. We're currently in a period of outperformance by value and we need to respect that as long as it continues:
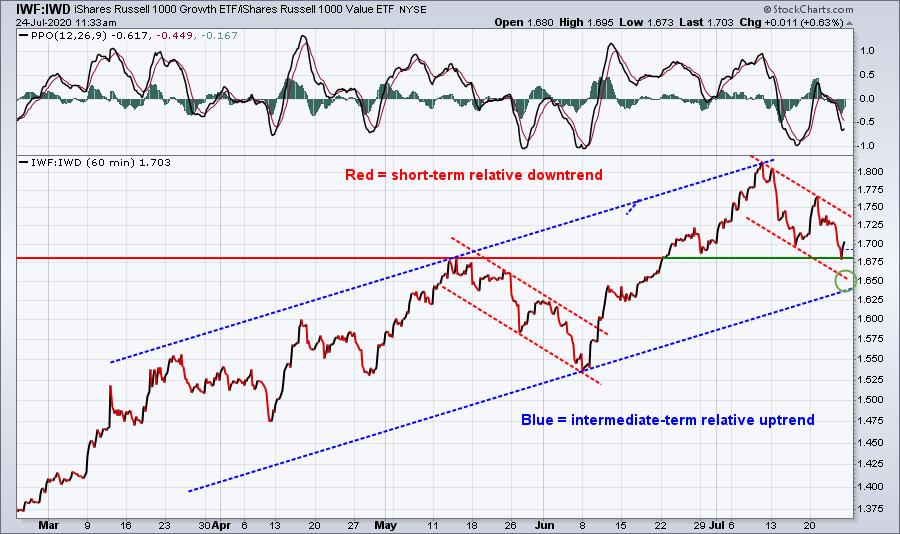
It's not easy to find the exact relative bottom when we're downtrending like we are now. But as we move lower, I believe the reward to risk really improves in terms of accumulating growth stocks. Maybe the run is over, but I very highly doubt it. Historically-low interest rates and a strengthening economy typically bode very well for companies that can grow their earnings rapidly. But we do need to balance this enthusiasm with the more bearish summer season.
Sector/Industry Focus
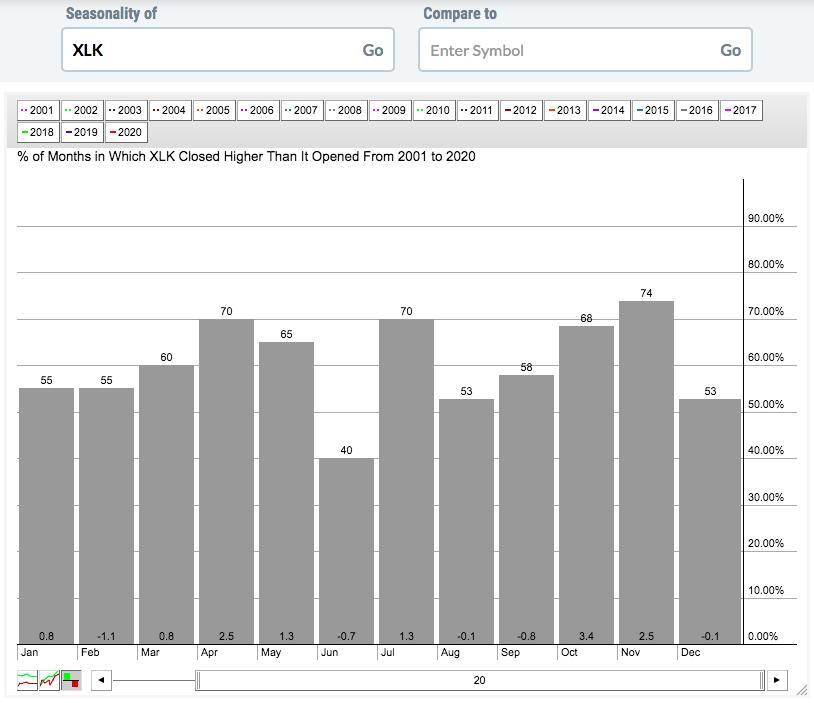
The primary reason the stock market struggles during the summer is that the tendency is for technology stocks (XLK) to move lower during the summer months of August and September. Check out this seasonality chart:
Perhaps the biggest culprit of the market and technology swoon during the summer is the semiconductor industry ($DJUSSC). Their seasonal weakness grows as we move deeper and deeper into summer:
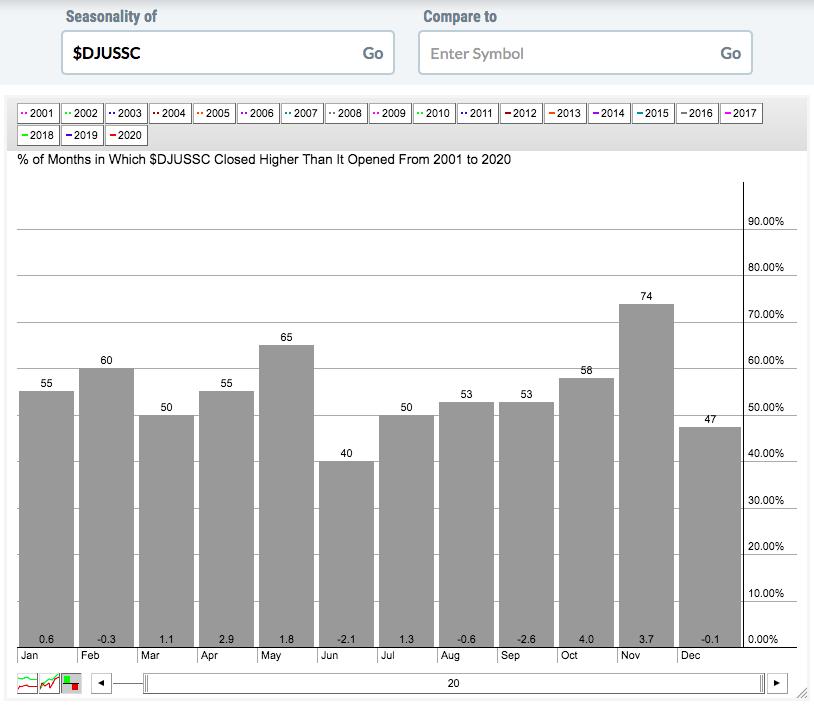
While the DJUSSC has risen more often than not over the past 20 years, their average return of -2.6% suggests that the bad years are REALLY bad, while up years are more modest. Seasonality certainly points to further consolidation and/or weakness ahead.
ChartLists
Biotechs have been roughed up quite a bit this week and it really shows when we look at the weekly performance of our Strong Future Earnings ChartList in Summary View:
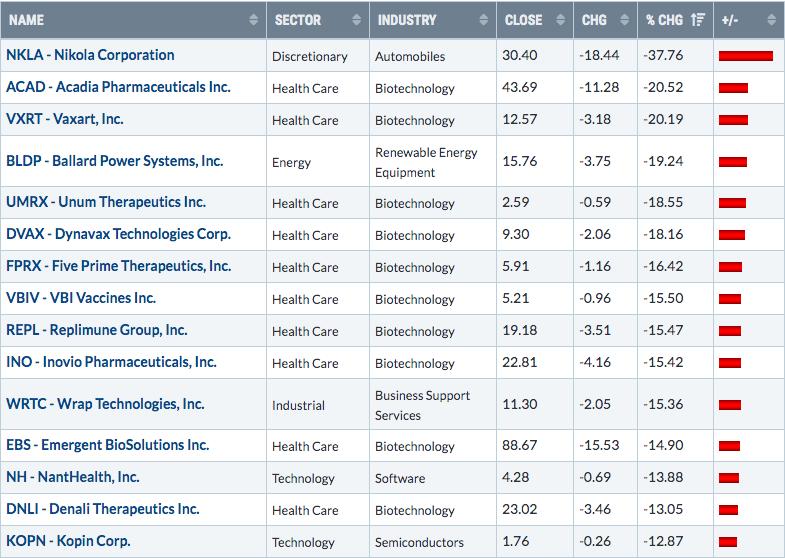
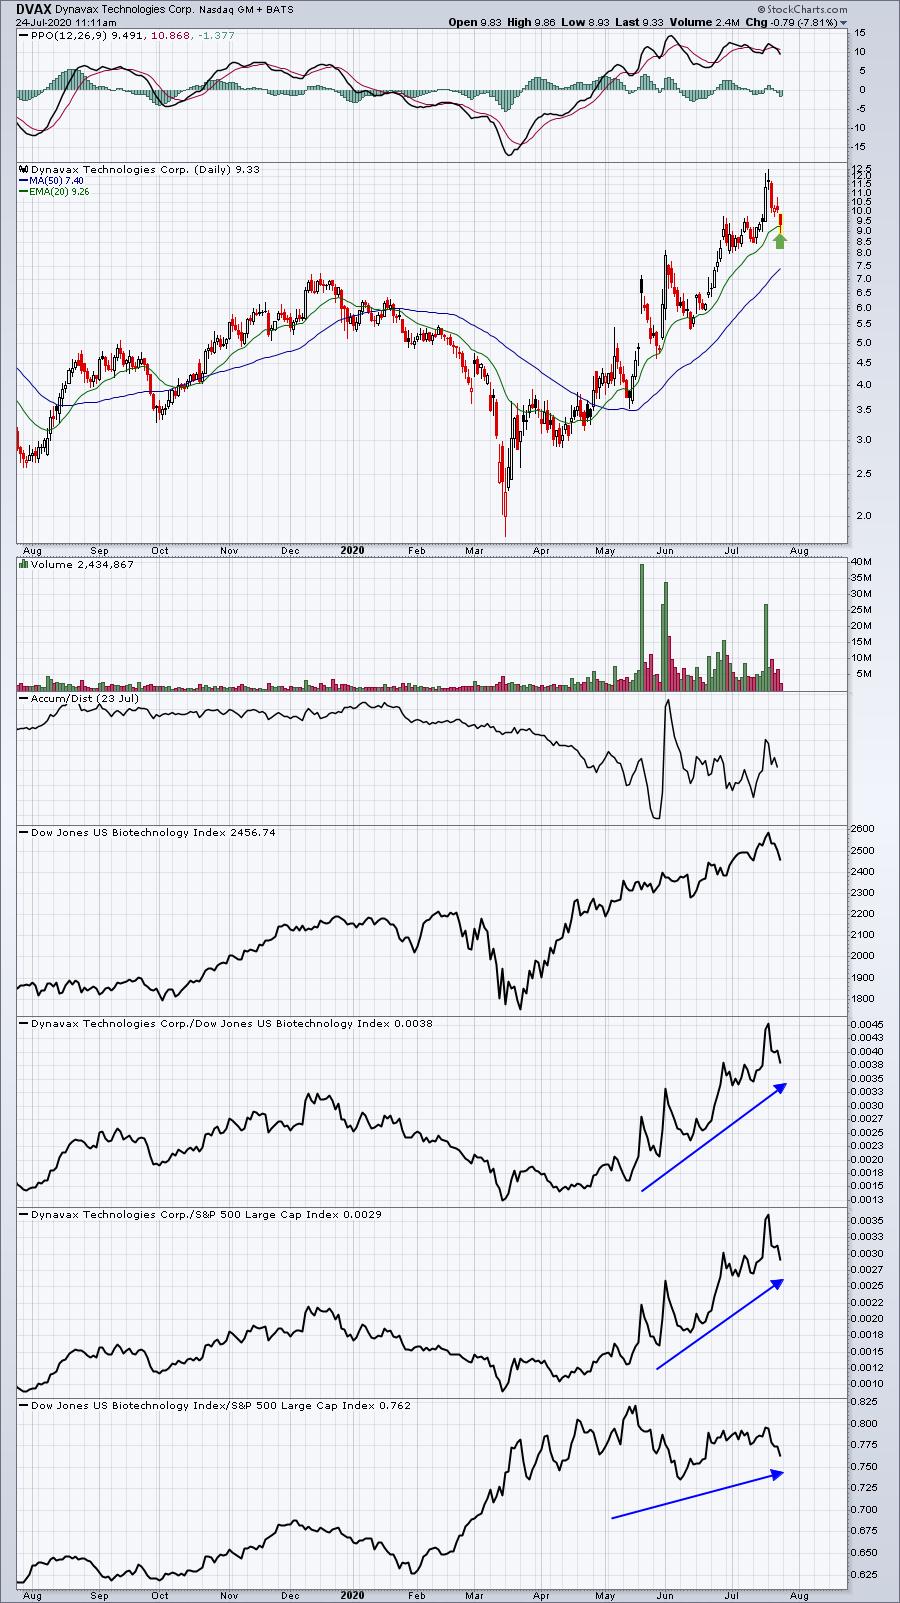
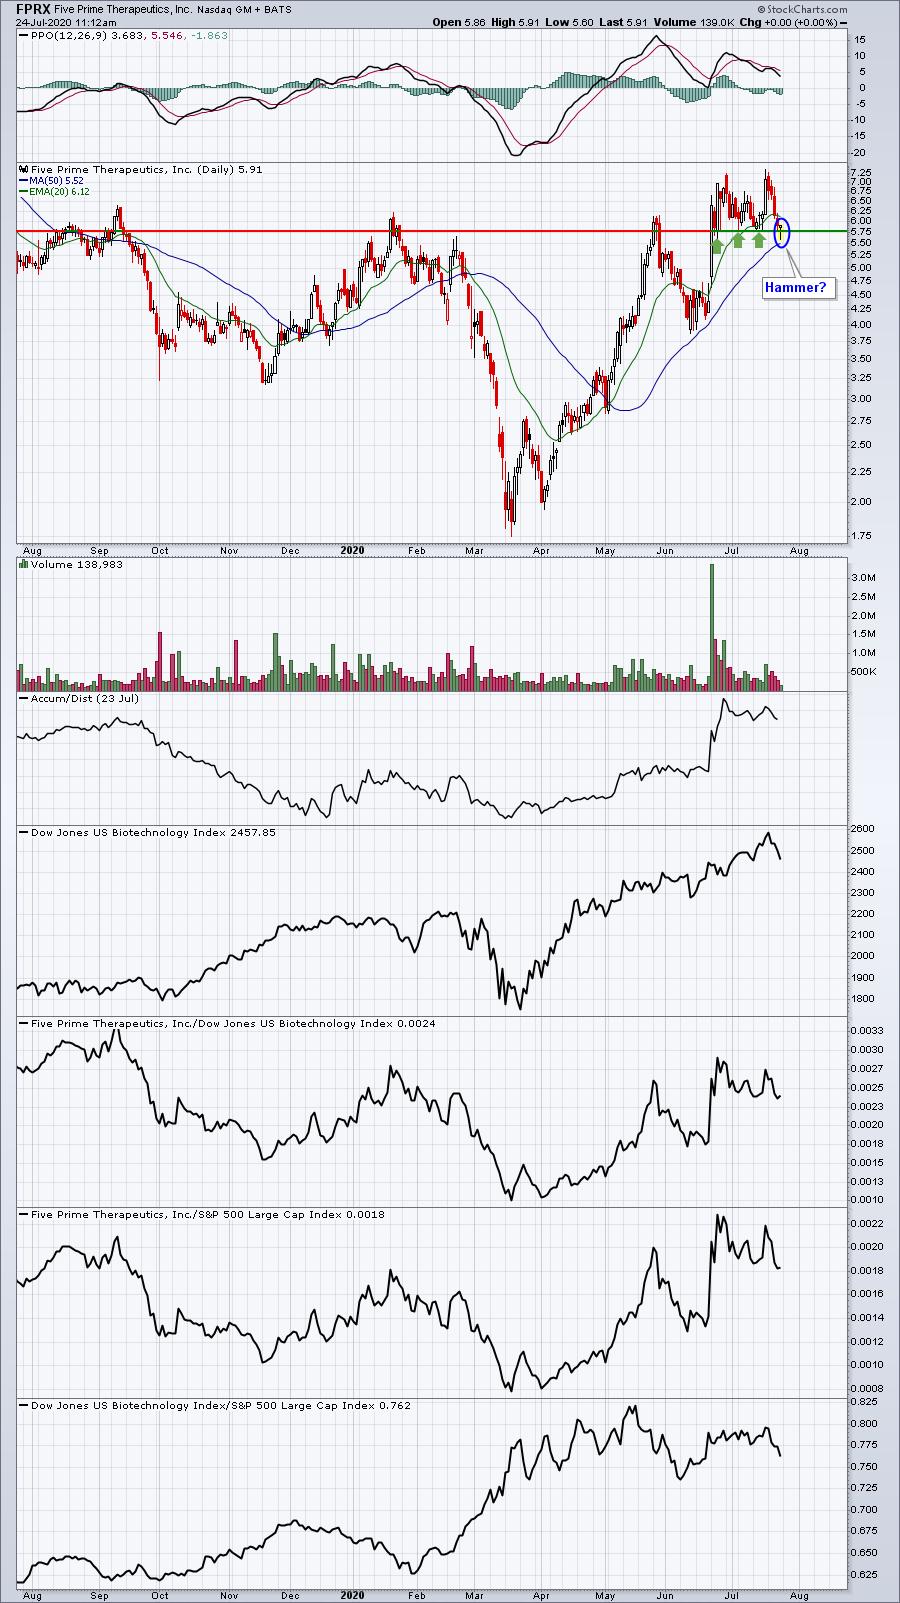
10 of the 15 worst performers have been in biotechnology. But it's quite possible that several of the above 15 stocks have simply worked off very overbought conditions. Check these out:
DVAX:
FPRX:
BLDP:
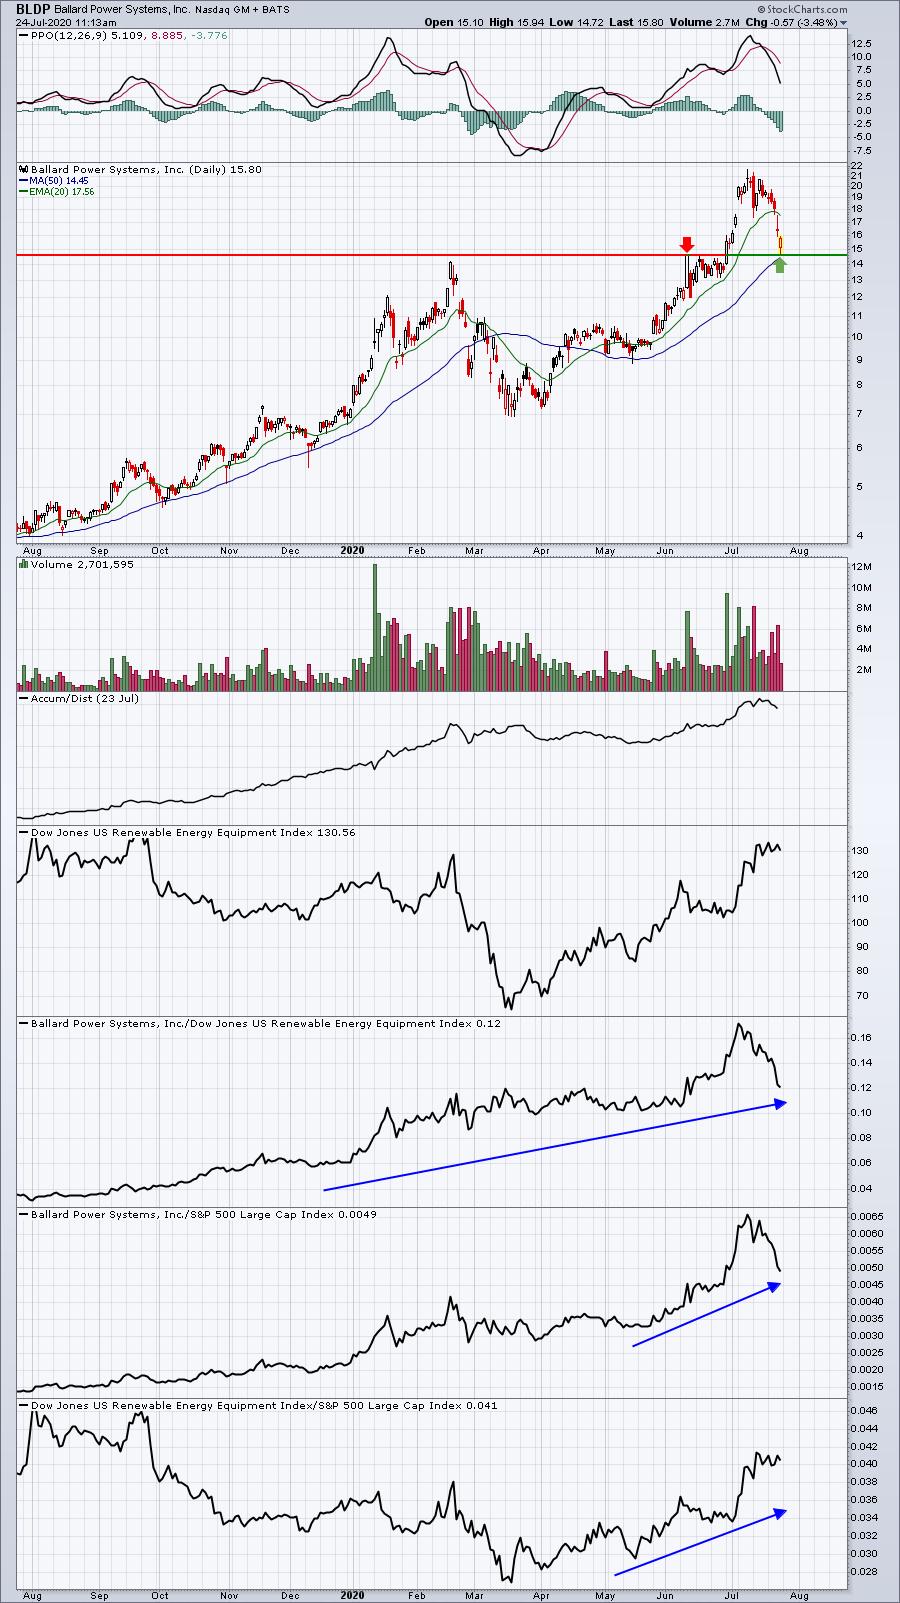
These are all very aggressive trade candidates and should only be considered by those having a very strong tolerance for risk.
Earnings Reports
Here are the key earnings reports for today and tomorrow, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks (or active trade alerts) that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning:
Friday, July 24:
VZ, NEE, HON, AXP, SLB, FMX, SHG, GNTX, CRI, TPH, BLMN
Monday, July 27:
SAP, NXPI, ARE, CINF, BRO, PFG, HAS, RPM, AVY, FFIV, UHS, LM
Economic Reports
July PMI composite flash: 50.0 (actual) vs. 50.3 (estimate)
June new home sales: 776,000 (actual) vs. 700,000 (estimate)
Happy trading!
Tom