
EB Daily Market Report - Monday, August 3, 2020
Executive Market Summary
- Futures were solid as we began a new trading day, week, and month
- The NASDAQ is showing leadership, which has been typical throughout the past 4-5 month uptrend
- Manufacturing data was mixed this morning, but both key reports showed a resumption of growth in July
- Leadership today comes from technology (XLK, +2.44%) and health care (XLV, +1.07%)
- Software ($DJUSSW, +3.59%) is surging near its July and all-time high, aiding technology, while medical supplies ($DJUSMS, +2.42%) and biotechnology ($DJUSBT, +2.28%) are lifting health care
- Defensive sectors - real estate (XLRE, -1.41%) and utilities (XLU, -1.12%) - are struggling on a relative basis
- Crude oil ($WTIC) is up 2% and is currently above $41 per barrel; gold ($GOLD) is up fractionally
- The 10 year treasury yield ($TNX) is up 3 basis points to 0.56%, at least temporarily reversing its recent downtrend
- European markets are surging today with the German DAX ($DAX) up 2.7%
Market Outlook
Well, the U.S. Dollar Index ($USD) may have printed a major bottom on Friday. It remains to be seen, but after a steady decline, a reversing bullish engulfing candle printed. If the USD falls back below that level, it would negate this signal and likely open the door much further for outperformance by materials (XLB) and possibly even energy (XLE). But should this reversal mark a bottom, then the XLB's relative outperformance may have ended. Here's an updated look at the USD and its impact on the XLB:$SPX:
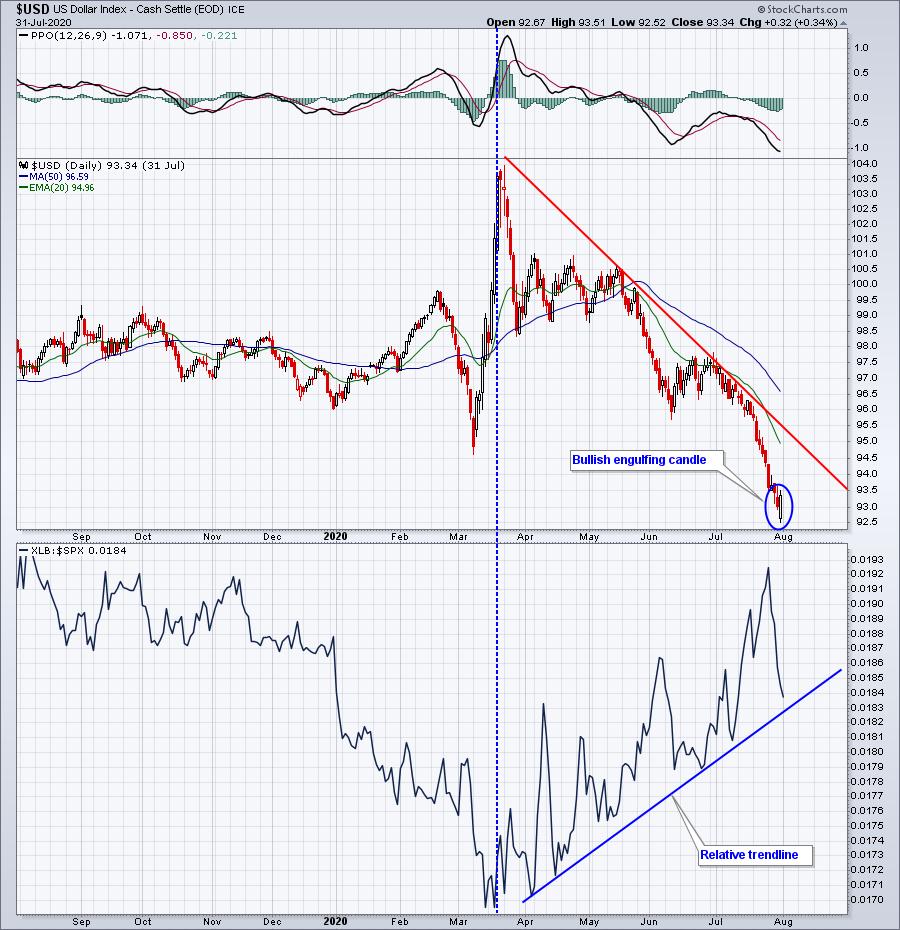
The inverse relationship between the dollar's direction and the direction of materials on a relative basis is clear.
Sector/Industry Focus
Aluminum ($DJUSAL) would likely be one of the most impacted industry groups if the U.S. Dollar Index ($USD) were to rebound and begin uptrending. You may not realize it, but the DJUSAL is the #1 industry group in terms of performance over the past month, gaining over 26%. While that is no doubt impressive, we MUST be mindful of the long-term relative picture and it's not a good one for this group:
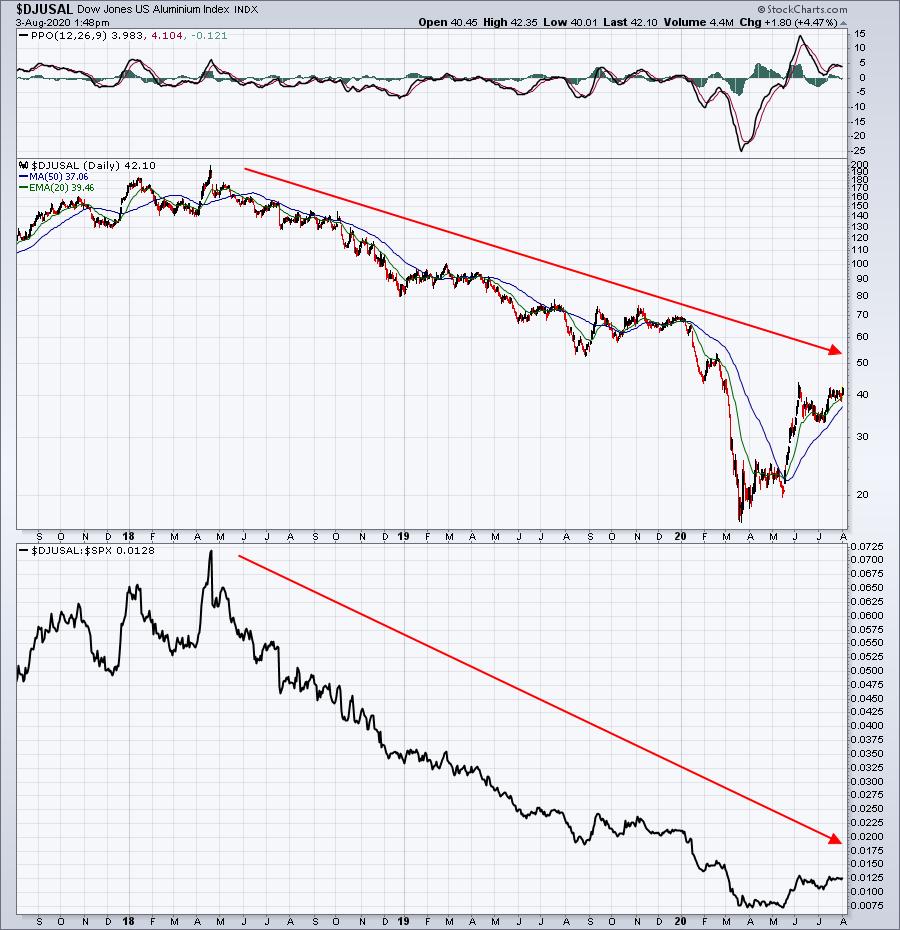
I believe the absolute and relative downtrends are fairly clear. The uptrending dollar has put severe downward pressure on many areas of basic materials over the past 9 years. Aluminum is most certainly one of those areas. The DJUSAL needs to clear 44-45 for a definitive breakout above the June high. I doubt that happens if the USD continues its 2-day rally. Keep a close eye on the dollar action because a major impact will likely be felt in materials.
ChartLists
I am in the process of updating the Strong Earnings ChartList (SECL). I hope to have it complete by tomorrow, at the latest. Here's a sneak preview of two charts, both in materials, that have been added based on last week's quarterly earnings results:
AA:
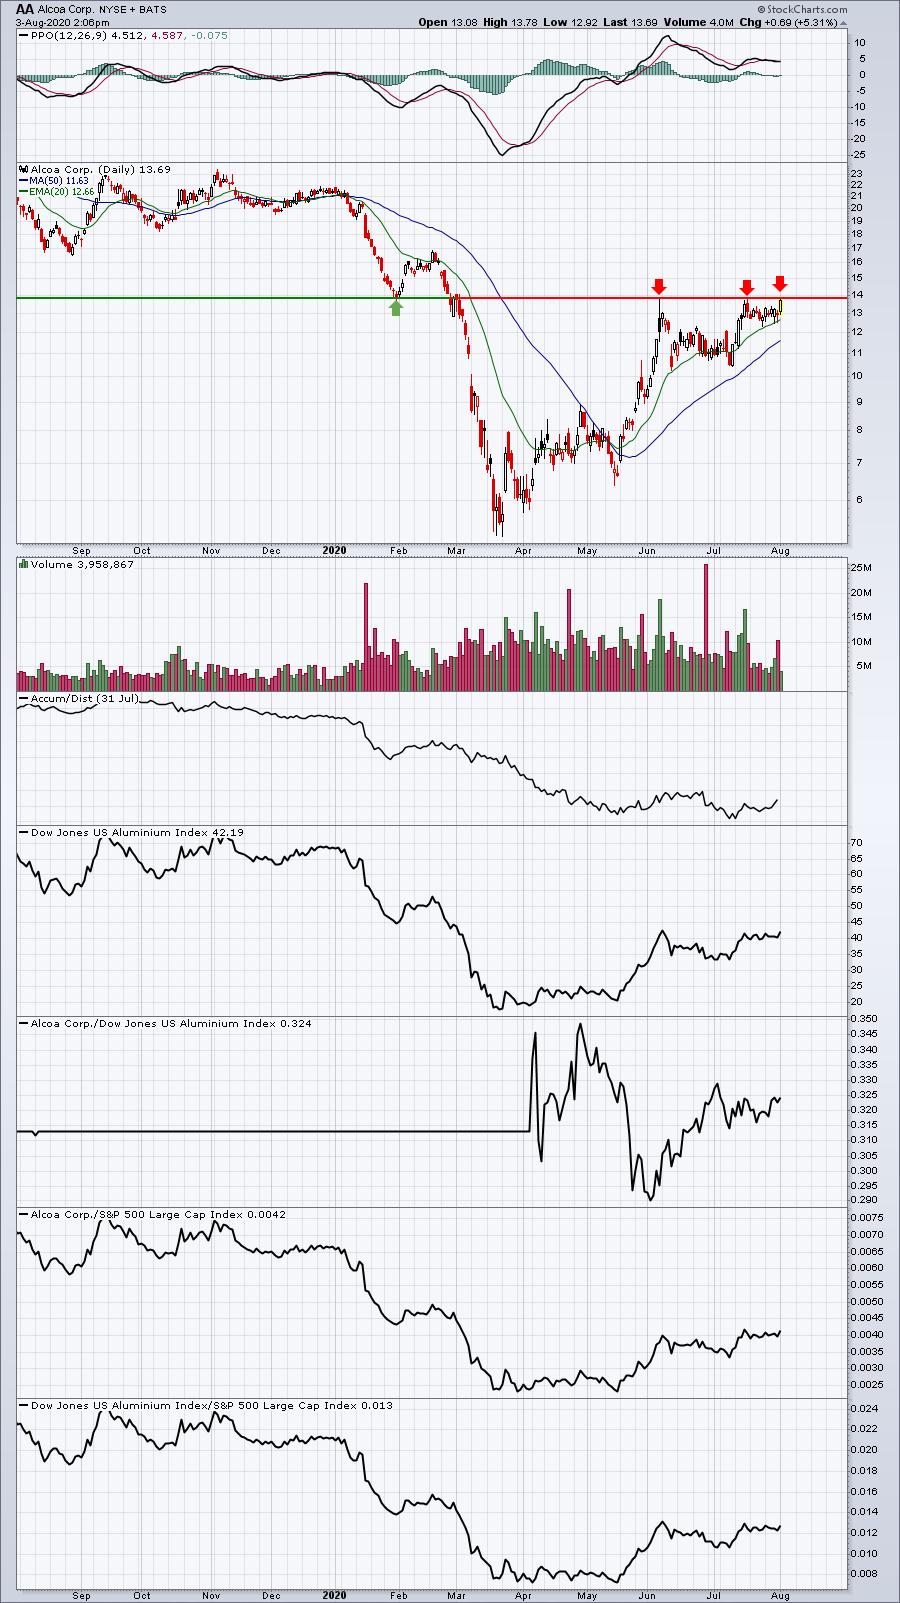
AA has a triple top, so a breakout above 15 would be extremely bullish, especially if it occurred with heavy volume AND a dollar breakdown to boot.
PPG:
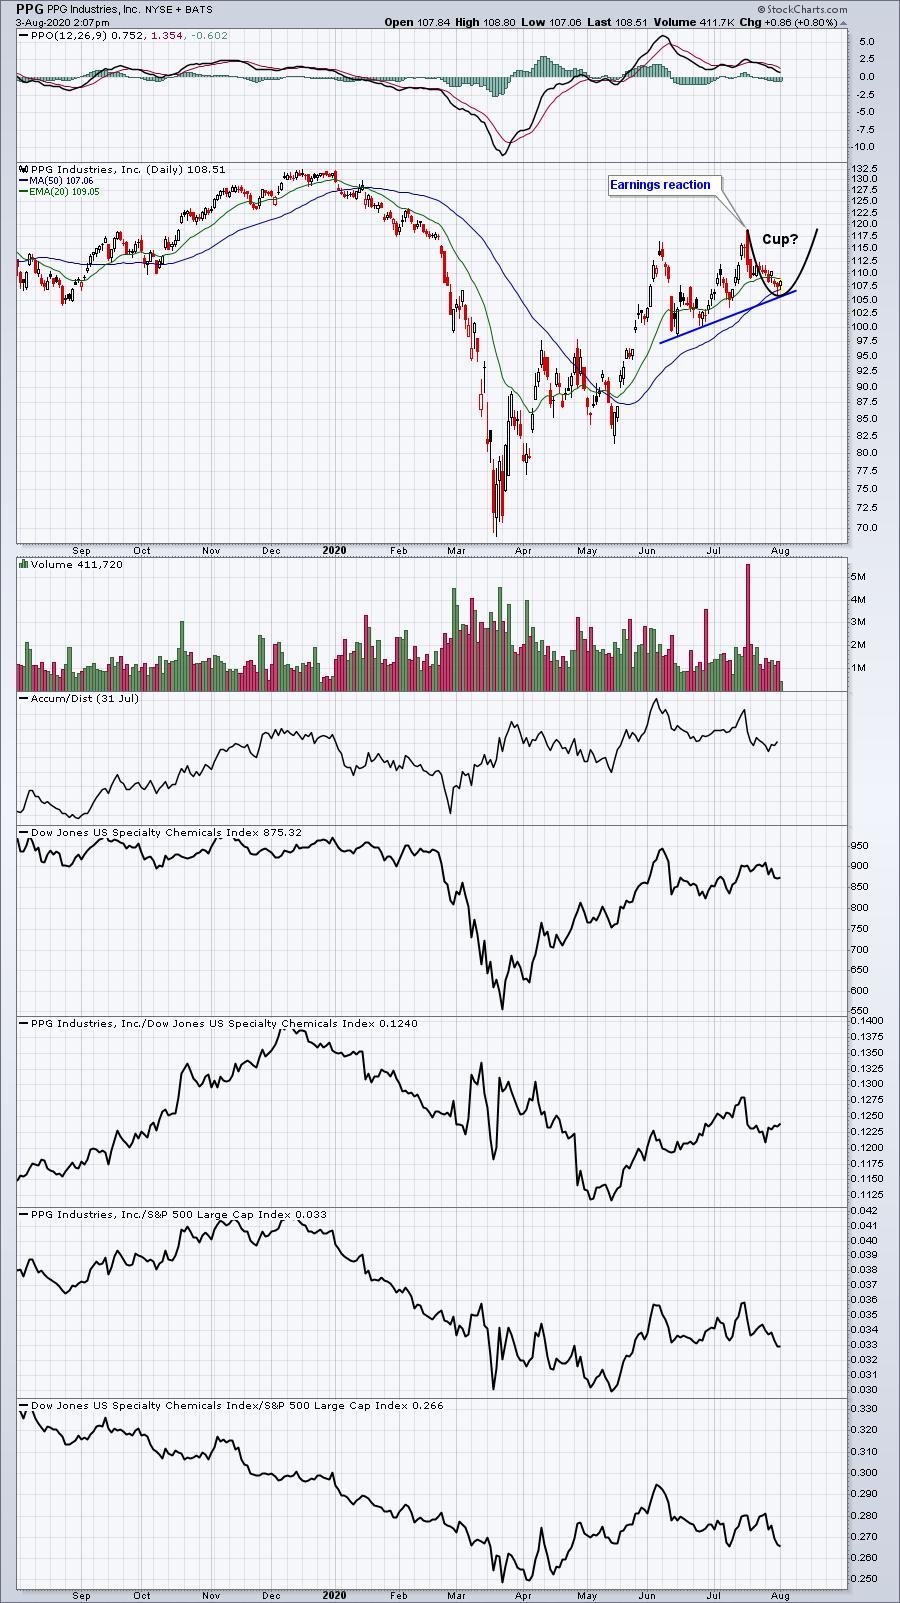
If I was in the "extremely bullish" group for materials, which I'm not (yet), I would be all over PPG. The stock opened at 118.81 after reporting stronger-than-expected quarterly results, then fell back to 105.94 on Friday, printing a hammer on its rising 50 day SMA. The reward to risk doesn't get much better than this. There's also additional price support closer to 105, so purchasing at the current price and looking to add again near 105 would reduce the risk even further. But again, I'm just not so sure the 9 year uptrend in the dollar has ended.
Earnings Reports
Here are the key earnings reports for today and tomorrow, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks (or active trade alerts) that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning:
Monday, August 3:
ITUB, GPN, SBAC, RACE, KLAC, CLX, AIG, MPC, MCK, RNG, WMB, TSN, O, MPLX, CMS, TTWO, INVH, ESS, STE, IR, J, NBIX, EMN, CNA, CHGG, SEDG, TREX, FIVN, DLB, VNO, MOS, NBL, H, SPCE, TXRH, CRUS, VRNS, MIME, THC, NSP, LGND, RRC, CTB
Tuesday, August 4:
DIS, FIS, BP, ATVI, MNST, EXC, TWLO, EMR, VRSK, WEC, ALL, ZBH, PRU, MCHP, EC, TDG, BMRN, INCY, AME, KKR, ANET, PAYC, VMC, PXD, FOXA, WMG, PEAK, EXPD, FMC, LDOS, EXR, QGEN, IT, TECH, NKLA, AVLR, PPD, WU, MTCH, WYNN, BYND, ENPH, WRK, LEA, IPHI, INGR, RL, TREE, PLNT, CYBR, ALSN, MRCY, DVN, NUVA, LGIH, LPSN, GDOT, SPR, IGT, CDLX, BMCH, GLUU, EVER, MODN, GNMK, OMI
Economic Reports
July PMI manufacturing index: 50.9 (actual) vs. 51.3 (estimate)
July ISM manufacturing index: 54.2 (actual) vs. 53.5 (estimate)
June construction spending: -0.7% (actual) vs. +1.3% (estimate)
Happy trading!
Tom