
EB Daily Market Report - Friday, August 21, 2020
Executive Market Summary
- Futures were slightly lower this morning, but all of our major indices are now higher, led by the Dow Jones
- Mid caps ($MID) and small caps ($SML), however, are not participating in this rally
- Deere & Co (DE) reported excellent results as I expected based on their recent absolute and relative strength, and DE is the top performing S&P 500 stock today
- Apple (AAPL) continues to soar, up another 5% today, leading technology (XLK) higher
- Automobiles ($DJUSAU) and home construction ($DJUSHB), two major leaders among consumer discretionary, are rising solidly again today
- The 10 year treasury yield ($TNX) is flat, along with most commodities
- The U.S. Dollar (UUP) was up earlier, tested its 20 day EMA, but has since backed off; there is a positive divergence on the UUP that could lead to a further short-term advance
Market Outlook
One of the biggest changes in our Portfolio selection process this quarter was the doubling of consumer discretionary (XLY) names - from 7 to 14 - among our 40 portfolio stocks (actually 39 since AAPL is in both our Model and Income portfolios). It's very hard to argue with this change given the superb relative strength being shown by the sector currently:
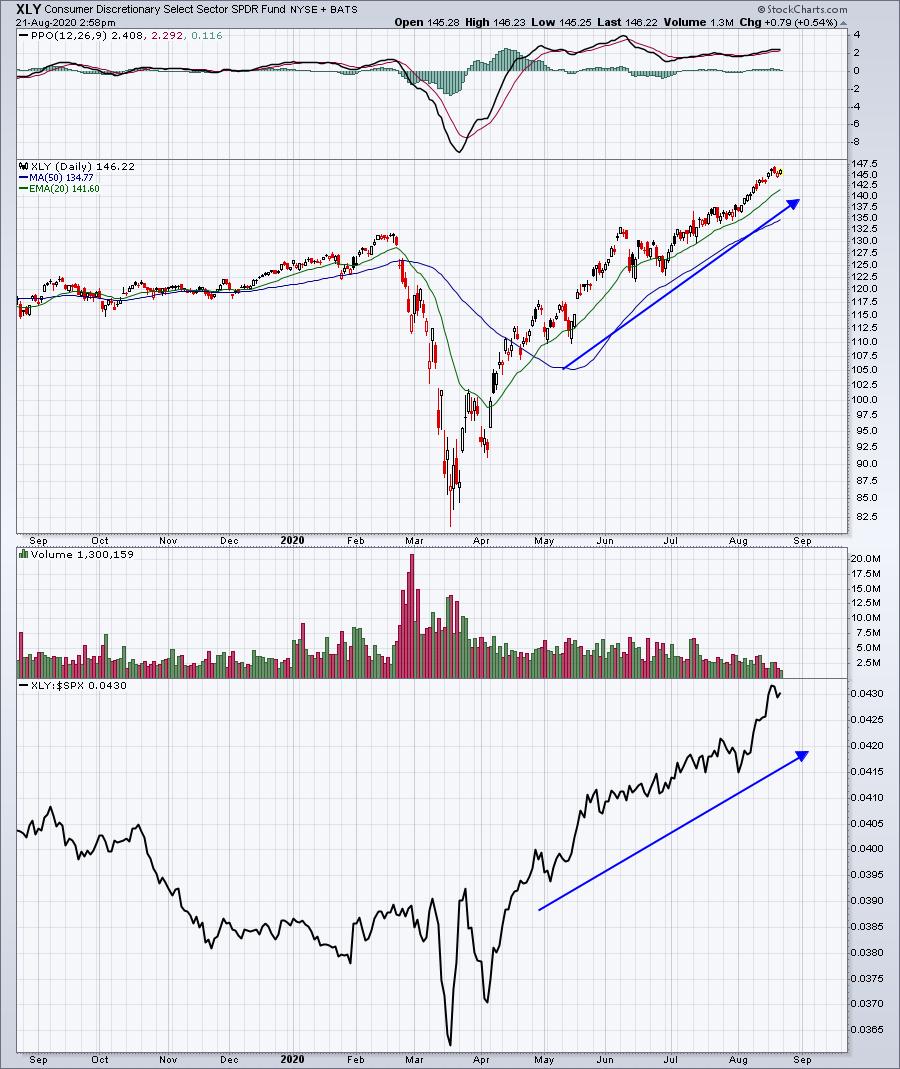
If we're trying to outperform the S&P 500 by following the current strength in the market, I'd say that consumer discretionary MUST have a very strong representation. That's why we added so many this quarter.
Sector/Industry Focus
Footwear ($DJUSFT), after sideways consolidating for months, has finally broken out:
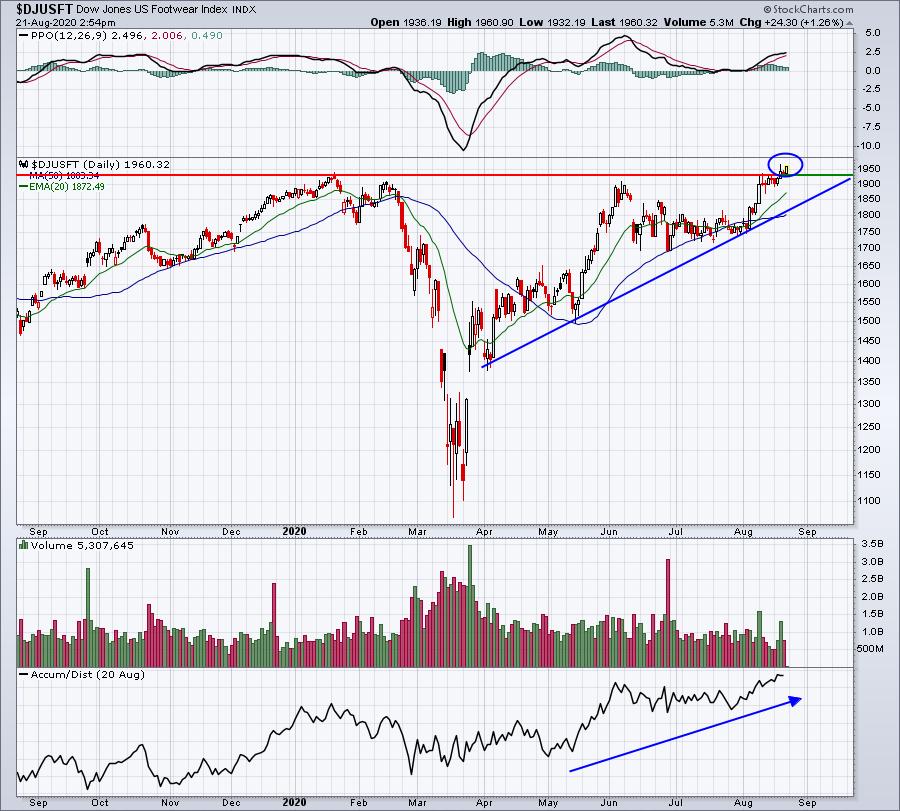
The DJUSFT is simply the latest industry group within the consumer discretionary sector (XLY) to break out. I suspect we'll continue to see solid performance in this space now on an absolute basis, but there's still more work to do before the group breaks out relative to the S&P 500.
ChartLists
We've seen many companies make a surge in the 2-3 weeks before they report earnings. So one strategy to consider, especially for more aggressive traders, is to look ahead at which companies will be reporting quarterly results over the next few weeks and see if they're current industry leaders (or if they've recently been an industry leader). Many of these companies will be bid higher into their quarterly reports. As I look ahead to the earnings calendar in early September, here are a few companies on our Strong Earnings ChartList (SECL) that could see a pre-earnings push higher:
ZM (reports Aug 31st):
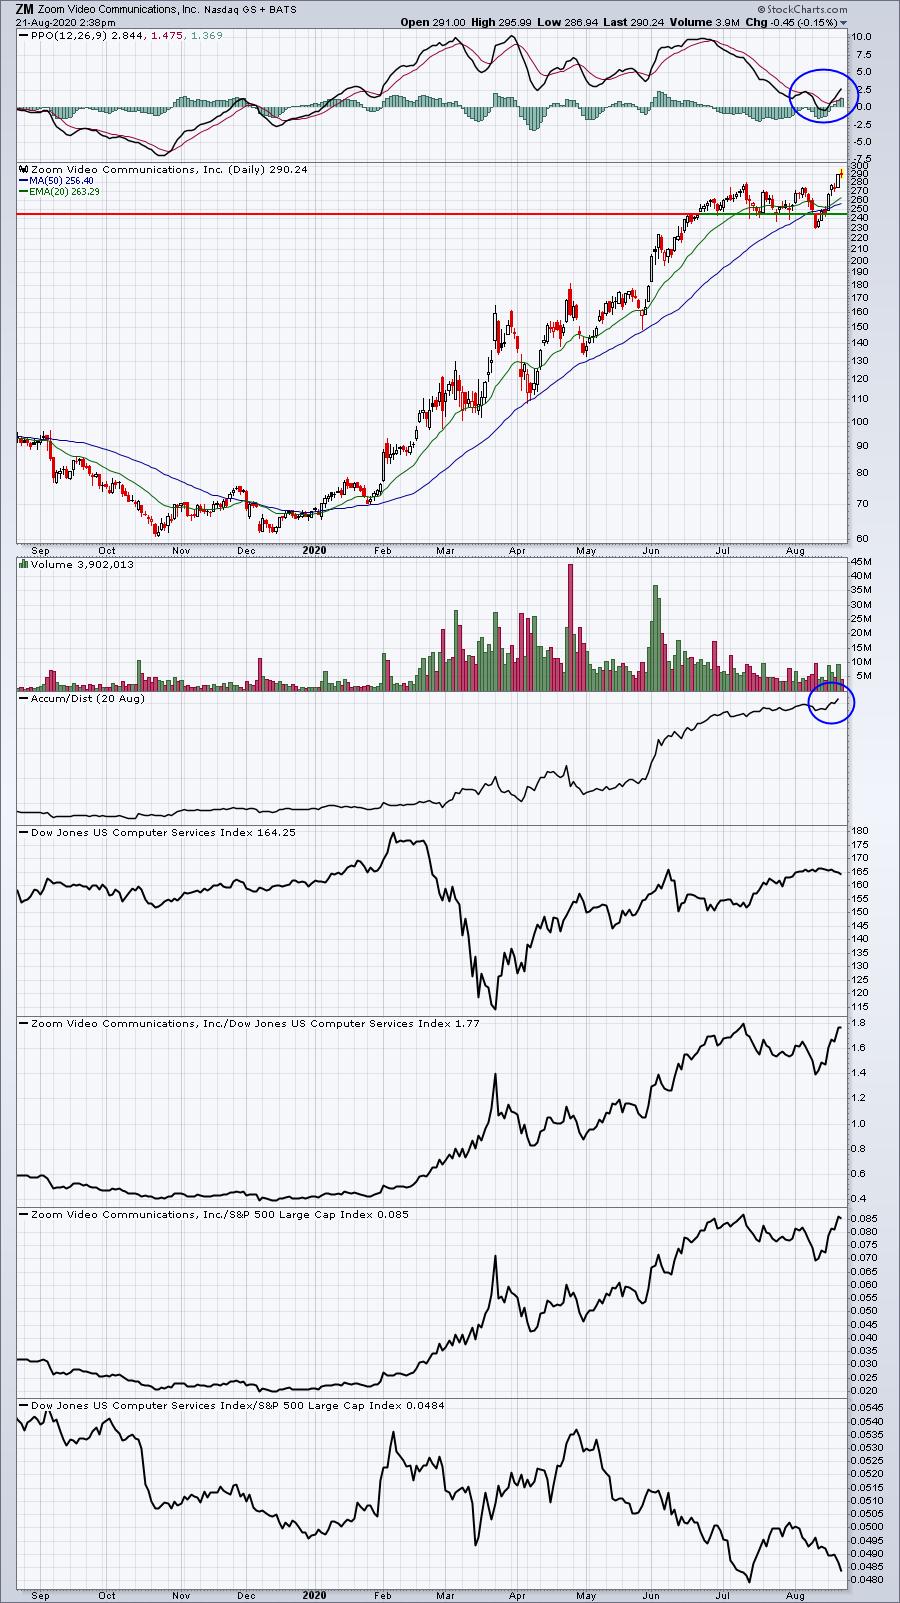
ZM appears to be on its way higher ahead of its earnings report, due out in 10 days. It's not at all unusual to see a false breakdown beneath key short-term support before a move higher as it enables market makers to build inventory from traders stopped out on the breakdown.
CRWD (reports Sept 2nd):
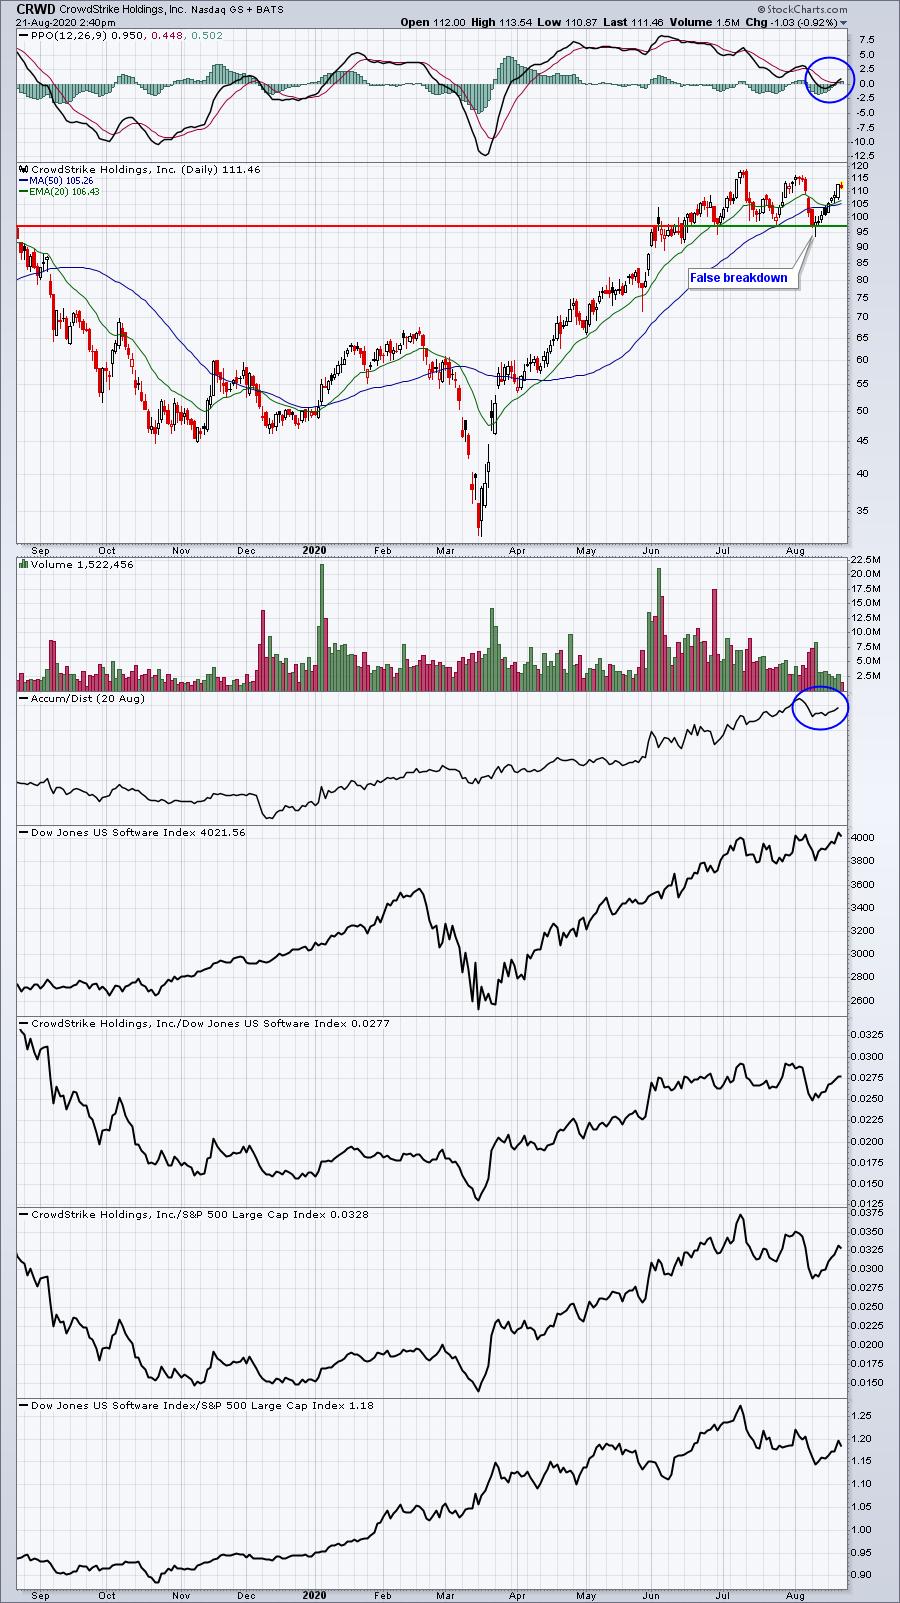
After a recent false breakdown, CRWD is starting to run ahead of earnings. I believe CRWD was mentioned here in the DMR several days ago when I revealed it from our Downtrend Reversal scan.
MDB (reports Sept 2nd):
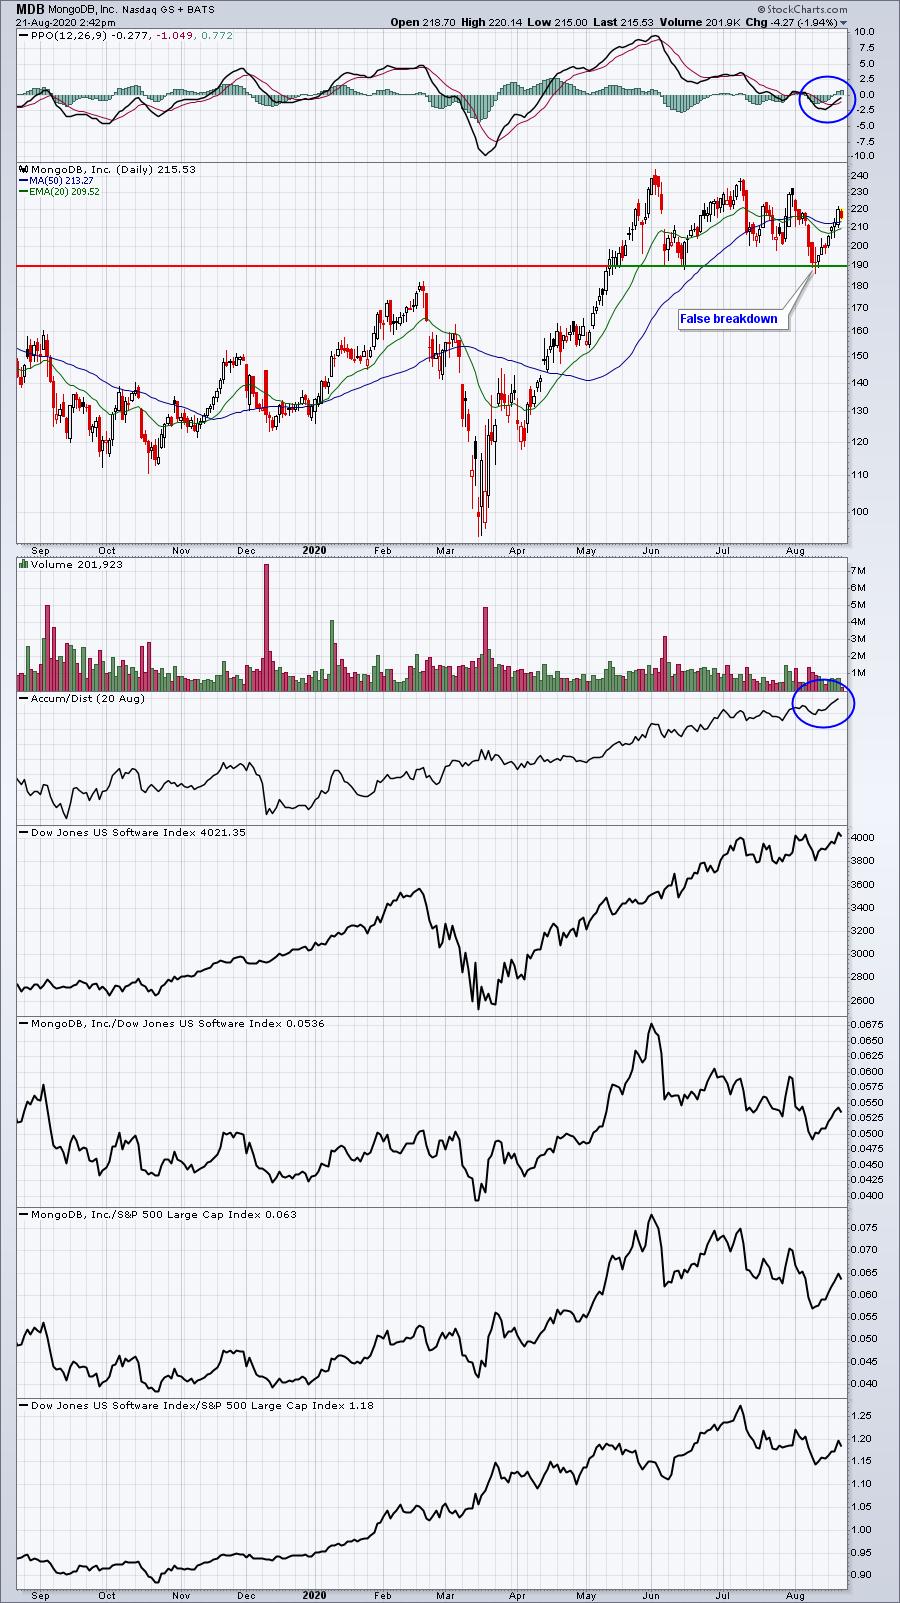
I'm circling the PPOs and AD lines on these charts because they're all quite similar. Despite the recent weakness and false breakdowns, note the AD lines are generally moving higher again. Also, PPO breaks beneath centerline support don't seem to last very long.
CLDR (reports Sept 2nd):
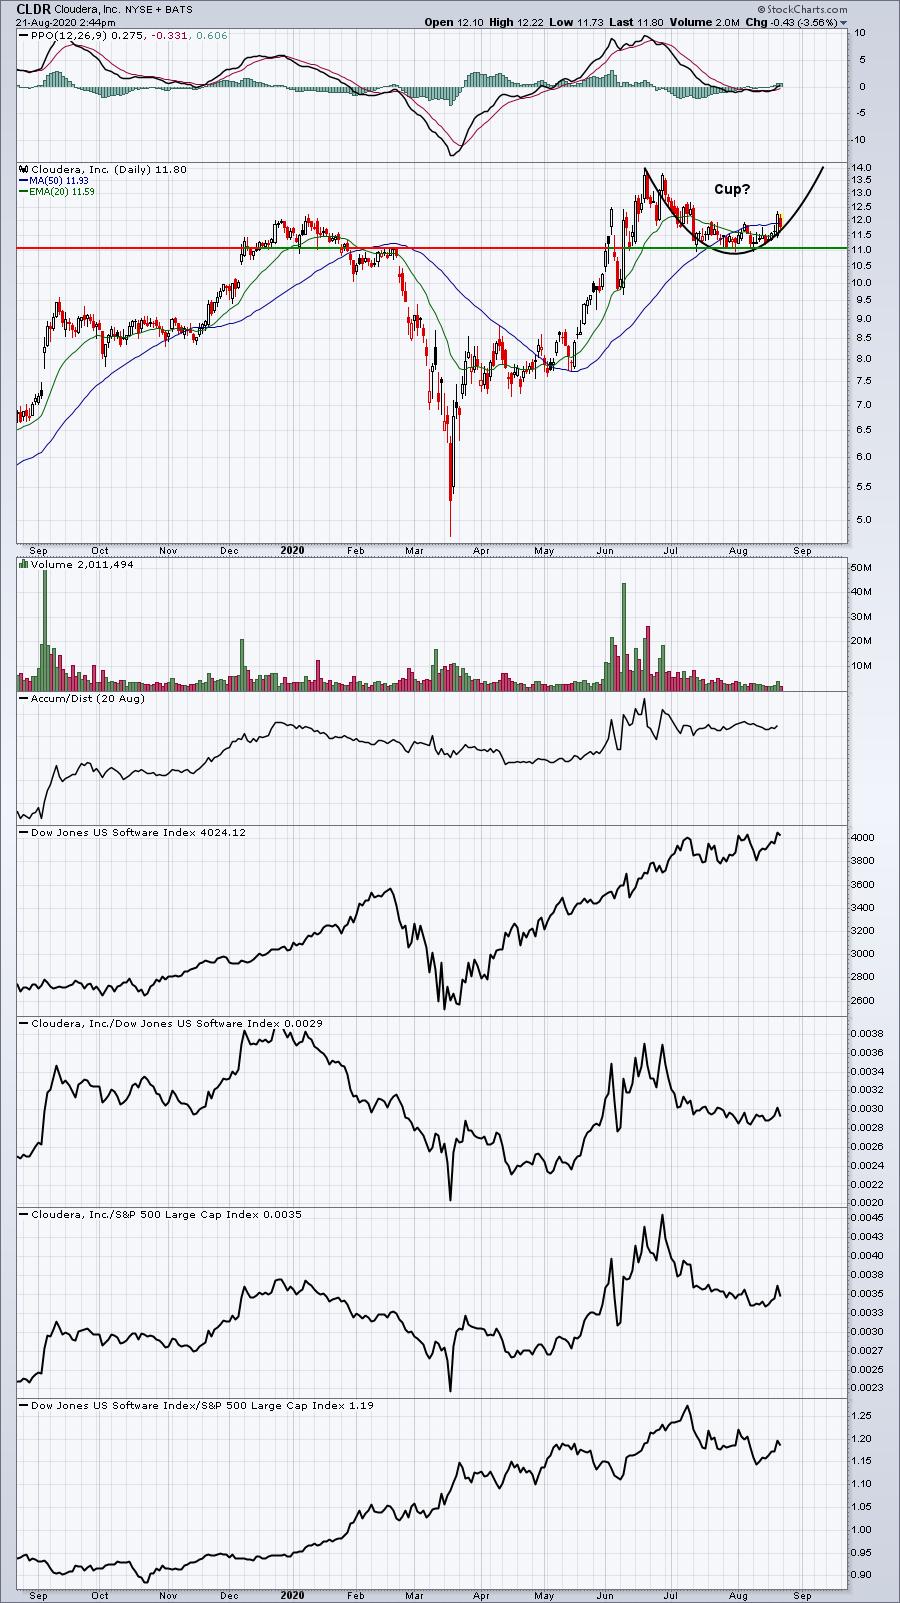
CLDR seems to be printing a rounded bottom. The right side of a potential cup could form. Keep a close eye on price support near 11.00. I'd have a stop in play on any close beneath that level.
Earnings Reports
Here are the key earnings reports for today and tomorrow, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Friday, August 21:
PDD, DE, FL
Monday, August 24:
PANW
Economic Reports
August PMI composite flash: 54.7 (actual) vs. 51.3 (estimate)
July existing home sales: 5,860,000 (actual) vs. 5,400,000 (estimate)
Happy trading!
Tom