
EB Daily Market Report - Thursday, September 10, 2020
Executive Market Summary
- Futures were strong across all our major indices
- Selling, however, has taken over as all key indices are lower as of this writing
- The failure at 20 day EMAs could be the start of a "C" leg lower in an ABC correction
- Energy (XLE, -3.16%) and technology (XLK, -2.40%) are the lagging sectors
- All 11 sectors are lower, but materials (XLB, -0.74%) lead on a relative basis
- Energy names are all over the S&P 500 worst performers
- The Dow Jones is being led lower by AAPL and MSFT
- Renewable energy ($DWCREE, -5.02%) and computer hardware ($DJUSCR, -3.77%) are lagging industries today
Market Outlook
Transports ($TRAN) did open September with a breakout above the January 2020 high, which adds to previous bullish signals that I've discussed. Furthermore, after breaking out, the group has fallen back to test its rising 20 day EMA and is currently bouncing:
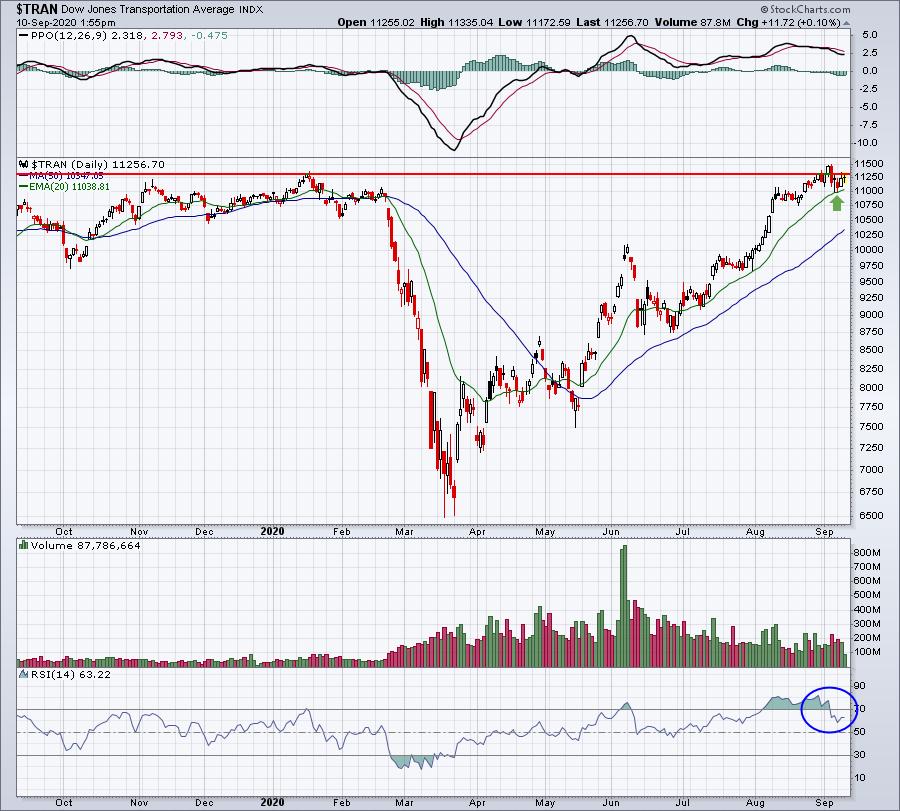
The recent selling enabled the RSI to fall back from overbought to a more manageable level just below 60. The rising 20 day EMA has been holding successfully as support the past couple months. In addition, railroads ($DJUSRR) have been strengthening on both an absolute and relative basis, adding to the more bullish bias among transports.
Sector/Industry Focus
Railroads ($DJUSRR) are trending above their rising 20 day EMA and they're moving closer and closer to a key relative breakout vs. the benchmark S&P 500:
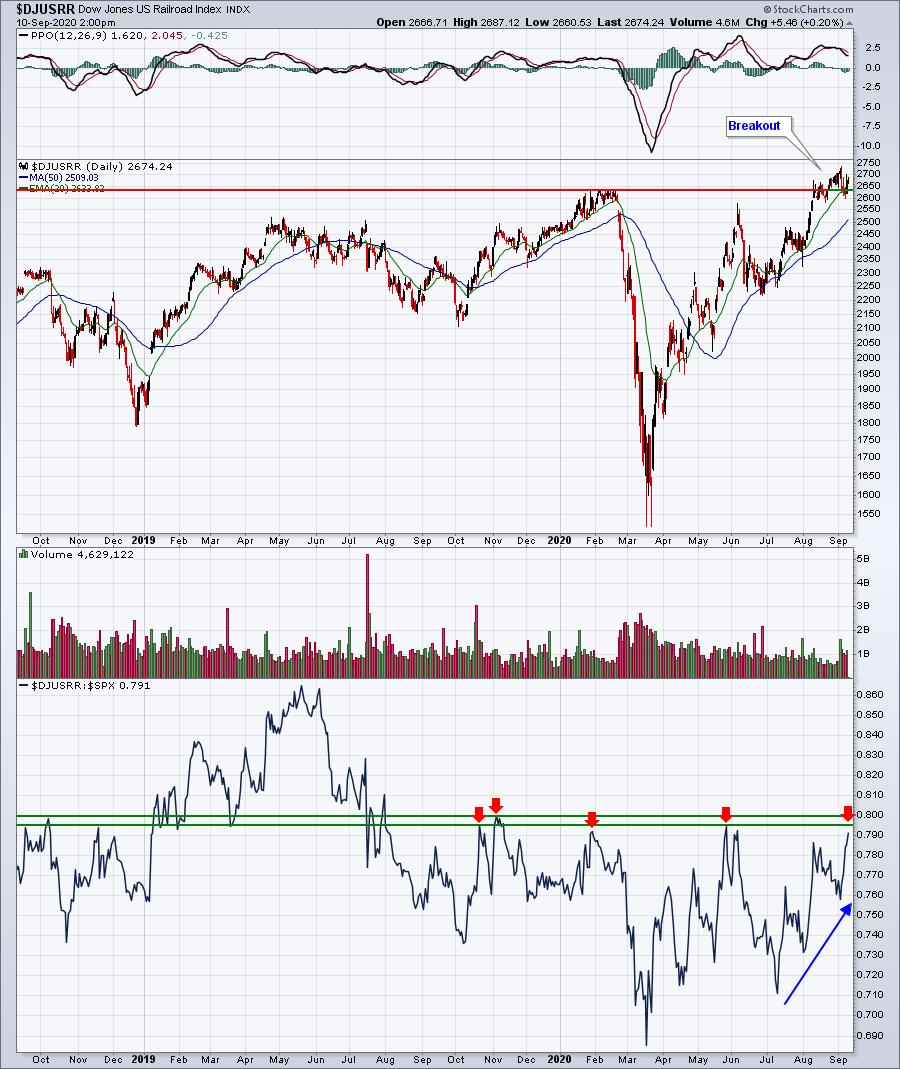
Railroads are definitely strengthening, but what I'd really like to see is that relative breakout. That'll give us the signal that money is rotating heavily toward the group.
ChartLists
I think it's prudent to watch the action into the close today. We could be starting the "C" in an ABC correction. Failure at the rising 20 day EMA leaves me skeptical of this current rally. To further illustrate, here's a current chart of the NASDAQ 100 ($NDX):
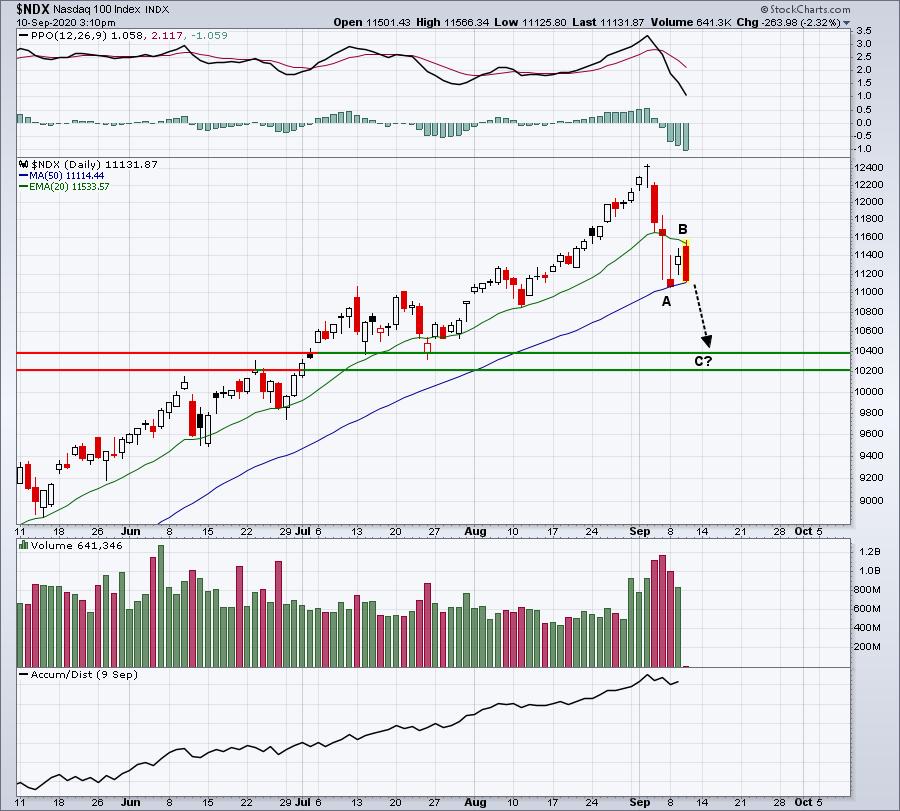
Let's watch the action into the close as I suspect we'll have better trading opportunities later this month.
Earnings Reports
Here are the key earnings reports for today and tomorrow, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, September 10:
ORCL, CHWY, PTON
Friday, September 11:
KR
Economic Reports
Initial jobless claims: 884,000 (actual) vs. 828,000 (estimate)
August PPI: +0.3% (actual) vs. +0.2% (estimate)
August Core PPI: +0.4% (actual) vs. +0.2% (estimate)
July wholesale inventories: -0.3% (actual) vs. -0.1% (estimate)
Happy trading!
Tom