
EB Daily Market Report - Thursday, October 1, 2020
Executive Market Summary
- Futures pointed to a very strong open this morning; traders will anxiously be awaiting tomorrow's nonfarm payrolls
- Currently, all major indices are gaining ground, led by the NASDAQ 100 ($NDX)
- Consumer discretionary (XLY, +1.36%) and communication services (XLC, +1.26%), two aggressive sectors, are today's leaders
- Automobiles ($DJUSAU, +3.43%) have reclaimed the top spot among discretionary stocks
- Media agencies ($DJUSAV, +2.19%) are leading communication services groups; it's approaching major closing resistance of 505.53 - a breakout would be very bullish for the group
- Bed Bath & Beyond (BBBY, +33.21%) is surging higher after posting excellent quarterly results, forcing shorts to cover
- Many retail stocks (XRT, +2.50%) are higher today
- Etsy, Inc. (ETSY, +7.63%), one of our Aggressive Portfolio stocks, is atop the S&P 500 leaderboard
Market Outlook
Well, it's Q4 time! Historically, this is the best calendar quarter for the S&P 500 since 1950. Over the past two decades, one of the best bets has been the QQQ (ETF tracking the NASDAQ 100) outperforming the SPY (ETF tracking the S&P 500) during the month of October. Here's the seasonality chart for confirmation of this relative strength:
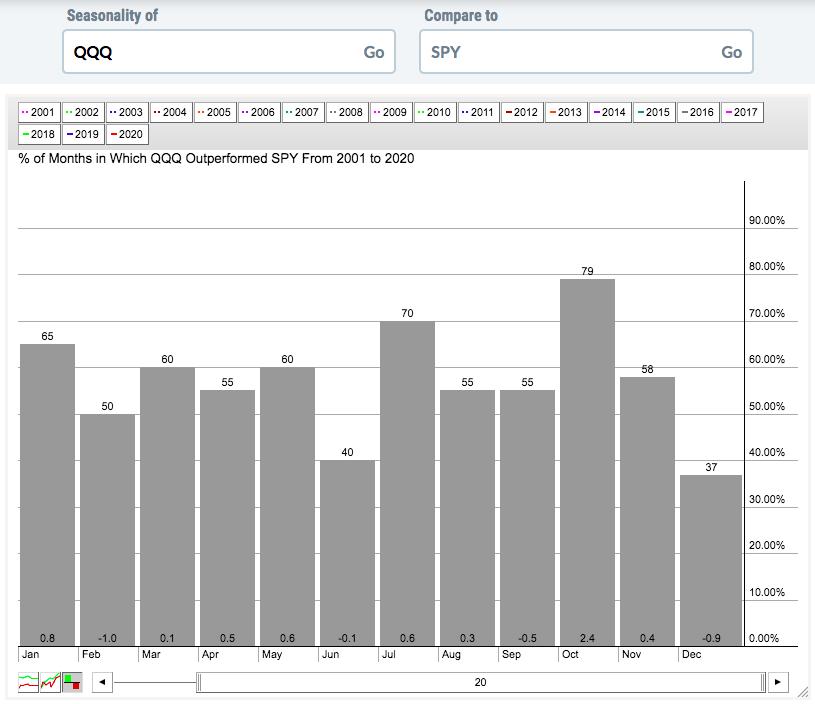
The QQQ has outperformed the SPY in 79% of Octobers since the turn of the century. That gives us, at least historically, about a 4 in 5 chance that the QQQ will continue its 2020 dominance of the SPY through October.
Furthermore, we favor growth stocks (IWF) over value stocks (IWD), and the following seasonality chart also favors growth stocks in October:
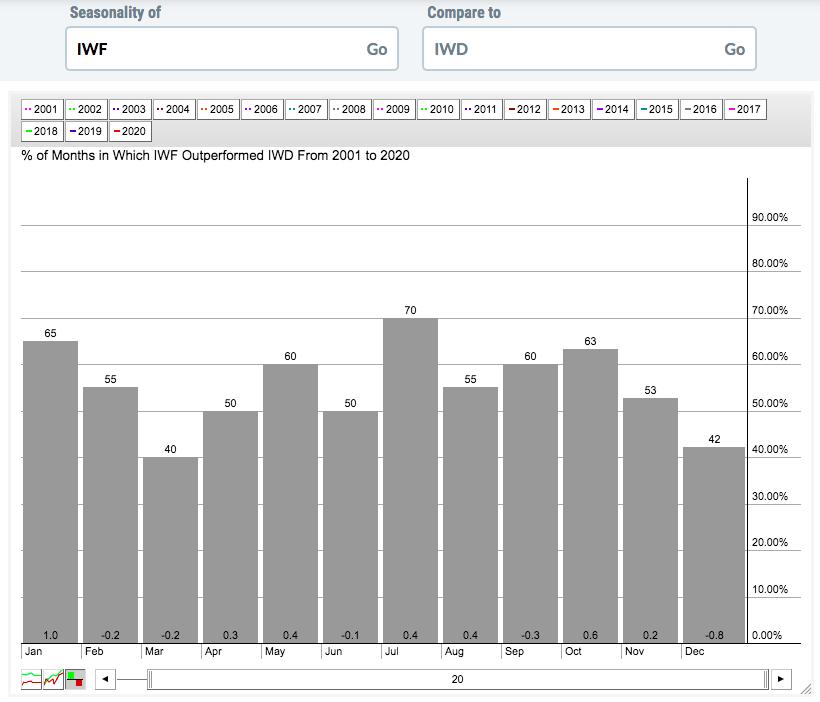
While the odds of October outperformance has been 63% the past two decades, October trails only January in terms of the average outperformance (+0.6%). History favors the NASDAQ 100 and growth stocks and that's what's been leading us throughout this pandemic in 2020.
Sector/Industry Focus
Let's take the seasonality charts in October one step further and compare technology (XLK) to the S&P 500. Over the past 20 years, this is how technology stacks up:
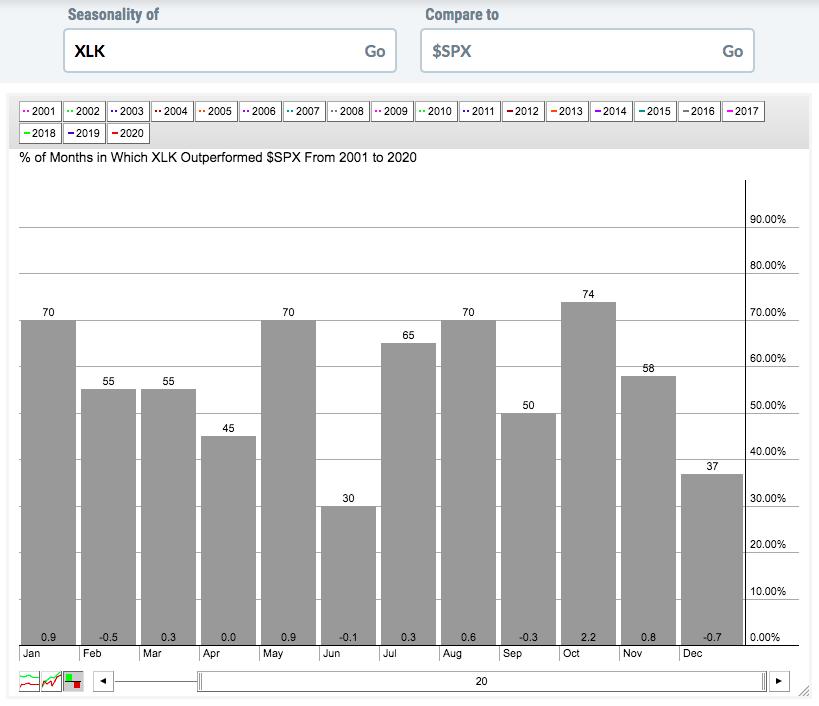
Not only does the XLK outperform the S&P 500 roughly three-quarters of all Octobers, but the average outperformance also is staggering. The average outperformance of technology in October is an astounding 2.2%, more than double any other calendar month throughout the year. These historical facts seem to corroborate my belief that growth stocks will lead U.S. equity prices higher in Q4 and technology should be a relative leader once again.
ChartLists/Strategies
I wanted to stick with the high volume theme from yesterday, but this time I ran a high volume scan against all of our ChartLists. Here was the scan syntax:
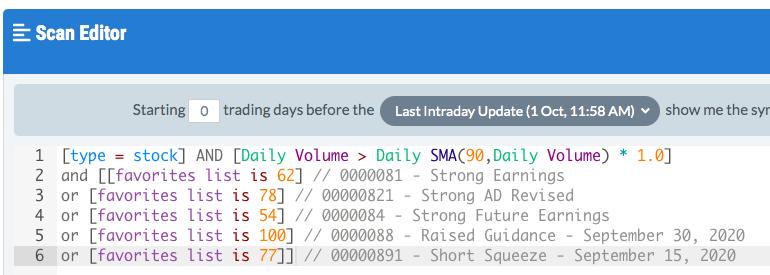
....and the results:
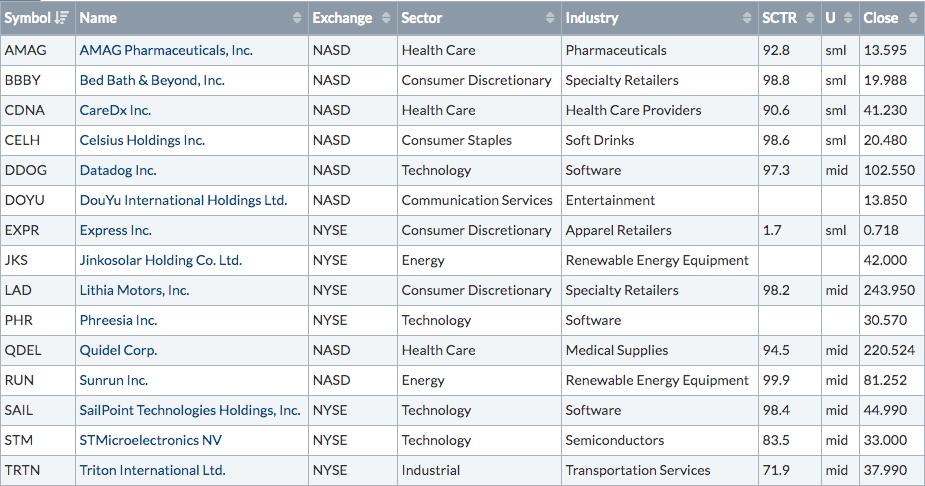
Three of these stocks are worth mentioning:
BBBY:
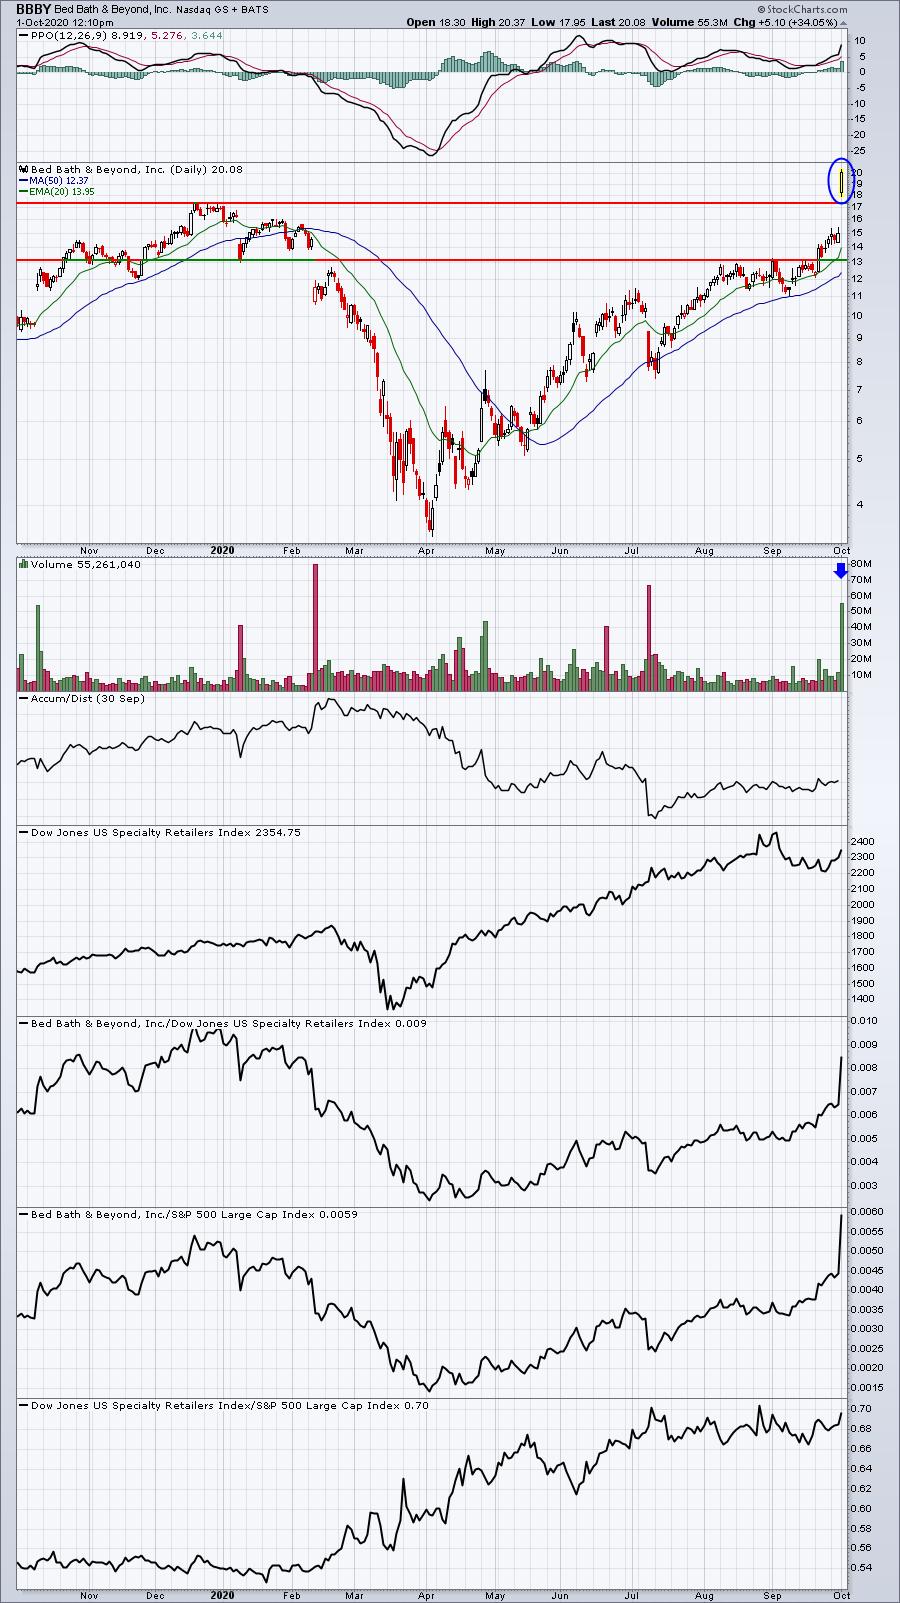
BBBY is currently a member of our Strong Future Earnings ChartList (SFECL) and our Short Squeeze ChartList (SSCL). I think it's safe to say that there are a lot of nervous short sellers dealing with a 34% surge in BBBY shares after the specialty retailer posted its latest quarterly results that CRUSHED Wall Street estimates. BBBY posted EPS of .50, well ahead of the loss that was forecast of (.29). Revenues also topped expectations. As of two weeks ago, BBBY was reported to have 61.05% of its float short. That's a lot of short sellers that need to cover (buy) the stock. I wouldn't be surprised to see a continuing melt up in BBBY shares short-term as a result.
CDNA:
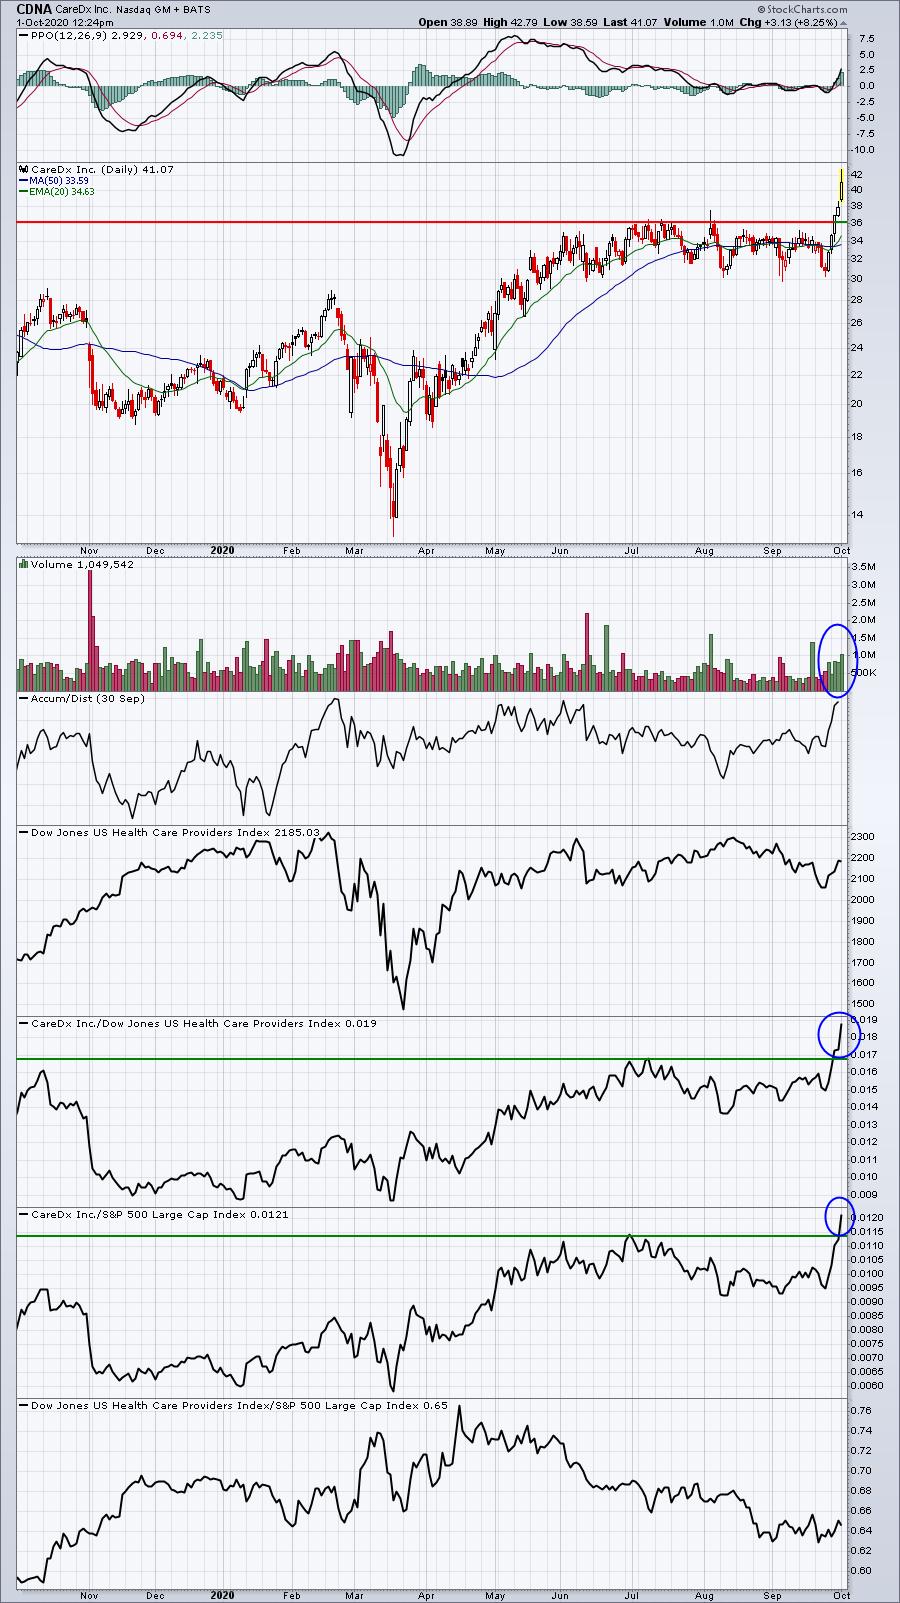
CDNA is currently a member of our Strong Earnings ChartList. The breakout here is obvious, as is the heavy volume confirmation. CDNA has broken out vs. its health care provider ($DJUSHP) peers and its AD line is on the verge of breaking out as well. While I believe chasing this breakout is dangerous short-term, any pullback to test either the rising 20 day EMA or the breakout level near 36 would represent excellent entry.
STM:
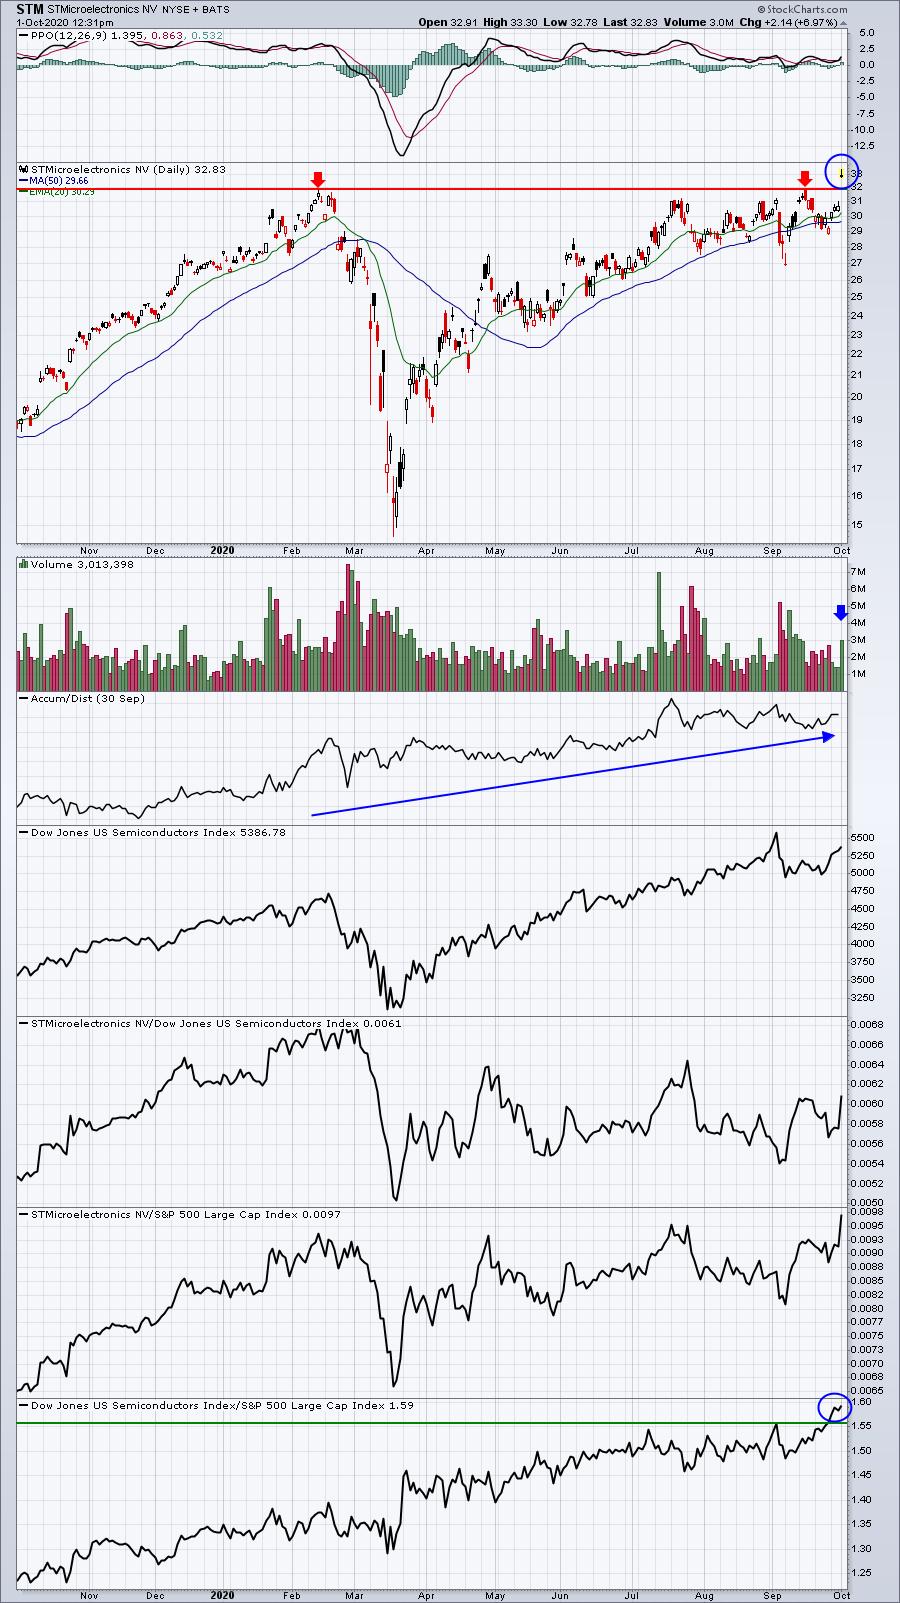
STM is currently a member of our Raised Guidance ChartList (RGCL) and our Strong AD ChartList (SADCL). The company will report its latest quarterly results in 3 weeks on 10/22 before the market opens. This morning, however, they pre-announced that both Q3 revenues and FY20 revenues will be above expectations, leading to the breakout. Volume is heavy, confirming the breakout, and STM resides in a strengthening semiconductors group ($DJUSSC). The only downside here is that STM's relative performance to its semiconductor peers is average at best.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, October 1:
PEP, STZ, CAG, BBBY
Friday, October 2:
None
Economic Reports
Initial jobless claims: 837,000 (actual) vs. 850,000 (estimate)
August personal income: -2.7% (actual) vs. -2.5% (estimate)
August personal spending: +1.0% (actual) vs. +0.8% (estimate)
September PMI manufacturing: 53.1 (actual) vs. 53.5 (estimate)
September ISM manufacturing: 55.4 (actual) vs. 56.3 (estimate)
August construction spending: +1.4% (actual) vs. +0.7% (estimate)
Happy trading!
Tom