
EB Daily Market Report - Monday, October 19, 2020
Draft Day - Model ETF Portfolio
At 4:30pm ET today, I'll announce the ETFs that will comprise our Model ETF Portfolio. I hope you can join me! If not, we'll have the entire webinar recorded. Here's the link to the room (which should open at 4:00pm ET):
https://us02web.zoom.us/j/84065769624
Executive Market Summary
- Futures pointed higher to open the week
- Our major indices are mostly lower, led by a 0.44% drop in the S&P 500
- Small caps ($SML) are clinging to a small gain
- Stimulus talks are still on the table, but time seems to be ticking down, and this could be a short-term driver for U.S. equities
- Renewable energy ($DWCREE, +1.96%)
- Consumer discretionary (XLY, +0.02%) is the only sector in positive territory
- Communication services (XLC, -0.82%) and financials (XLF, -0.66%) are the two worst sectors today
- Companies on deck for earnings after the close include IBM, Cadence Design (CDNS), PPG Industries (PPG), and Logitech (LOGI); Wall Street is expecting solid reports from CDNS and LOGI, in my opinion
Market Outlook
The NASDAQ 100 ($NDX) is once again challenging gap support and recent price lows, which can be seen on an hourly chart as follows:
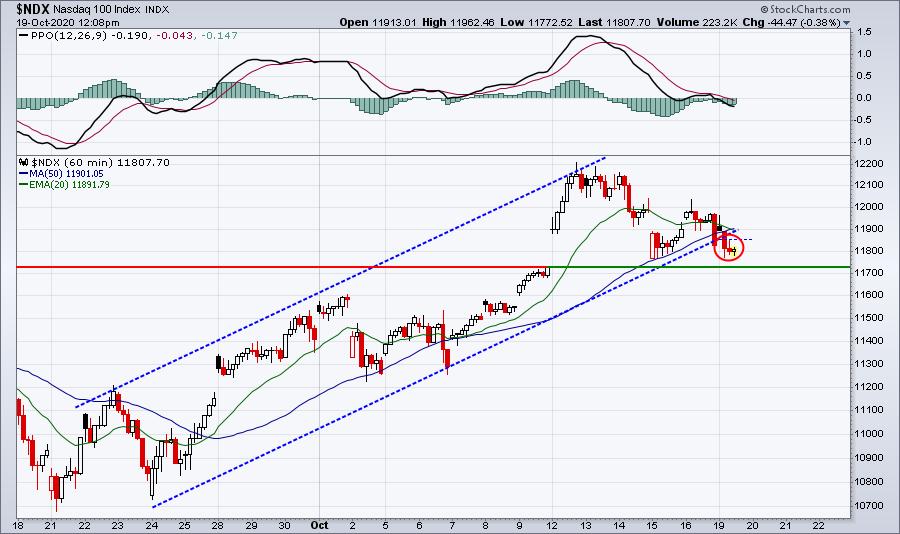
The number to watch on the NDX is 11724. A move beneath that level could trigger further short-term selling and we cannot forget which week it is. Be careful.
Sector/Industry Focus
Recreational services ($DJUSRQ, +1.61%) and travel & tourism ($DJUSTT, +0.67%) have two of the lowest SCTR scores among consumer discretionary industry groups at 35 and 23, respectively. Their strength could be options-related. These two groups did not move higher last week, instead falling. It's quite possible that net in-the-money put premium could be driving these stocks higher. With the exception of renewable energy ($DWCREE, +3.17%), it seems that most leading industries today had been laggards during much of October.
Recreational services is still rather challenged on both an absolute and relative basis:
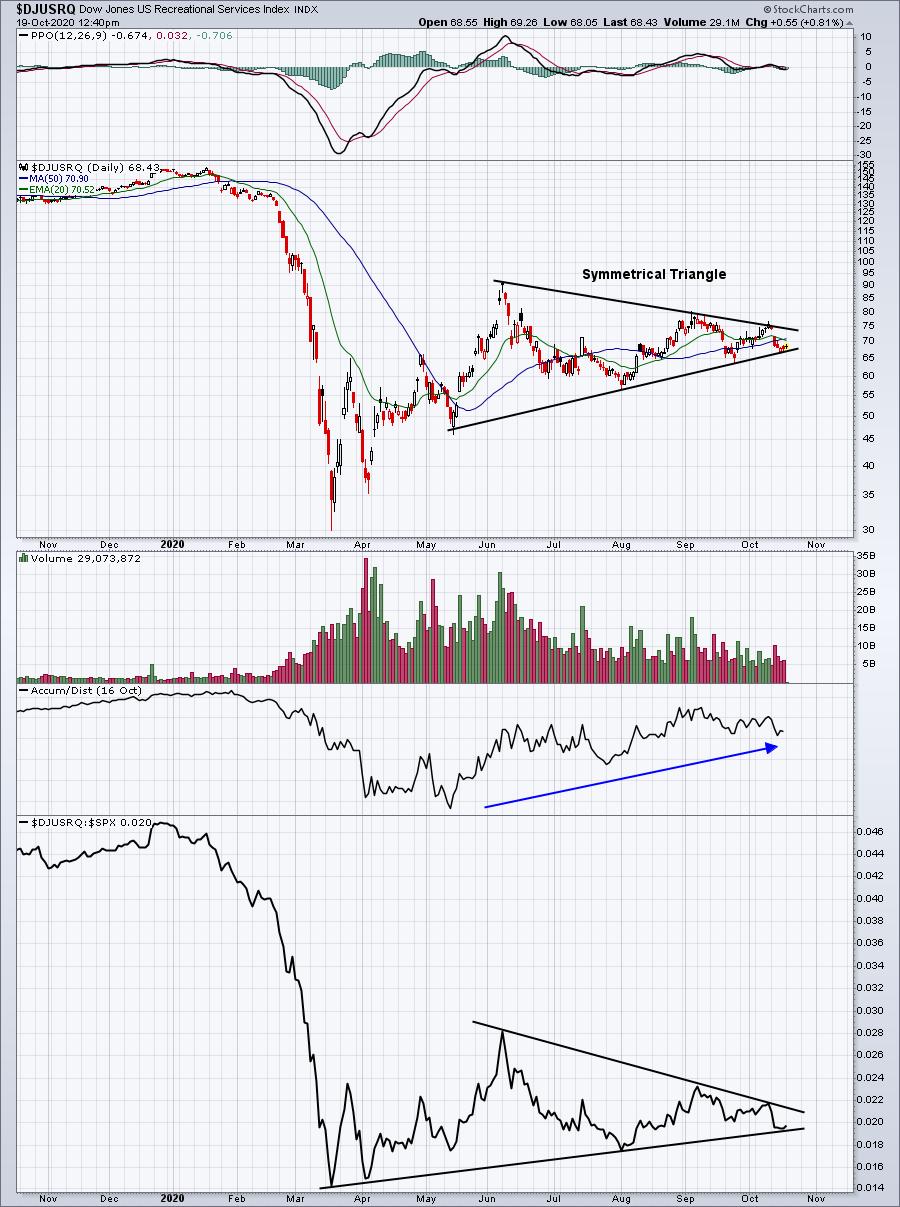
These triangles tend to resolve in the direction of the prior trend, which is down. Given that I believe we're in a secular bull market, we may not see that resolution. However, until further notice, expect relative weakness.
ChartLists/Strategies
I'm choosing to take a very cautious approach to U.S. equities in the very near-term. I do believe that earnings will ultimately send stocks higher, but the next week or so could see an acceleration of volatility. The VIX is up close to 2% on today's session. If we can keep the VIX below the key short-term resistance zone from 29 to 31, then I'll feel pretty good about the next rally. If it breaks above, though, be prepared for a quick, intense bout of selling.
In the meantime, I'll look for quick, one-off trades. On the Strong Earnings ChartList, TACO posted better-than-expected revenues and EPS late last week and there's been a big selloff since. It might very well be overdone. It's hit an initial price support level close to 7.70. A bounce from here is certainly possible:
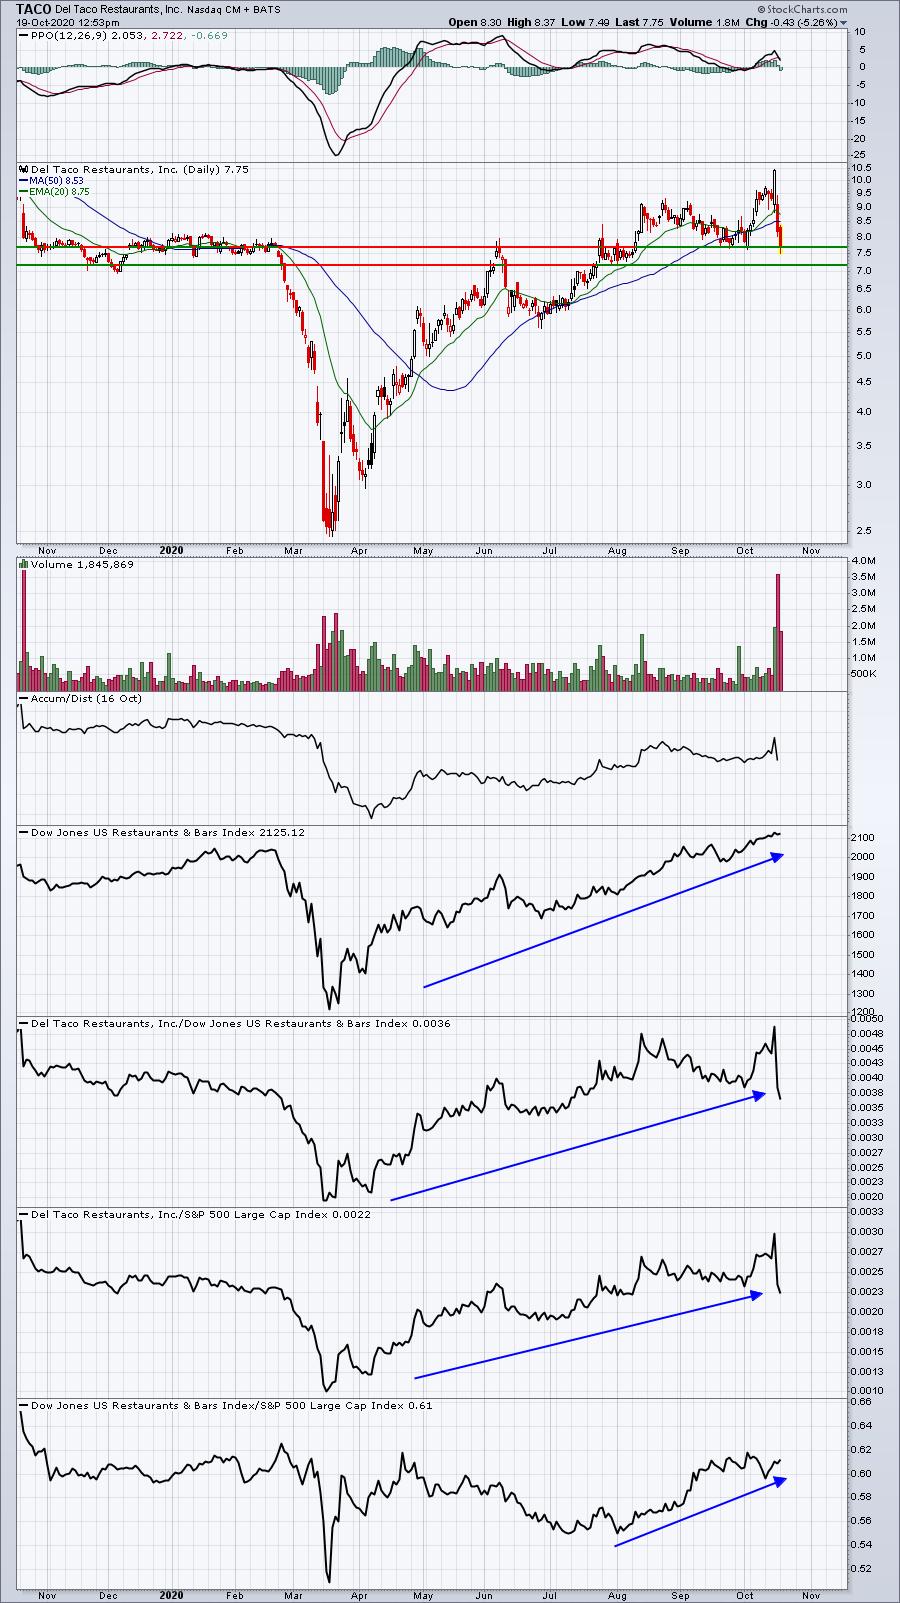
Failure at 7.70 could bring July gap support at 7.15 into play.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Monday, October 19:
IBM, CDNS, PPG, LOGI, ELS, HAL, CCK, LII, STLD, ZION, ADC, HXL, FNB
Tuesday, October 20:
PG, NFLX, TXN, PM, LMT, CNI, PLD, CP, UBS, SNAP, IQV, PCAR, TRV, IBKR, AGR, SYF, DOV, TER, RF, WRB, CMA, MAN, GPK, THC, IRBT
Economic Reports
October housing price index: 85 (actual) vs. 83 (estimate)
Happy trading!
Tom