
EB Daily Market Report - Tuesday, December 1, 2020
Executive Market Summary
- Futures were strong across the board this morning, as global markets rallied
- Zoom Video Communications (ZM, -13.68%) blew away revenue & EPS estimates and raised guidance on Monday after the close, but it's been a "buy on rumor, sell on news" development
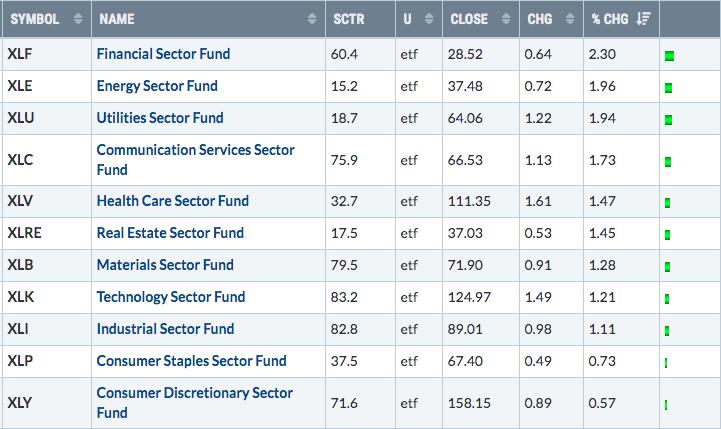
- Financials (XLF, +2.30%) and energy (XLE, +1.96%) are morning leaders among sectors
- The 10-year treasury yield ($TNX) is surging 8 basis points higher to 0.92%; the selling of treasuries is no doubt helping equities
- The U.S. Dollar (UUP,-0.73%) moves to new 2020 low as gold ($GOLD, +1.86%) jumps back above $1800
- Banks ($DJUSBK, +2.11%) are rallying on the rise in treasury yields
- Western Digital (WDC, +6.32%) our top December seasonality stock, opens the month with strong gains
Market Outlook
The good news is that strength continues in U.S. equities. But it's coming at the expense of aggressive growth stocks as rotation is occurring. In the last hour, we've seen growth (IWF) make somewhat of a comeback, but value (IWD) is in charge today. The following seasonality chart shows that the IWD definitely has a tendency to outperform the IWF during December, though that outperformance is short-lived based on its January relative weakness. Check out this chart:
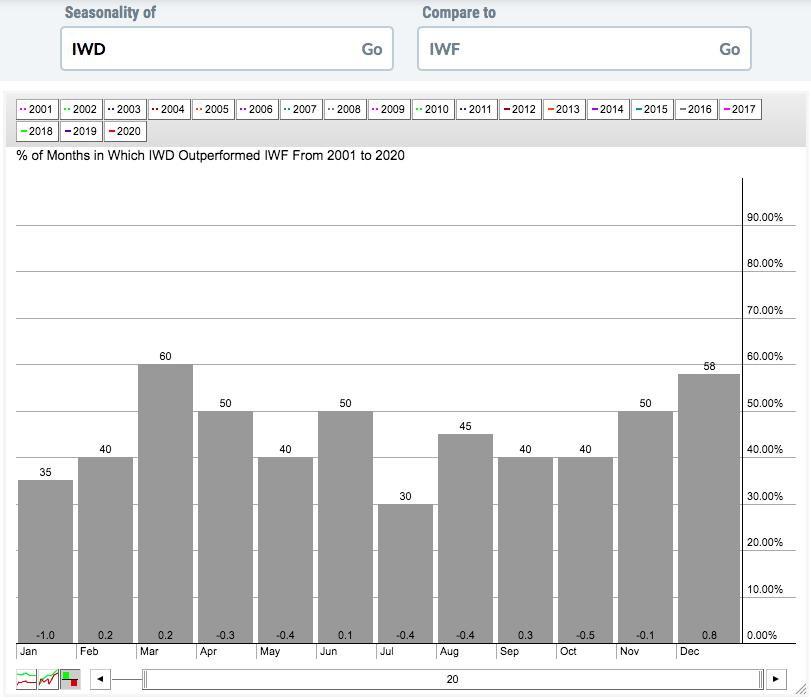
While the IWD's best performance vs. the IWF historically occurs in December, January is arguably the worst relative performance for those value stocks. So as we weave our way through December, keep this relative performance in the back of your mind. Honestly, it could result in December underperformance by our portfolios, which still lean significantly towards growth.
Sector/Industry Focus
Value (IWD), as mentioned above, is back in vogue today and that's typical behavior for the month of December, so don't let it surprise you. I suggested that defensive posturing in December has made sense through the years. December is a bullish month, but aggressive stocks tend to pause and allow temporary strength in defensive areas. As I mentioned in this past weekend's December Seasonality Report, real estate (XLRE) has been the big winner this century during December. Today's sector leaderboard - and I realize it's only one day - is mostly ignoring those aggressive sectors with 4 of them claiming the bottom 4 spots on the leaderboard:
ChartLists/Strategies
When I consider morning trades, which isn't too often, I normally look at stocks trading with extraordinarily high volume or stocks pulling back in early action on light volume. Let me give you a couple examples.
I ran a high volume scan of our Strong Earnings ChartList (SECL) and Strong Future Earnings ChartList (SFECL) to filter any stocks that have traded at least their daily average volume as of 10:45am ET today. 6 stocks were returned:
AHCO, APPN, FOUR, NOVA, SSTK, VERI
SSTK looked very interesting to me as this stock is breaking out:
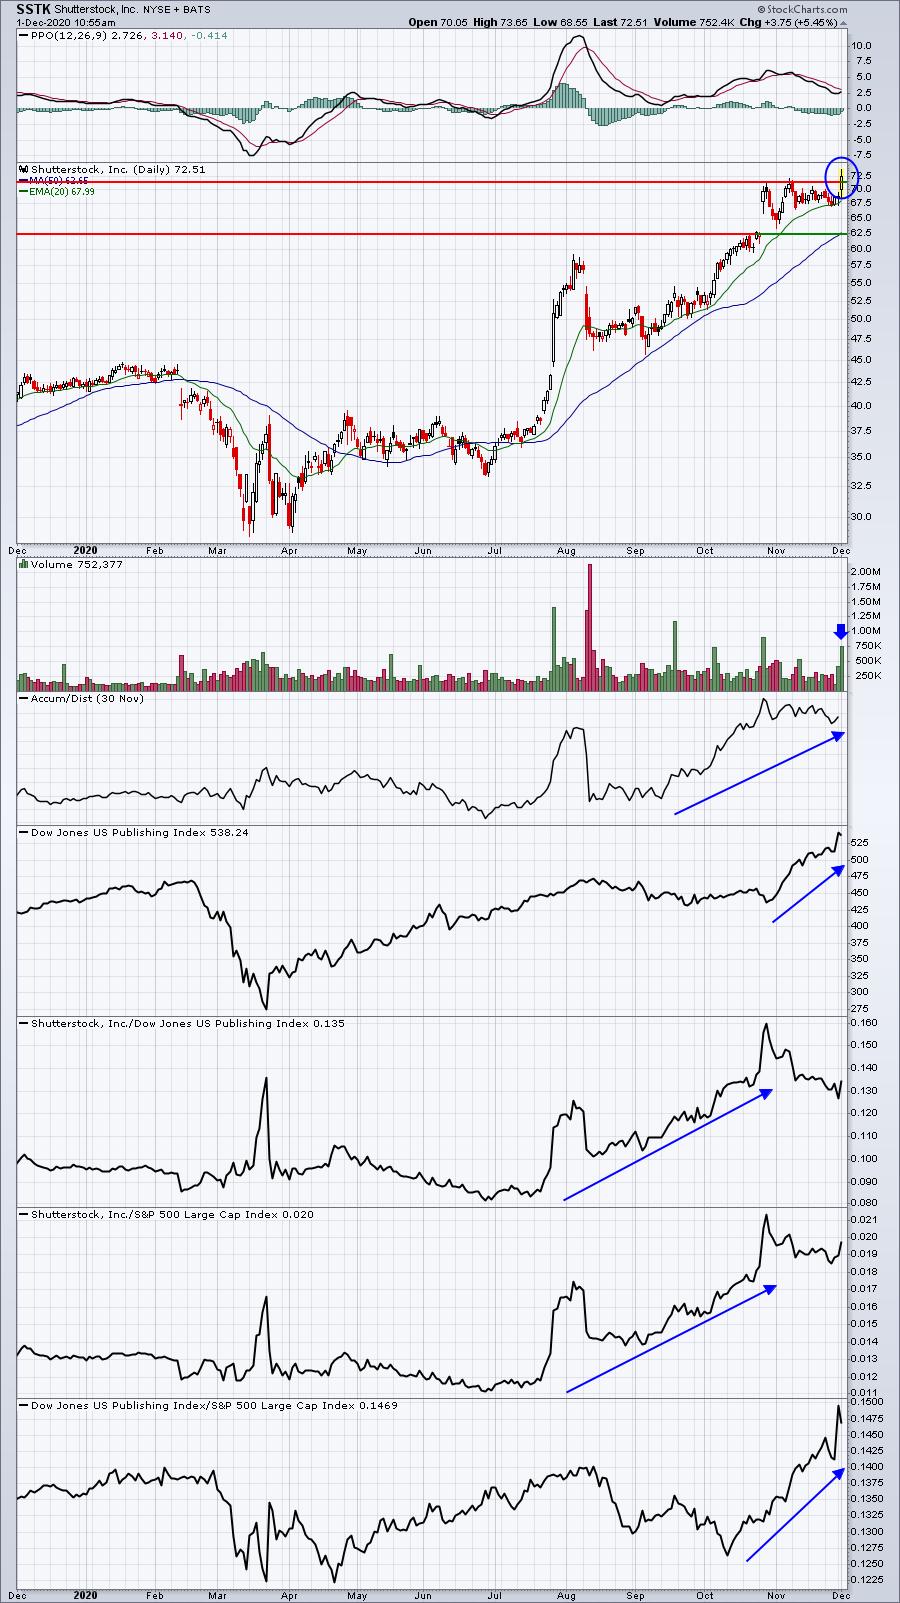
If SSTK can hold the breakout into its close today, I'd look for higher prices ahead. If it fails, then look for maybe one more test of its rising 20 day EMA. Either way, I expect it goes higher. Its industry group, publishing ($DJUSPB) has been exploding higher on a relative basis, so it certainly doesn't hurt that SSTK is part of a strong group that's seeing money rotate its way.
Now let me take a different approach and combine a pullback scan with known seasonality strength. Running our 20 day EMA scan against the SECL with SCTRs above 90, LL was returned. It's part of the home improvement group ($DJUSHI), which has struggled of late, but loves December:
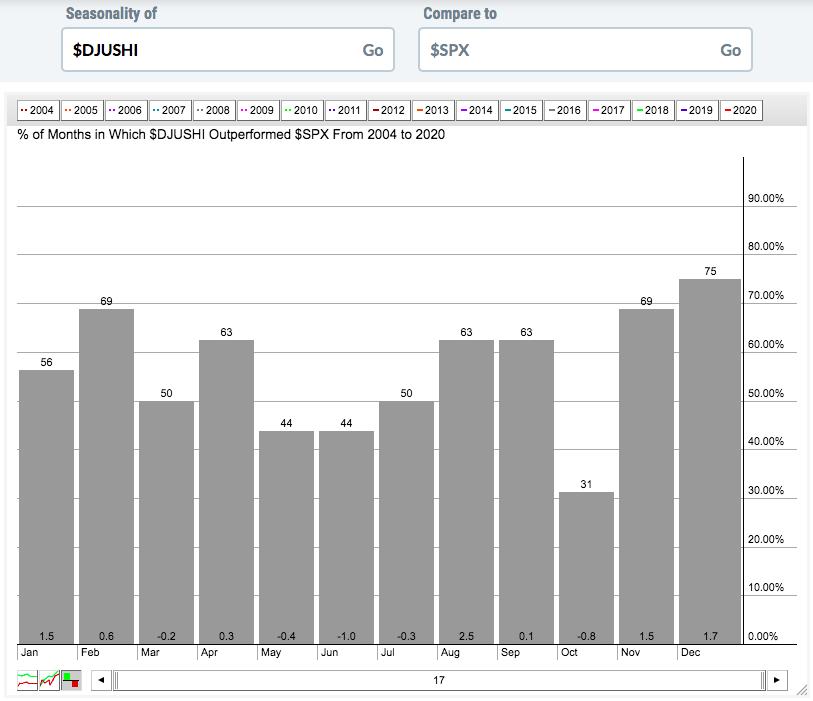
The DJUSHI has outperformed the S&P 500 75% of all Decembers over the past 17 years and its average outperformance is a very solid 1.7 percentage points per December. LL loves the month of December as well:
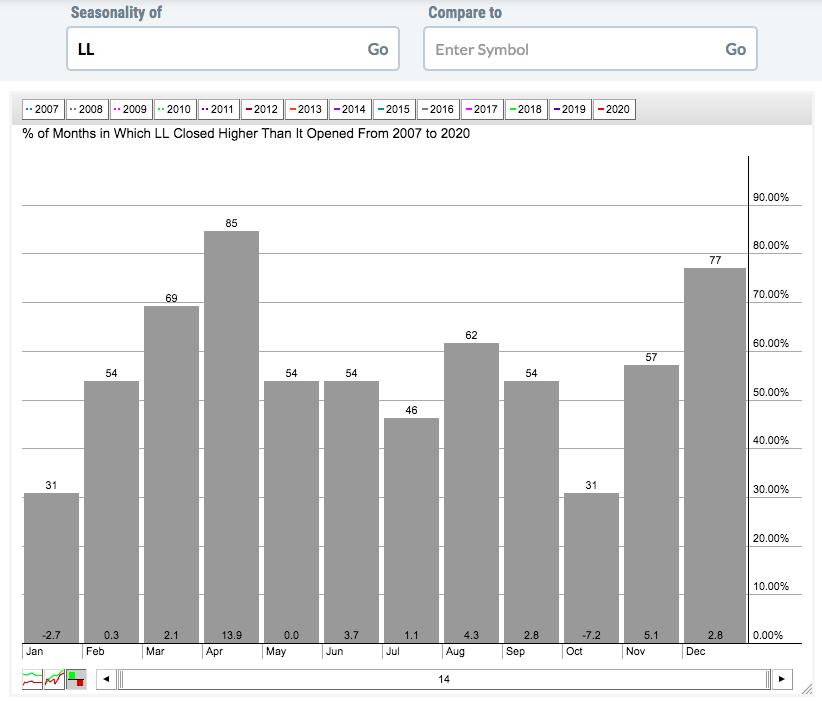
LL has risen 77% of its last 14 Decembers and averages returning 2.8% per December. That makes today's 20 day EMA test a bit more appetizing:
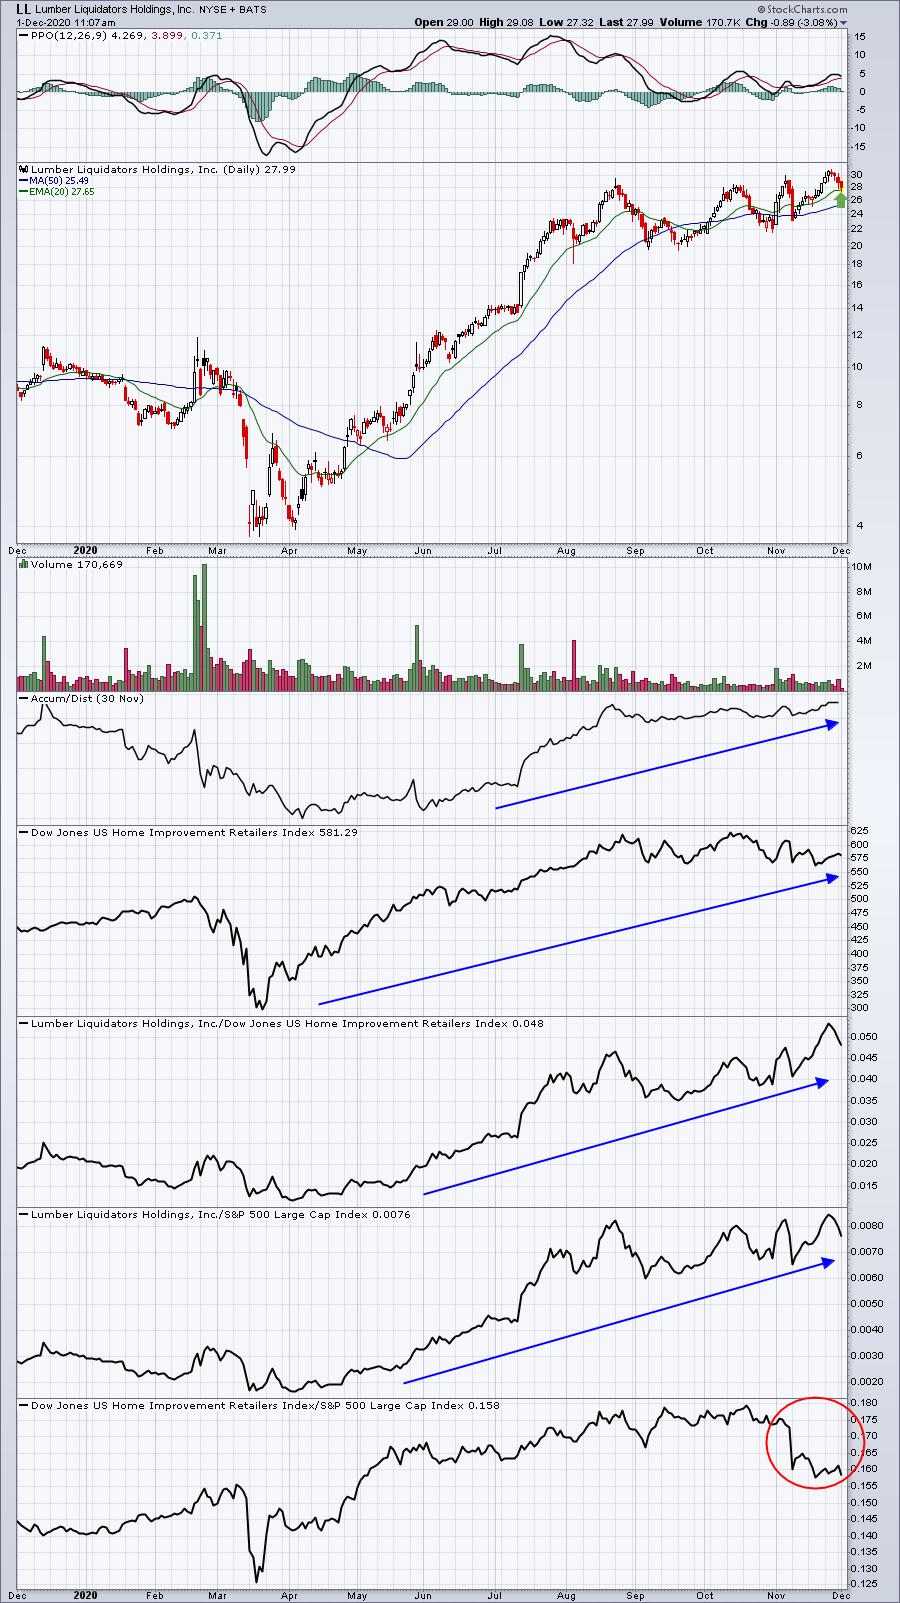
The biggest concern is the relative weakness of home improvements in November, but they do typically flip that bullish switch in December and the group had a reason to underperform as it was consolidating the past several weeks.
This type of analysis never guarantees us a profitable trade, but it does enable us to feel more confident about our trades given the homework we do.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Tuesday, December 1:
CRM, BNS, BMO, VEEV, LU, TCOM, HPE, NTAP, MOMO, BOX, HOME
Wednesday, December 2:
RY, SNOW, SNPS, CRWD, SPLK, OKTA, ZS, ESTC, FIVE, PVH, DSGX, SMTC, PDCO, GES
Economic Reports
November PMI manufacturing: 56.7 (actual) vs. 56.7 (estimate)
November ISM manufacturing: 57.5 (actual) vs. 57.7 (estimate)
October construction spending: +1.3% (actual) vs. +0.8% (estimate)
Happy trading!
Tom