
EB Daily Market Report - Wednesday, December 23, 2020
Note
This will be the last DMR this week. We will be closed for Christmas Eve. I want to wish everyone a safe and happy holiday this weekend. If you spend it with family, please be safe!
I'll likely publish my next DMR on Monday. If not, we'll be sure to let you know. Volume will subside next week and trading should be fairly quiet as many market participants will be on vacation.
Please note that there will not be a Trading Places LIVE show on Monday and Wednesday at EarningsBeats.com.
Executive Market Summary
- Futures suggested all of our major indices would open higher, which they did
- The NASDAQ has suffered on a relative basis throughout the day, however
- There were tons of economic reports as many were moved up ahead of Christmas Eve
- New home sales were very weak, so home construction's ($DJUSHB, -1.67%) weakness shouldn't be a shocker
- Many areas hit hardest by the pandemic are trading higher today
- Recreational services ($DJUSRQ), banks ($DJUSBK), and airlines ($DJUSAR) are all trading higher by more than 3%
- The 10-year treasury yield ($TNX) is up 4 basis points to 0.96%, aiding the banks specifically and financials (XLF, +2.13%) in general
- Recent winners are seeing profit taking today - Etsy, Inc. (ETSY, -3.00%) is the worst performing S&P 500 stock
Market Outlook
The NASDAQ 100 ($NDX) typically leads during bull market advances, so when we're in an uptrend, I'll review the NDX chart. We are currently trending higher and the NDX has been bouncing off 20 day EMA tests, which is bullish:
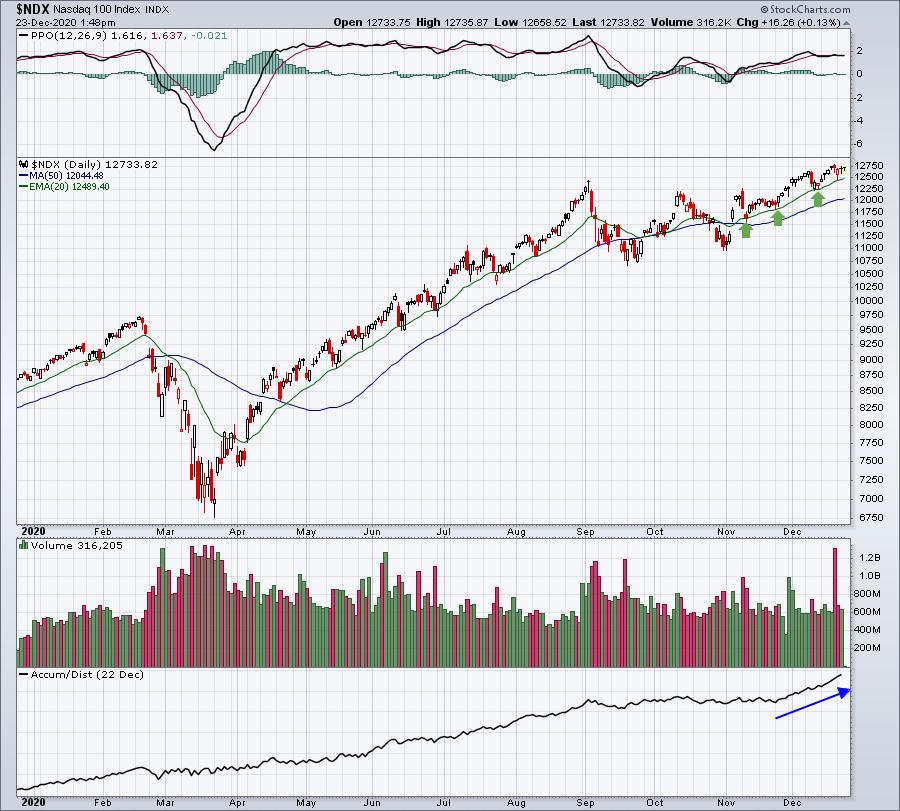
Look at the AD line as it soars higher! Furthermore, three recent 20 day EMA tests were all successful. I don't care what news is being reported or what futures do overnight, I remain long during these periods so long as the chart tells me to do so.
Sector/Industry Focus
Energy (XLE, +2.29%) is today's leading sector as we move to the 3rd day past options expiration Friday. Last week, we discussed how it was in the market makers' best interests to see a decline in energy shares. Shockingly (sarcasm intended), the XLE finished lower for 5 straight days. I feel like market makers let go of the chokehold they had on energy call holders:
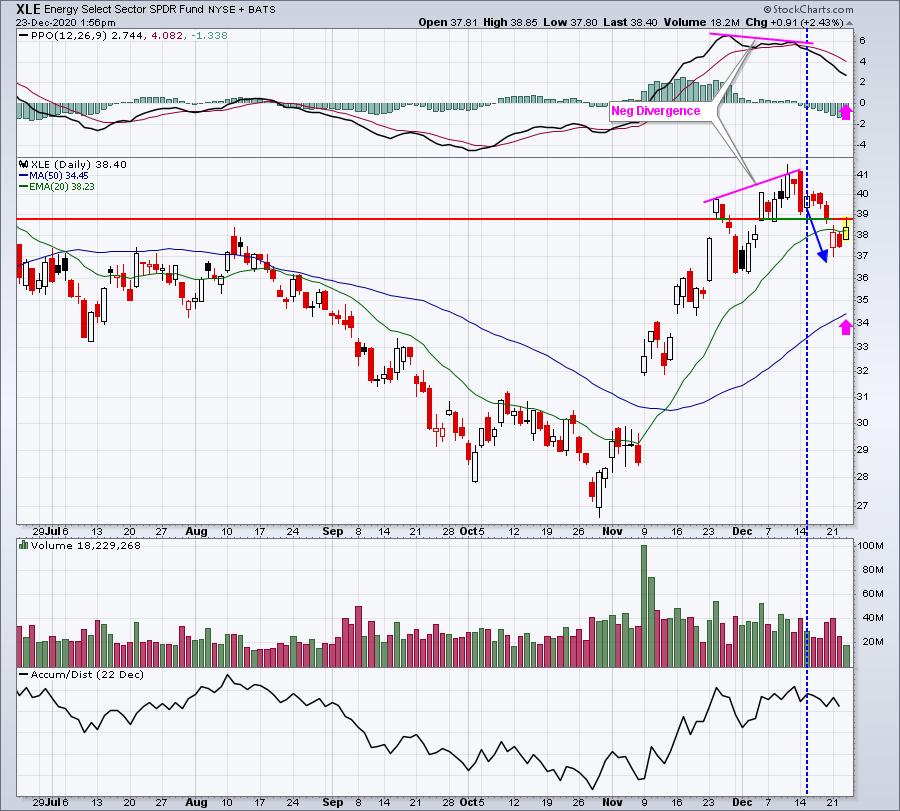
The blue-dotted vertical line highlights when we had our max pain session. You can see the XLE selling that took place after it. Also, there's a negative divergence in play here that could lead to further short-term selling. I tend to look for successful 20 day EMA tests if the most recent price high produced a PPO high as well. But in XLE's case, the last price high was accompanied by a lower PPO high. The pink arrows mark the 50 day SMA and PPO centerline support.
ChartLists/Strategies
I ran the Downtrend Reversal scan from our website against the Strong Earnings ChartList (SECL), Strong Future Earnings ChartList (SFECL), and Raised Guidance ChartList (RGCL). I ran it as of yesterday and 9 stocks were returned. One interesting stock was CAR.
CAR:
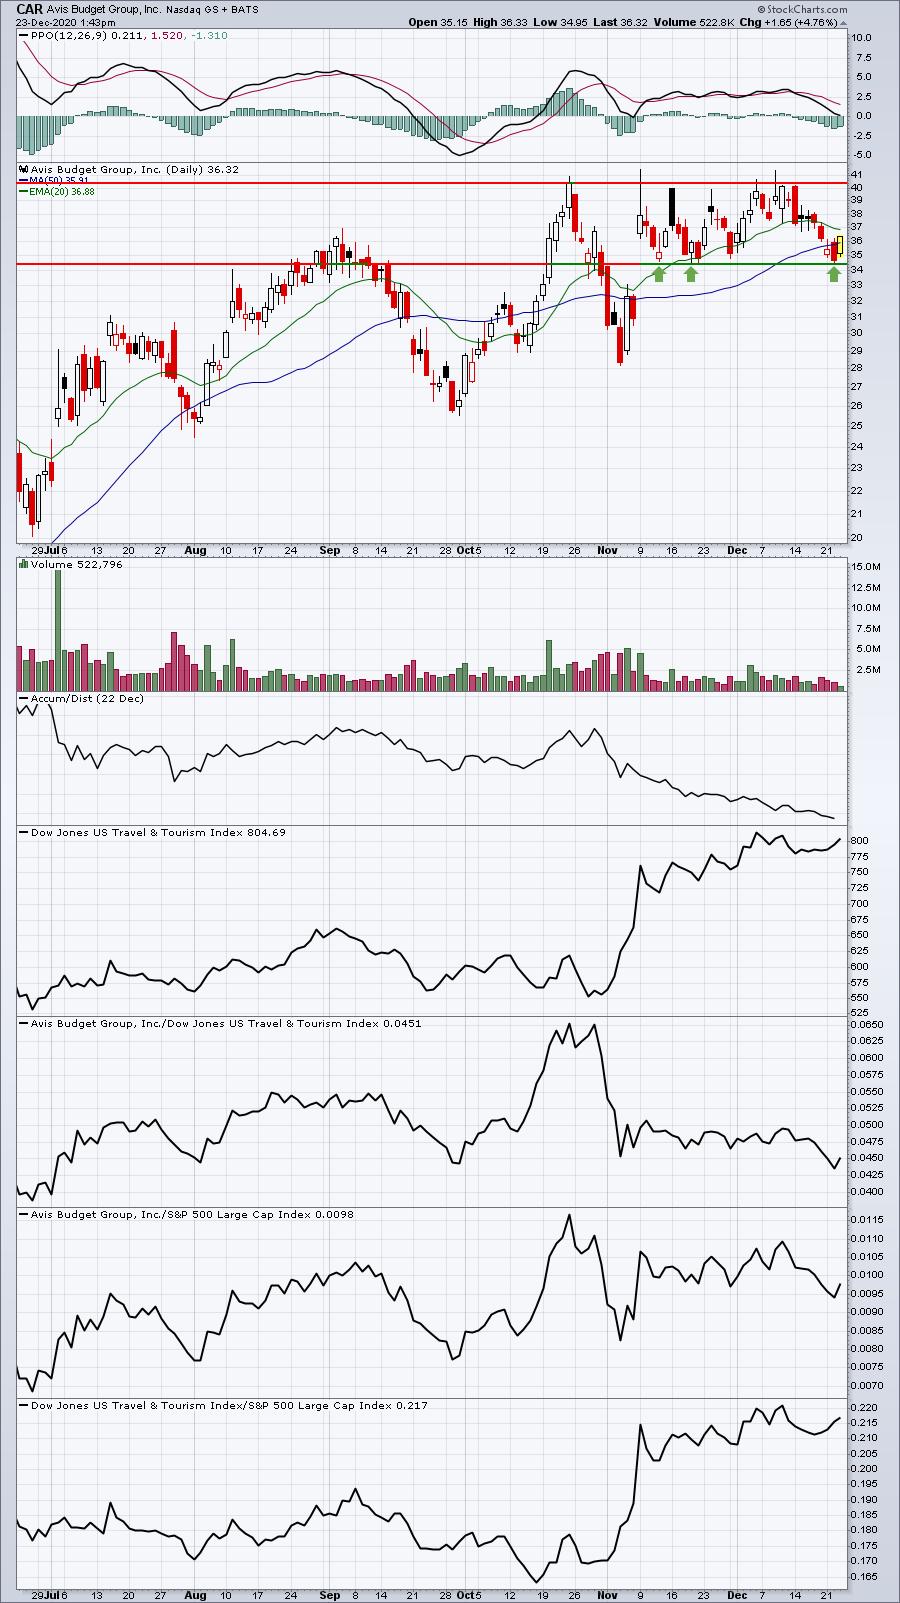
The travel & tourism group ($DJUSTT) has definitely been strengthening on a relative basis, but CAR has two strikes against it. First, the AD line is very weak. Second, CAR's relative strength vs. the DJUSTT is not good at all. As a result, I would typically ignore the potential buy signal off price support. If I did take a position, I'd make sure I kept a very tight stop just below recent price lows.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, December 23:
PAYX
Thursday, December 24:
None
Economic Reports
November durable goods: +0.9% (actual) vs. +0.6% (estimate)
November durable goods ex-transports: +0.4% (actual) vs. +0.5% (estimate)
Initial jobless claims: 803,000 (actual) vs. 875,000 (estimate)
November personal income: -1.1% (actual) vs. -0.3% (estimate)
November personal spending: -0.4% (actual) vs. -0.2% (estimate)
October FHFA house price index: +1.5% (actual) vs. +0.5% (estimate)
November new home sales: 841,000 (actual) vs. 989,000 (estimate)
December consumer sentiment: 80.7 (actual) vs. 81.0 (estimate)
Happy trading!
Tom