
EB Daily Market Report - Friday, January 15, 2021
Executive Market Summary
- Futures were weak this morning, but hey it's option expiration Friday
- Large money center banks kicked off earnings season this morning as JPM, C, WFC, and PNC all reported; all 4 are lower today, but JPM clearly has had the best response from Wall Street
- The 10-year treasury yield ($TNX) is down 4 basis points to 1.09%, seemingly responding more to the weak retail sales numbers
- Industrial production and capacity utilization, however, came in well above expectations - a bullish signal
- Defensive sectors are leading today's action, while energy (XLE, -3.01%) and financials (XLF, -1.75%) lag
- The S&P 500 laggards are littered with companies that have performed extremely well in recent weeks, a likely reversal due to options expiration
- Home Depot (HD, +2.50%) and Amgen (AMGN, +1.78%) are the only two Dow Jones stocks gaining more than 1% today
Market Outlook
Welcome to monthly options expiry! Anyone shocked by today's selling? Don't be. This is simply a minor bout of selling that's likely making market makers a BOATLOAD of money. Areas of the market that have been strong are mysteriously weak today. Don't believe me? Check out the Sector Summary in the Sector/Industry Focus section below.
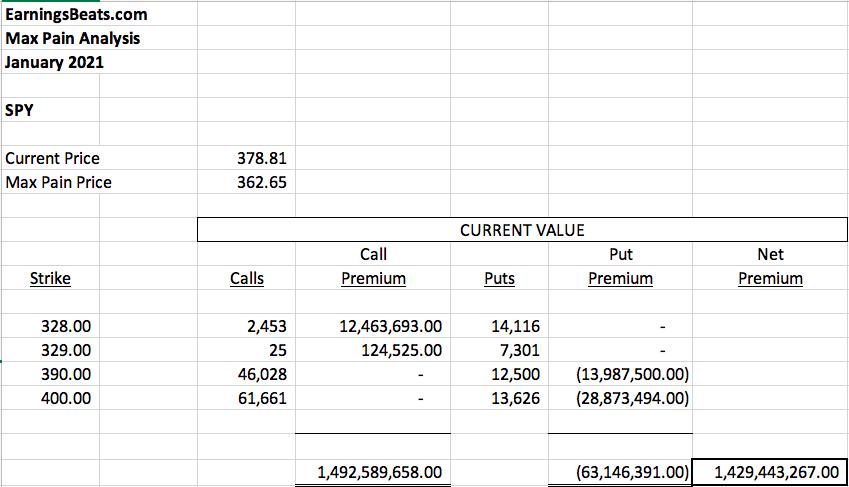
When we had our Max Pain event on Tuesday after the close, the SPY was at 378.81 and the calculated value of net in-the-money call premium was $1.43 billion:
At today's intraday low on the SPY of 373.70, here's that same calculation:
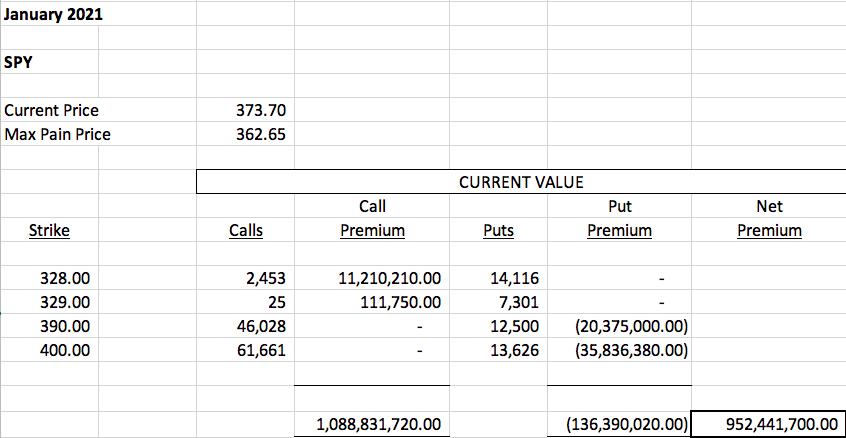
Now I realize that the max pain level likely changed slightly from Tuesday's close. However, that drop of nearly $500 million in net in-the-money call premium is STAGGERING! That's just one ETF option, albeit a heavily-traded one. This max pain work never guarantees us a thing, but hopefully you understand the risks that you take if you buy stocks or ETFs in the middle of the month without considering the potential impact of options expiry.
Sector/Industry Focus
The strongest ETFs of late are selling today, while the weakest are holding up best. Check out this Sector Summary leaderboard today. I want you to focus on the SCTR scores for each sector. Note that the worst sectors are leading today, while the best sectors are lagging. I swear, you can't make this stuff up:
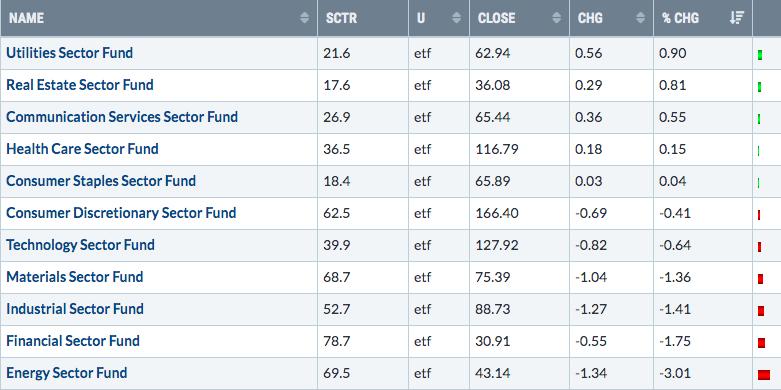
Coincidence? I think not.
ChartLists/Strategies
Let's take a break with potential trade candidates today. We could have a bit more selling and/or consolidation to deal with in the very near-term. Monday's a holiday - Martin Luther King Day - and U.S. markets will be closed. We'll regroup on Tuesday and see what stocks present opportunities based on any further short-term selling. If we rebound, we'll still have plenty of choices available. I don't worry about that.
I will say this, however. When I look at a stock like Zoom (ZM), which has been weak for the past few months, it doesn't seem to be impacted by the options-related selling. However, ENPH, the worst performing S&P 500 stock today, shows the following open interest at CBOE.com:
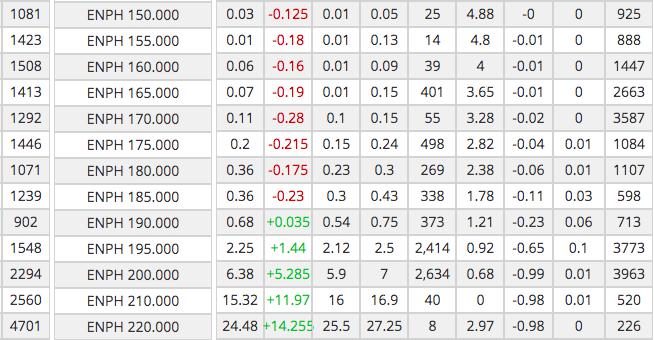
The far left column represents the open call interest and the far right column represents the open put interest. There are thousands of open in-the-money calls that are seeing their value significantly reduced or eliminated. Meanwhile, there's almost no in-the-money put premium. This is how market makers LEGALLY steal from options traders as time runs out. ENPH will likely see more weakness ahead near-term, which will present an opportunity from a trading perspective.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Friday, January 15:
JPM, WFC, C, PNC
Tuesday, January 19:
BAC, NFLX, SCHW, GS, IBKR, STT, HAL, JBHT, CMA, ZION, PNFP
Economic Reports
December PPI: +0.3% (actual) vs. +0.4% (estimate)
December Core PPI: +0.1% (actual) vs. +0.2% (estimate)
December retail sales: -0.7% (actual) vs. -0.1% (estimate)
December retail sales less autos: -1.4% (actual) vs. -0.1% (estimate)
January empire state manufacturing index: 3.5 (actual) vs. 6.0 (estimate)
December industrial production: +1.6% (actual) vs. +0.5% (estimate)
December capacity utilization: 74.5% (actual) vs. 73.6% (estimate)
November business inventories: +0.5% (actual) vs. +0.4% (estimate)
January consumer sentiment: 79.2 (actual) vs. 80.0 (estimate)
Happy trading!
Tom