
EB Daily Market Report - Thursday, April 15, 2021
Executive Market Summary
- Futures were strong overnight and action has strengthened throughout the day
- The Dow Jones has topped 34000 for the first time in history
- The S&P 500 is another strong day away from topping 4200 for the first time in its history
- The NASDAQ has returned back above 14000 and is now within roughly 0.6% of its all-time high, established in mid-February
- Earnings reports are mostly well above consensus estimates, helping to fuel this rally
- Unitedhealth Group (UNH, +3.41%) is today's top performing Dow Jones component, after surpassing estimates
- Technology (XLK, +1.70%) and health care (XLV, +1.70%) are co-leading sectors today
- Renewable energy ($DWCREE, -7.23%) is free-falling today and going completely against the bullish grain of the market
Market Outlook
Banks ($DJUSBK) continue to post excellent quarterly results, but a lot of good news was already built into stock prices. This morning, Bank of America (BAC, -2.92%) and Citigroup (C, -0.22%) posted the following quarterly revenues and EPS (estimates in parenthesis):
- BAC: Revenues - $22.8 billion ($21.7 billion), EPS - $.86 ($.62)
- C: Revenues - $19.3 billion ($18.3 billion), EPS - $3.62 ($2.18)
These are BIG beats and it bodes well not only for bank stocks, but for the economy and U.S. equities in general. We ALWAYS want a strong banking industry because it leads to easier credit availability for companies looking to grow their businesses.
Sector/Industry Focus
Despite a few excellent economic reports, including March retail sales and much lower-than-expected jobless claims, the 10-year treasury yield ($TNX) is down substantially - 9 basis points to 1.55%. Momentum has been slowing in the TNX, so I've been looking for potentially 1.50% to the downside. Here's a chart highlighting the negative divergence:
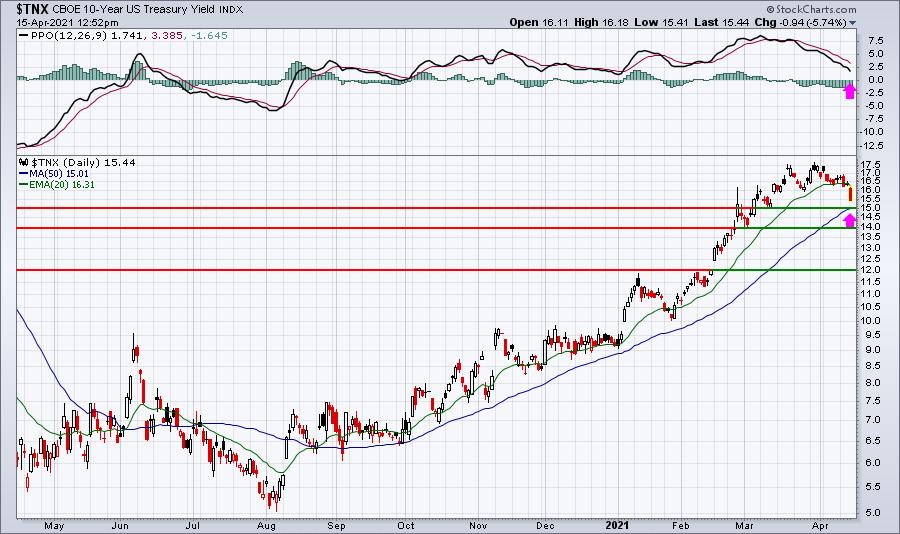
The pink arrows mark the PPO centerline and the 50-day SMA, two areas that I typically look to be tested after a negative divergence emerges. If 1.50% doesn't hold, then look to 1.40% as the next support. Then there's 1.20%. I doubt we'd see that type of buying in treasuries to drive the yield that low, especially given the very strong economic reports coming out.
ChartLists/Strategies
The max pain candidates, especially on the long side, have really struggled these past couple days. Plug Power (PLUG, -11.64%), despite having thousands and thousands of in-the-money puts in place and plenty of incentive for market makers to reverse the price action, continues to plummet. The key to me is that volume remains extremely heavy, which makes it difficult for market makers to commit capital on the long side to attempt to reverse price action. The entire renewable energy space ($DWCREE, -6.40%) is under intense selling pressure, it's just not PLUG. Similar action is taking place today in Ballard Power (BLDP, -7.46%) and FuelCell Energy (FCEL, 13.09%). Heavy volume selling like this typically ends in a capitulatory moment, but the difference between it occurring today, tomorrow, or next week can be very significant in terms of % decline.
Here's a chart of the DWCREE, with key support levels to watch for reversals:
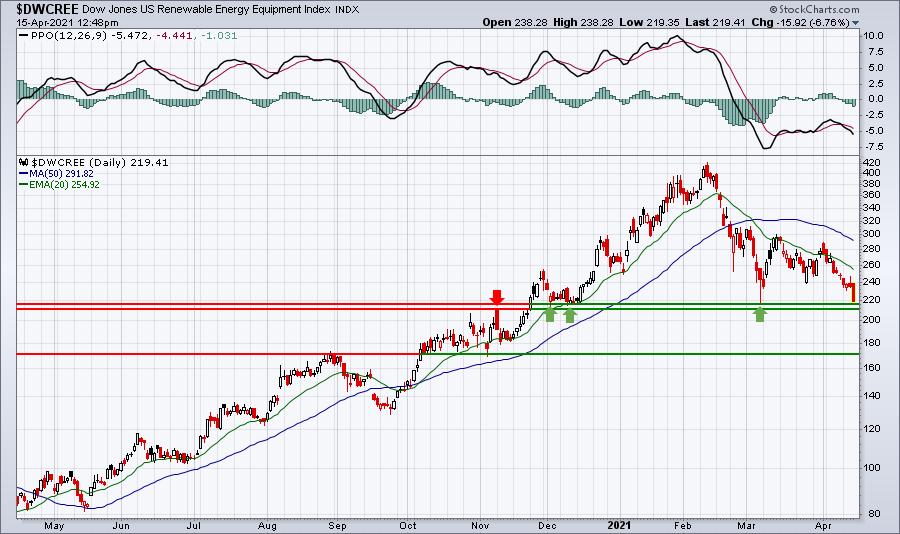
217.36 marked the low on March 5th, which was a capitulatory low. That level needs to hold or these renewable energy stocks could sell off a lot further. I'd count on it to hold, but if it doesn't, I'd grow much more cautious on the group.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, April 15:
TSM, UNH, BAC, PEP, C, BLK, SCHW, USB, TFC, PGR, WIT, PPG, DAL, JBHT, WAL, CBSH, AA, RAD
Friday, April 16:
MS, PNC, BK, STT, KSU, CFG, ALLY
Economic Report
Initial jobless claims: 576,000 (actual) vs. 695,000 (estimate)
March retail sales: +9.8% (actual) vs. +5.6% (estimate)
March retail sales less autos: +8.4% (actual) vs. +5.0% (estimate)
April empire state manufacturing index: 26.3 (actual) vs. 17.0 (estimate)
March industrial production: +1.4% (actual) vs. +2.8% (estimate)
March capacity utilization: 74.4% (actual) vs. 75.7% (estimate)
April housing market index: 83 (actual) vs. 83 (estimate)
Happy trading!
Tom