
EB Daily Market Report - Wednesday, May 12, 2021
Executive Market Summary
- Futures were weak overnight and the weakness escalated after CPI data was released
- April CPI surged 0.8%, well above the 0.2% expectation; Core CPI rose a similar amount, +0.9% vs. +0.3%
- The higher inflationary environment encouraged further selling in high-growth areas like consumer discretionary (XLY, -3.23%) and technology (XLK, -2.78%)
- Selling is intensifying in the final hour with the Dow Jones down nearly 600 points at last check; the NASDAQ, however, along with small and mid caps, are leading to the downside
- Gambling stocks ($DJUSCA, -3.63%) remain under intense selling pressure; we've seen more than a 15% decline in just the past two weeks
- Home Depot (HD, -4.13%) is the biggest loser in the Dow Jones, while Caesars (CZR, -8.40%) and Penn National Gaming (PENN, -8.38%) pace the S&P 500 laggards
- Tomorrow morning we'll get the latest PPI numbers for April
Market Outlook
I wrote an article one month ago in ChartWatchers that discussed the likely rise in inflation and how that might impact stocks. But one thing you must realize about the stock market is that it always anticipates such things. I certainly wasn't the only one that recognized that key inflationary data would be hotter than expected. So market participants will sell growth stocks ahead of that news, but a key question to ask.......is this a "sell on rumor, buy on news" event? In other words, once the news hits, do we see growth stocks bought? Well, one way to gauge this is to review both daily and intraday the IWF:IWD ratio (growth vs. value). Here's the daily:
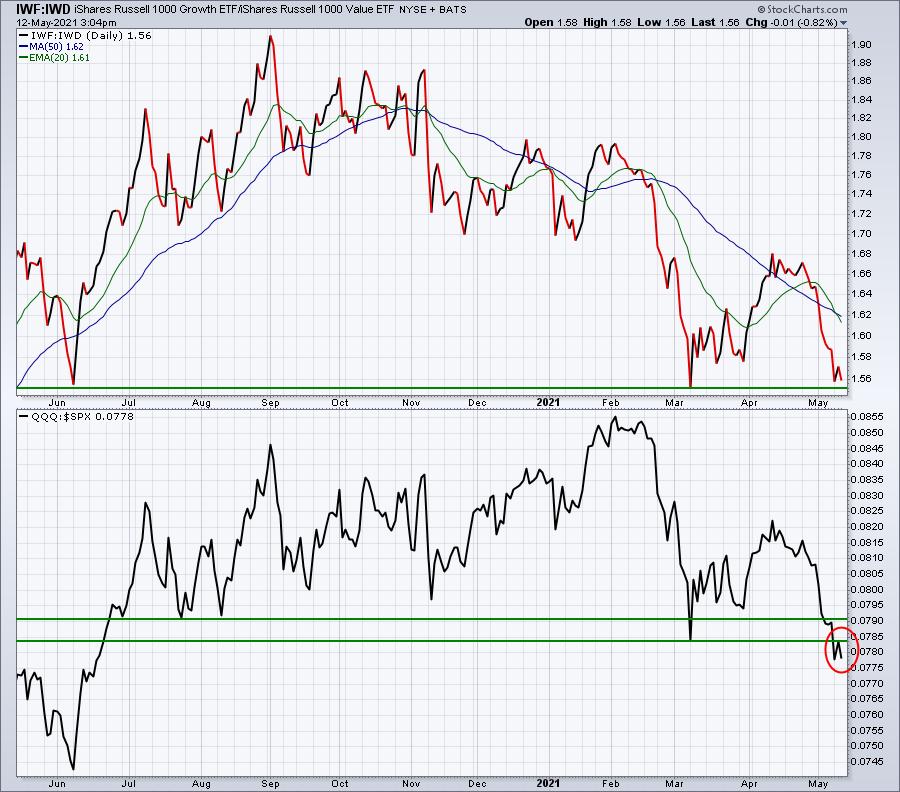
I've added the QQQ:SPY ratio (NASDAQ 100 vs. S&P 500) in the bottom panel and you can see this ratio has broken down. But the top part of the chart shows that, at this point, the IWF:IWD ratio is still holding relative support at 1.55. Here's the intraday view (5-day, 10-minute chart):
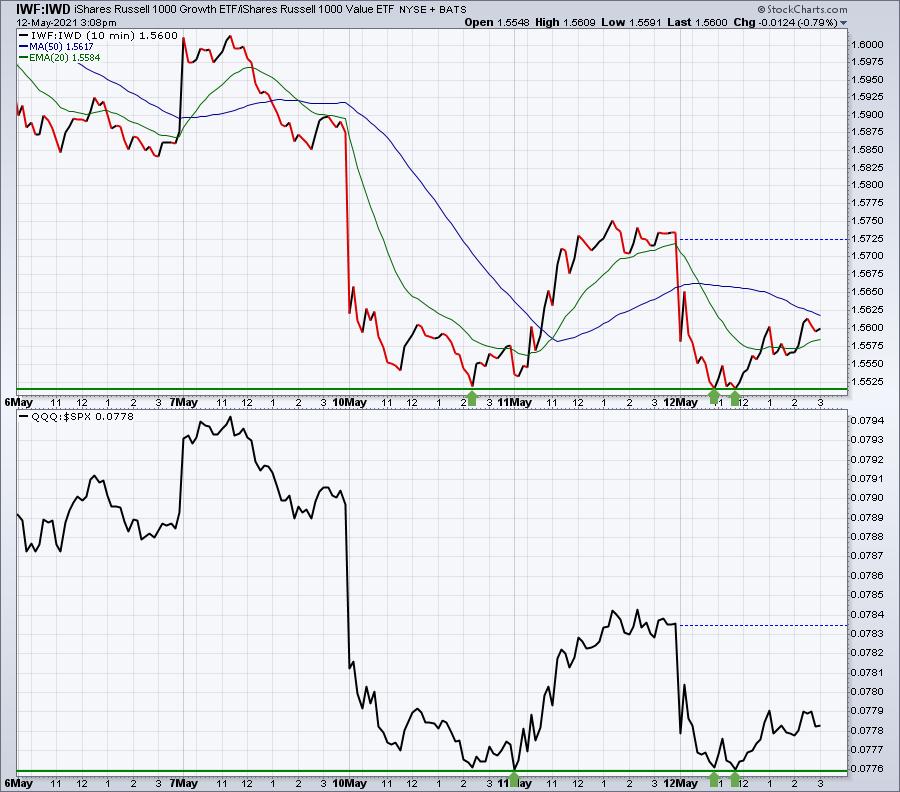
This morning's action was weak and obviously quite bearish in the short-term, but if there's one silver lining, it's that the relative support levels from Monday/Tuesday have not been broken.....yet.
Sector/Industry Focus
Energy (XLE) remains the leader today as crude oil prices ($WTIC) have gained more than 1% to push above $66 per barrel. Here's today's sector leaderboard:
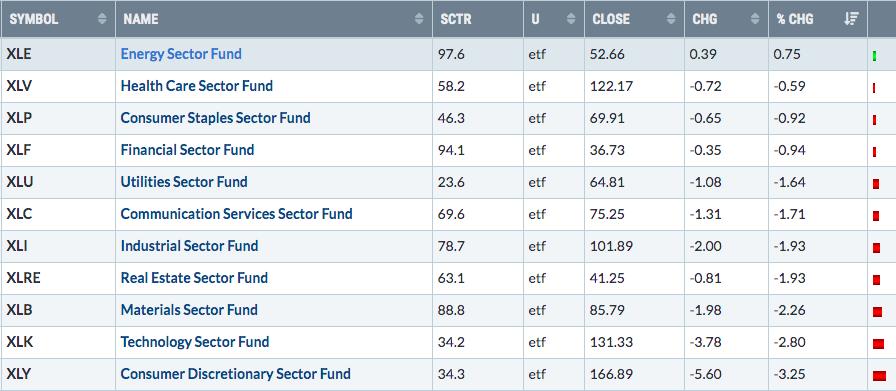
As would be expected, consumer discretionary (XLY) and technology (XLK), two high-growth areas, are the worst performing sectors, very likely due to the inflationary concerns and the impact that will have on future earnings. Both of these groups, which I believe are excellent long-term buys, remain in short-term trouble as their relative strength continues to deteriorate. It's possible we might need to work our way through this inflationary "bubble" over the next couple months before the masses begin buying these two groups again. The charts will let us know when these two groups look healthy again. It's certainly not right now.
ChartLists/Strategies
Given all the uncertainty over the market right now and with the Volatility Index ($VIX) spiking 22% higher to 26, it's probably best to wait and allow the market to establish a VIX top before considering further long trades, especially in high-growth areas. If needing to trade, I'd look mostly towards energy and health care.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, May 12:
CPNG, WIX, DT, DOX, PAAS, LITE, WEN, SONO, TSEM, JACK, BOOT, PLBY, MNKD
Thursday, May 13:
BABA, DIS, ABNB, BAM, DASH, BILI, FTCH, NICE, GDRX, GLOB, YETI, LAZR, GOOS, EYE, UTZ, NEWR, CELH, HAE, PLT, ACB, BLNK
Economic Reports
April CPI: +0.8% (actual) vs. +0.2% (estimate)
April Core CPI: +0.9% (actual) vs. +0.3% (estimate)
Happy trading!
Tom