
EB Daily Market Report - Thursday, May 27, 2021
Executive Market Summary
- Futures were higher overnight and our major indices opened higher this morning
- Small and mid caps have been the big winners, however, building on opening gains
- Our other indices are struggling to hang onto those early gains
- Aerospace ($DJUSAS, +2.56%) is breaking out and aiding industrials (XLI, +1.28%), today's top performing sector
- Furnishings ($DJUSFH, +3.04%) is seeing a return of strength, leading the consumer discretionary area (XLY, +0.32%)
- There's been very little movement today among sectors, though energy (XLE, -0.38%) and technology (XLK, -0.35%) are the weakest groups
- Boeing (BA, +3.58%) is having another very strong day, contributing to the strength in aerospace
Market Outlook
We've seen a bit of rotation back to growth (IWF) from value (IWD), as evidenced by the rising IWF:IWD and QQQ:SPY ratios. This is occurring despite the recent talk about inflation. If market participants truly expect that inflation will be problematic long-term, both of these ratios will fall. Instead, since the inflationary data hit earlier this month, both of these ratios have been on the rise:
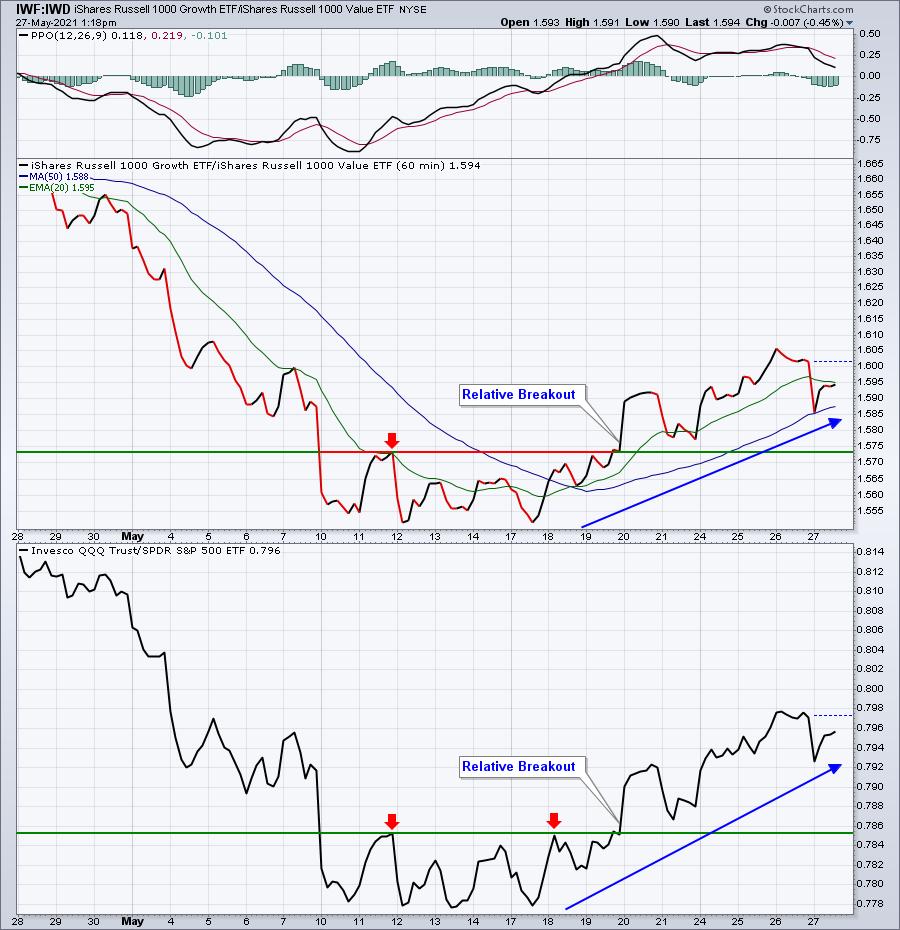
There's still a LONG way to go before I'd feel good about owning growth stocks, but one positive thus far has been the holding of relative support on the IWF:IWD ratio at 1.55. That's a key relative support level and so far, so good.
Sector/Industry Focus
There's a big time industry group breakout taking place today and it's in aerospace ($DJUSAS). A bullish ascending triangle pattern suggests this breakout has quite a ways to go to the upside:
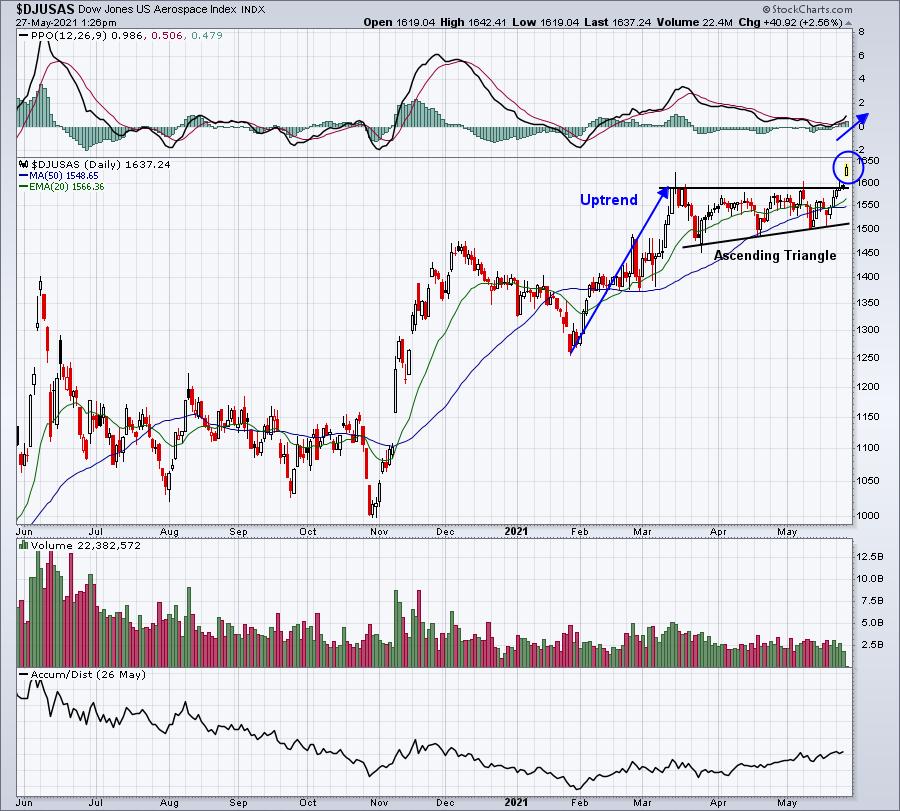
The measurement of an ascending triangle is the distance between its resistance area and its first low after the pattern begins. That would be roughly 150 points in this case. So my initial target on the DJUSAS would be 1750 - great news for the aerospace stocks featured below.
ChartLists/Strategies
Given the bullish breakout on aerospace stocks, let's review two stocks within this industry group that are also on our ChartLists.
HXL:
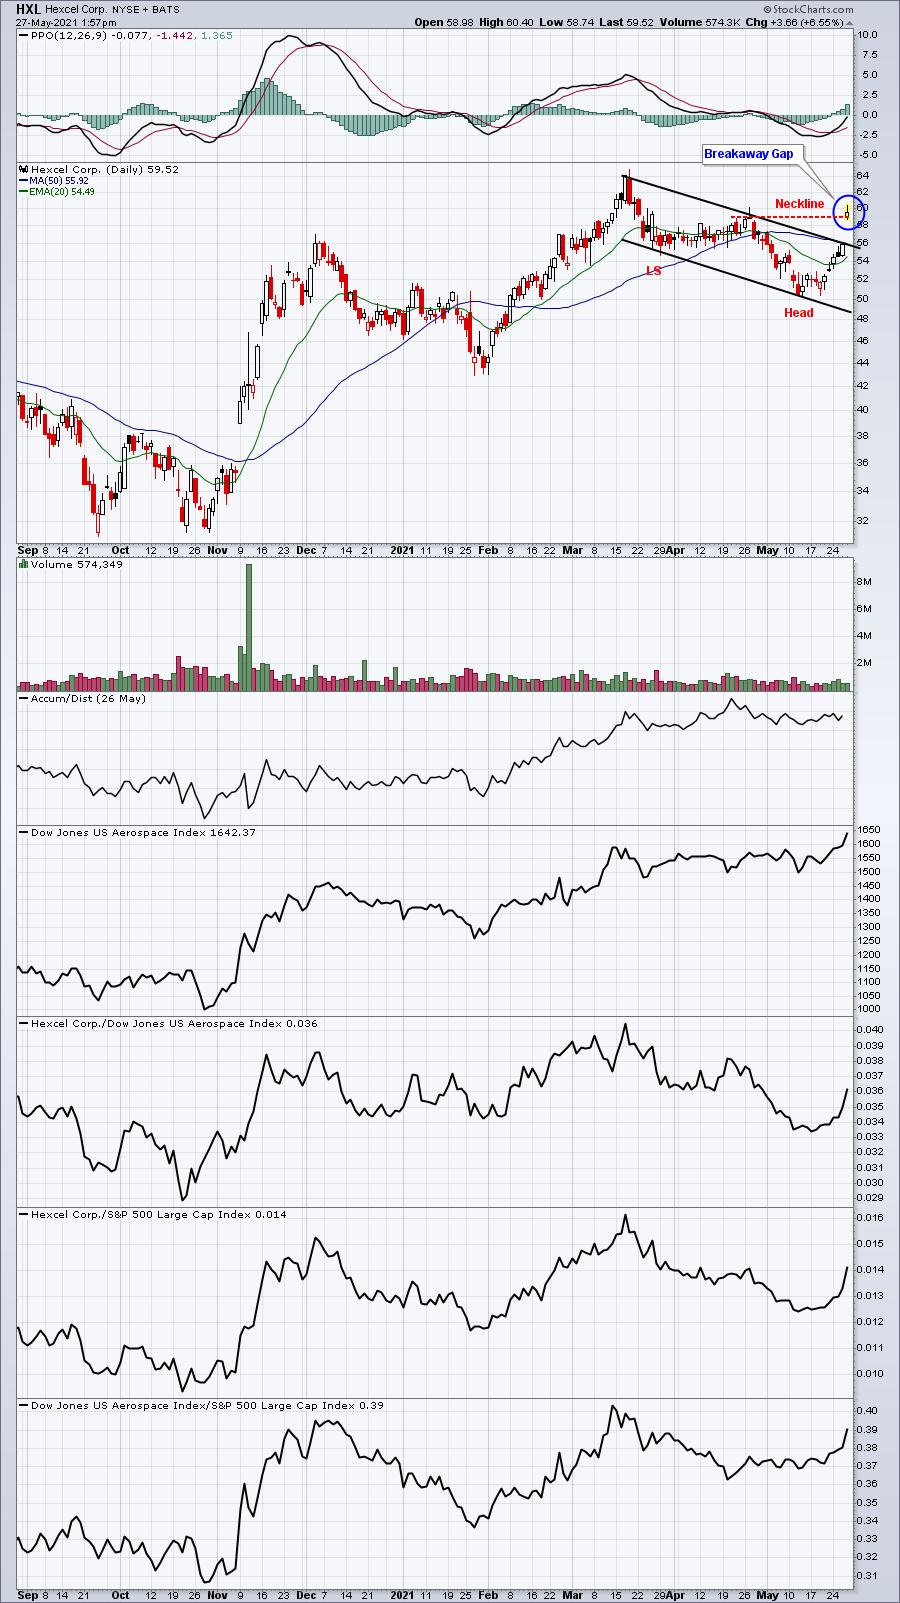
I see one of two likely courses here.....and both are bullish. The breakaway gap could result in continuing strength ahead with little or no pullback until HXL reaches its previous high. The second scenario involves a possible inverse head & shoulders bullish continuation pattern. If we finish weak today, I could see today's action establishing the right side of a neckline. In that scenario, a trip back to the 55-56 area to set the inverse right shoulder would be expected. That would be the best reward to risk level for entry.
ATRO:
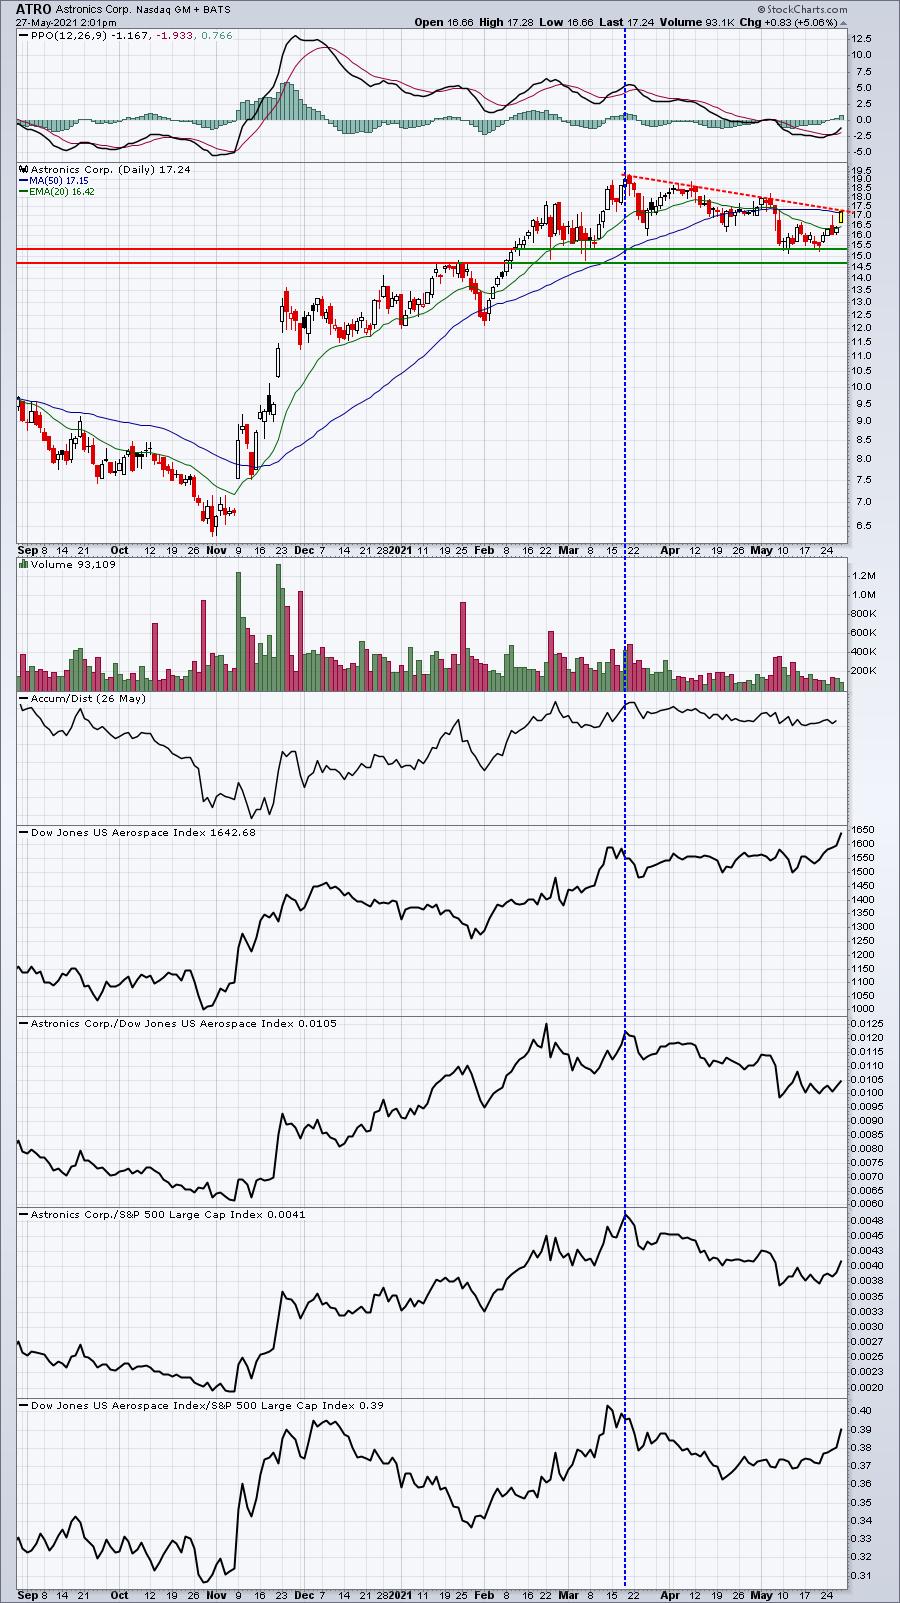
The blue-dotted vertical line marks the top on ATRO and it was a leader in the DJUSAS at that point. It's since been consolidating. If volume picks up into the close today and it can break that downtrend line (red-dotted line), I believe it would lead to further gains.
Outside of our ChartLists, one aerospace stock that really looks solid technically is TDG, which is breaking out of a lengthy sideways consolidation period:
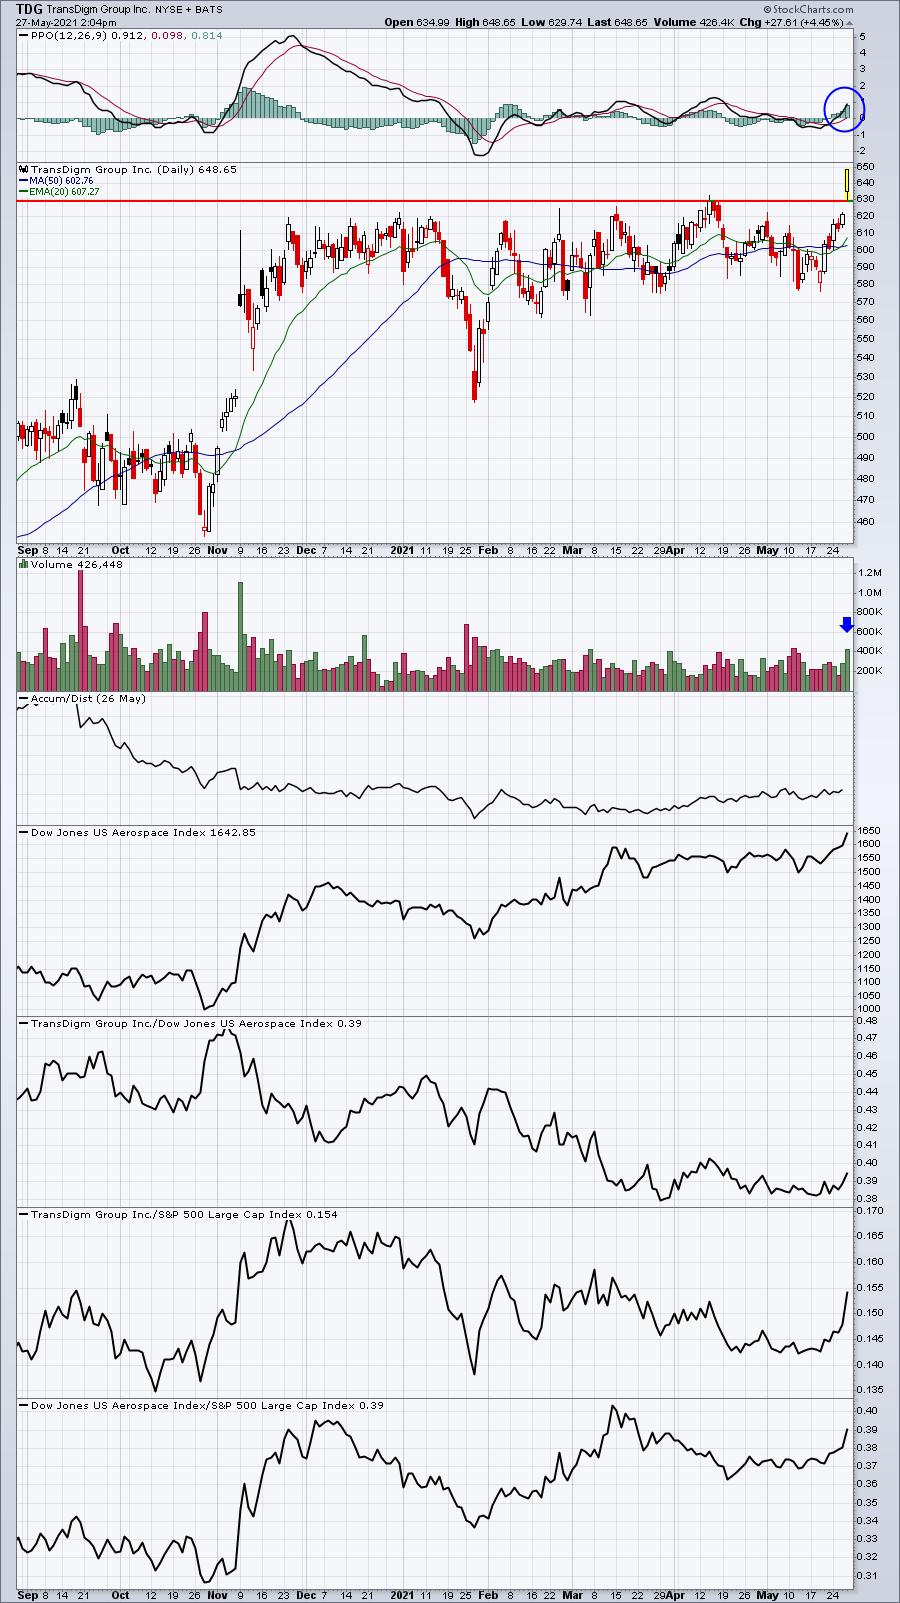
Volume is likely to be TDG's highest over the past 3-4 months, confirming this breakout. While an ensuing 20-day EMA could be seen at any time - and I'd be a buyer there for sure - I really believe we're starting a more lengthy uptrend on TDG.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, May 27:
CRM, MDT, COST, RY, TD, DELL, VMW, ADSK, CM, DG, HPQ, VEEV, BBY, DLTR, BURL, ULTA, GPS, ATHM, PLAN, ASND, OLLI, BOX, DOMO, GES, YEXT
Friday, May 28:
BIG, HIBB
Economic Reports
April durable goods: -1.3% (actual) vs. +0.7% (estimate)
April durable goods ex-transports: +1.0% (actual) vs. +0.7% (estimate)
Q2 GDP (2nd estimate): 6.4% (actual) vs. 6.5% (estimate)
Initial jobless claims: 406,000 (actual) vs. 450,000 (estimate)
April pending home sales: -4.4% (actual) vs. +2.0% (estimate)
Happy trading!
Tom