
EB Daily Market Report - Thursday, June 3, 2021
Annual Spring Special
Our Spring Special, which is our best annual deal of the year, is underway! There's not a better time to extend your current membership. At the current rate of $997 for 14 months (2 bonus months), your monthly cost is 52% below our regular published monthly rate. It won't get any better than this, so please hurry. Our special will end on Tuesday, June 15th. We appreciate your loyalty and support.
For more information, CLICK HERE.
Executive Market Summary
- Futures moved lower overnight and many of the meme stocks reversed after AMC Entertainment (AMC) announced plans for a secondary stock offering
- The May ADP employment report was expected to be strong, but it came in even stronger than expected; the market watches the nonfarm payrolls report more closely, however, and that's due out Friday morning
- Financials (XLF, +0.82%) are the best performing sector as the 10-year treasury yield ($TNX) has climbed 4 basis points to 1.63%
- Investment services ($DJUSSB, +1.07%) is a strong area within financials as Goldman Sachs (GS, +1.80%) is the best performing Dow Jones component stock
- Technology (XLK, -0.68%), the worst performing sector over the past 3 months, is struggling again as INTC, CRM, and AAPL are the 3 primary laggards on the Dow Jones
- The IWF:IWD (growth vs. value) is nearing a key support level from 1.54-1.55; watch to see if this ratio breaks down ahead of key inflationary data over the next 1-2 weeks
- Gold ($GOLD, -2.00%) and silver ($SILVER, -2.83%) are both having weak sessions as the dollar (UUP, +0.68%) strengthens
Market Outlook
While I'm not seeing any MAJOR sell signals flashing, I honestly just don't like the behavior on the S&P 500 right now:
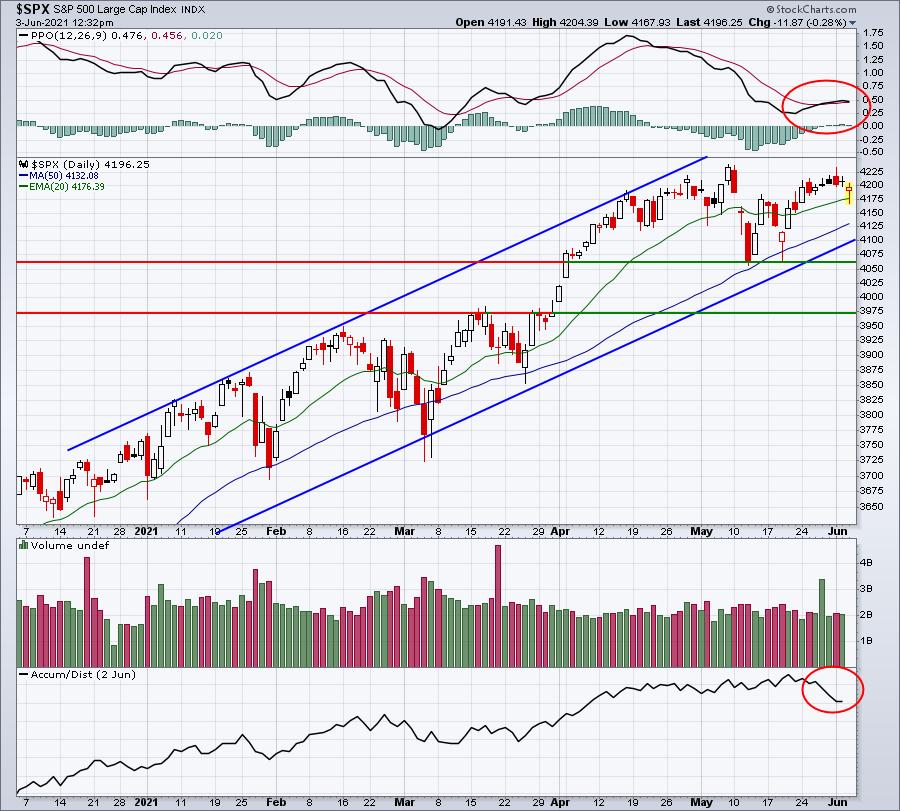
The AD line is weakening, despite the S&P 500's recent consolidation just beneath its all-time high. Also, the PPO is barely bouncing even though it rebounded 160-170 points during the second half of May. It just seems like this stage of the secular bull market advance is a bit tired.
We should see a very solid jobs report tomorrow morning. Today's ADP employment was much stronger than expected, yet the stock market sold off. It's also important to keep an eye on the IWF:IWD ratio, which has dropped in recent days to 1.5625 earlier today. 1.54-1.55 is excellent support, so if you see this ratio beginning to move beneath 1.54, another leg lower for growth stocks would appear likely.
Sector/Industry Focus
The last time the Volatility Index ($VIX) spiked to the 80-90 range in 2009, it bounced when it hit the 15 level after a long and steady decline. I know that's not a big sample of data, but the VIX does look similar now:
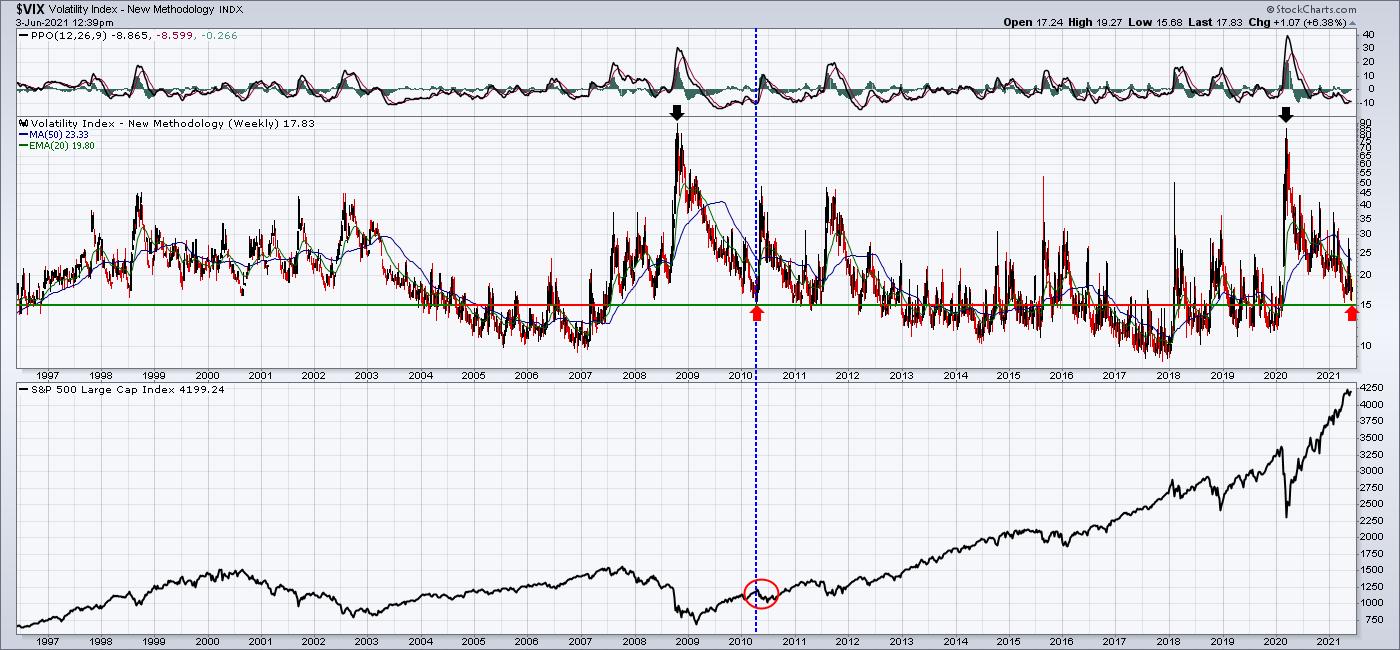
I don't know that we'll see the VIX spike into the 40s as we did then, but I am nervous short-term with the inflation data coming out next week. I've discussed on several previous occasions that I believed the inflation story would be the next subject that pressures the bulls. We already saw a glimpse of that last month and I expect to see inflation numbers that are higher than last month's.
ChartLists/Strategies
I would suggest simply keeping tight stops in play for the moment. I'm going to avoid the temptation to offer up trading ideas because, quite simply, I'm nervous about the market near-term. There's nothing really that suggests we'll see a huge drop, but we've been consolidating just beneath a key breakout on the Dow Jones and S&P 500 without the ability to actually make the breakout. Next week historically is a week of selling and we'll kick off two more key inflation reports on Thursday when the May CPI is released. I think if I were to trade, I'd look at financials, energy, and health care, and avoid the more aggressive technology names. From a reward to risk perspective, the XLV (health care ETF) is testing its 50-day SMA. That area might provide solid trades without taking big risks.
I plan to trade a LOT less over the next couple weeks as the Fed meets and we see those inflation reports, which will likely produce shocking headline numbers. I wouldn't be surprised to see professionals exiting some of the growth names that had decent runs of late as we approach the inflation reports and Fed meeting.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, June 3:
AVGO, CRWD, LULU, DOCU, WORK, COO, MDB, SJM, TTC, FIVE, CIEN, SAIC, PHR, SCWX, ZUMZ
Friday, June 4:
None
Economic Reports
May ADP employment report: 978,000 (actual) vs. 650,000 (estimate)
Initial jobless claims: 385,000 (actual) vs. 400,000 (estimate)
Q2 productivity (2nd estimate): 5.4% (actual) vs. 5.5% (estimate)
May PMI composite: 68.7 (actual) vs. 68.1 (estimate)
May ISM services index: 64.0 (actual) vs. 63.1 (estimate)
Happy trading!
Tom