
EB Daily Market Report - Wednesday, June 16, 2021
Spring Special Extended ONE DAY
We decided at our June Max Pain event last night, which was awesome, that we'd extend our Spring Special one more day. The Spring Special provides 14 months of membership (two bonus months!) for $997, 52% off the regular monthly rate of $147. For more information, CLICK HERE!
Executive Market Summary
- Futures were relatively flat this morning, with NASDAQ showing a bit of relative strength
- All of our major indices are lower as we await the FOMC policy statement, though the NASDAQ's slight relative strength advantage today continues
- Oracle Corp (ORCL, -4.76%) beat revenue and EPS estimates, but gapped down at the opening bell; it is trading well off earlier lows
- Cryptocurrencies are down today, mostly in the 3%-5% range
- Crude oil ($WTIC) is flat after a torrid advance recently, while copper ($COPPER, +1.03%) is rebounding from its recent selloff
- Real estate (XLRE, +0.20%) and health care (XLV, +0.17%) are the best performing sectors
- Financials (XLF, -1.10%) are underperforming as the 10-year treasury yield ($TNX) declines a basis point to 1.49% ahead of the FOMC policy statement
- All eyes are on the Fed this afternoon; will they change their wording regarding inflation after May CPI and PPI reports both were hotter than expected
Market Outlook
The Federal Reserve last met to discuss interest rate policy on April 27-28. That was before the last two months' worth of inflation data. So the Fed has now had time to digest much-hotter-than-expected inflation data from April and May at both the consumer and producer levels. They're on record expecting inflation to be higher, but have stated in the past that they expect it to be transitory, or short-term in nature. They've explained their expectation based on base level effects and temporary supply chain disruptions. Personally, I don't believe much has changed, so I fully expect the Fed to stick with their prior statements. If they do, and with recent economic reports much lower than expected, traders are likely to pour into bonds, driving yields lower. That, in turn, would bode very well for consumer discretionary stocks (XLY) and technology stocks (XLK). Here's the current 10-year treasury yield ($TNX) picture from a long-term weekly perspective:
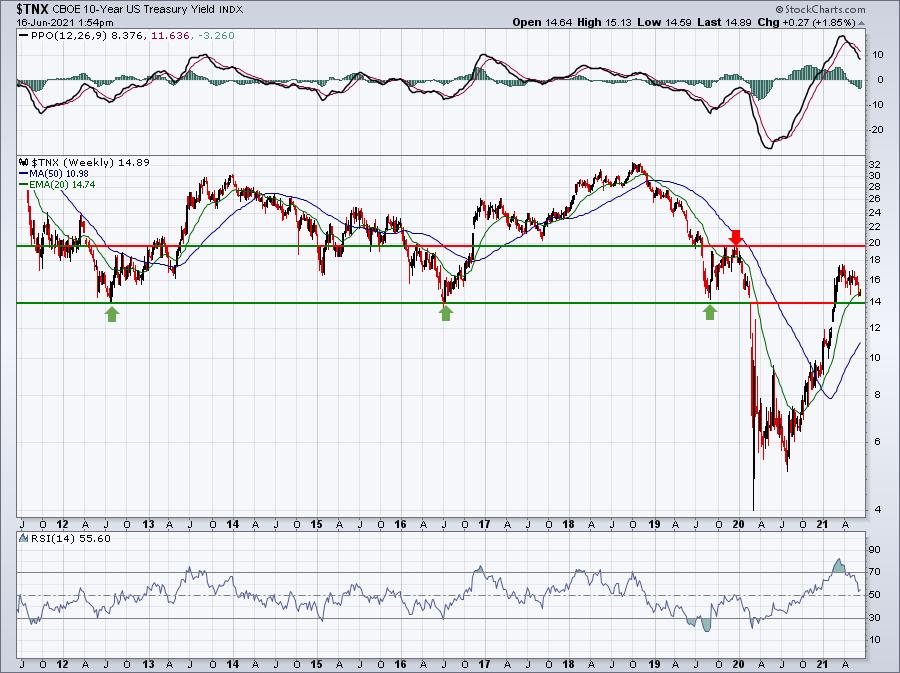
I would expect our more intermediate-term range to be from 1.40% to 2.00%, but if the Fed says inflation is not a problem, and the TNX dips below 1.40%, it'll be GAME ON for growth stocks in technology and consumer discretionary.
Sector/Industry Focus
Growth stocks (IWF) have been outperforming value stocks (IWD) in June, ignoring the headline inflation news that would seem to suggest that inflation is soaring. I'm always interested in the IWF:IWD ratio, but never more so than this afternoon after Fed Chief Jay Powell explains the Fed's latest stance. Here's where this ratio stands as we approach the 2pm ET announcement:
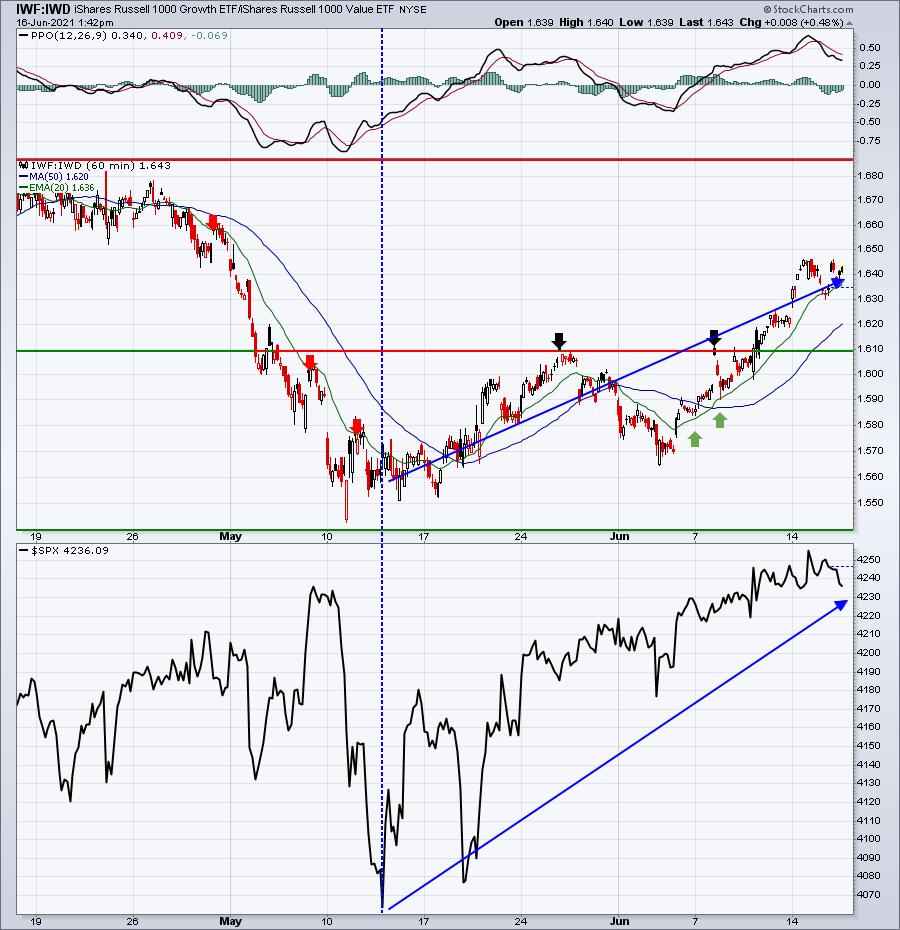
This ratio has been advancing ever since the April inflation data was released in the second week of May. That is a clear signal that Wall Street is ignoring headline inflation news. Will the Fed give Wall Street something to worry about? My guess is no, but who knows?
ChartLists/Strategies
I believe it's too risky to do too much right now. I think max pain provides us a few opportunities, but otherwise, it all boils down to the Fed's outlook with respect to inflation and how the market reacts to their position. So let's wait a day and allow the market to settle down before considering new trades.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, June 16:
LEN
Thursday, June 17:
ADBE, KR, JBL, CMC, SWBI
Economic Reports
May housing starts: 1,572,000 (actual) vs. 1,630,000 (estimate)
May building permits: 1,681,000 (actual) vs. 1,738,000 (estimate)
FOMC meeting policy statement to be released at 2:00pm ET
Happy trading!
Tom