
EB Daily Market Report - Tuesday, July 13, 2021
Today's Event
At 4:30pm ET today, I'll be hosting our "July Max Pain" webinar. This is designed to provide us directional clues heading into options-expiration Friday. Erin Webber will be providing a brief tutorial on how to calculate max pain using our new Excel tool, so this should be something to look forward to if you're interested in calculating max pain on any stocks you own. It should be a highly educational webinar. We'll make sure that a recording is sent out to everyone in the event you're unable to attend.
Here's the room link if you need it (the room will not open until 4:00pm ET):
https://earningsbeats.zoom.us/j/82352783826
Executive Market Summary
- Futures were slightly lower after June CPI came in much-hotter-than-expected at 0.9%
- Rotation has been wild today, highlighted by a chart below in the "Market Outlook" section
- Cryptocurrencies continue to drift lower, led by etherium, which is lower by nearly 3%
- Most commodities are lower, though crude oil ($WTIC) is up roughly 1.5%
- Earnings season is now officially underway as every key earnings report today was better than expected
- Goldman Sachs (GS, -0.83%) reported exceptionally strong earnings, 15.02 vs. 9.90, yet the stock is down - buy on rumor, sell on news
- Given the inflationary news, technology (XLK, +0.44%) surprisingly is the only sector in positive territory
- Financials (XLF, -0.97%), generally higher with higher treasury yields, is struggling on the session
- Conagra (CAG, -5.36%), citing inflationary pressures, lowered their guidance and is the worst performing S&P 500 stock
Market Outlook
Well, we saw yet another shocking inflationary report as the June CPI soared past expectations, +0.9% vs. +0.5%. June Core CPI came in with the same numbers, so the surge cannot be blamed simply on rising crude oil or food prices. If inflation is truly a big problem, one key reaction should be surging treasury yields (to anticipate Fed action to raise rates). Those potential rising rates would then result in a selloff of growth stocks.
The whipsaw today in both treasury yields and the growth vs. value stock ratio (IWF:IWD) summarizes almost perfectly how treacherous rotation is in the market right now. There is quite a battle taking place between professionals. They're putting money to work in U.S. equities, driving prices higher, but leadership seems to change about as often as the wind blows, making short-term trading extremely difficult. The big picture in U.S. equities remains quite bright, in my opinion, as I don't believe inflation will present a long-term challenge. But feel free to disagree, that's what makes a market.
Let's look at the 10-year treasury yield ($TNX) today, along with performance between growth (IWF) and value (IWD):
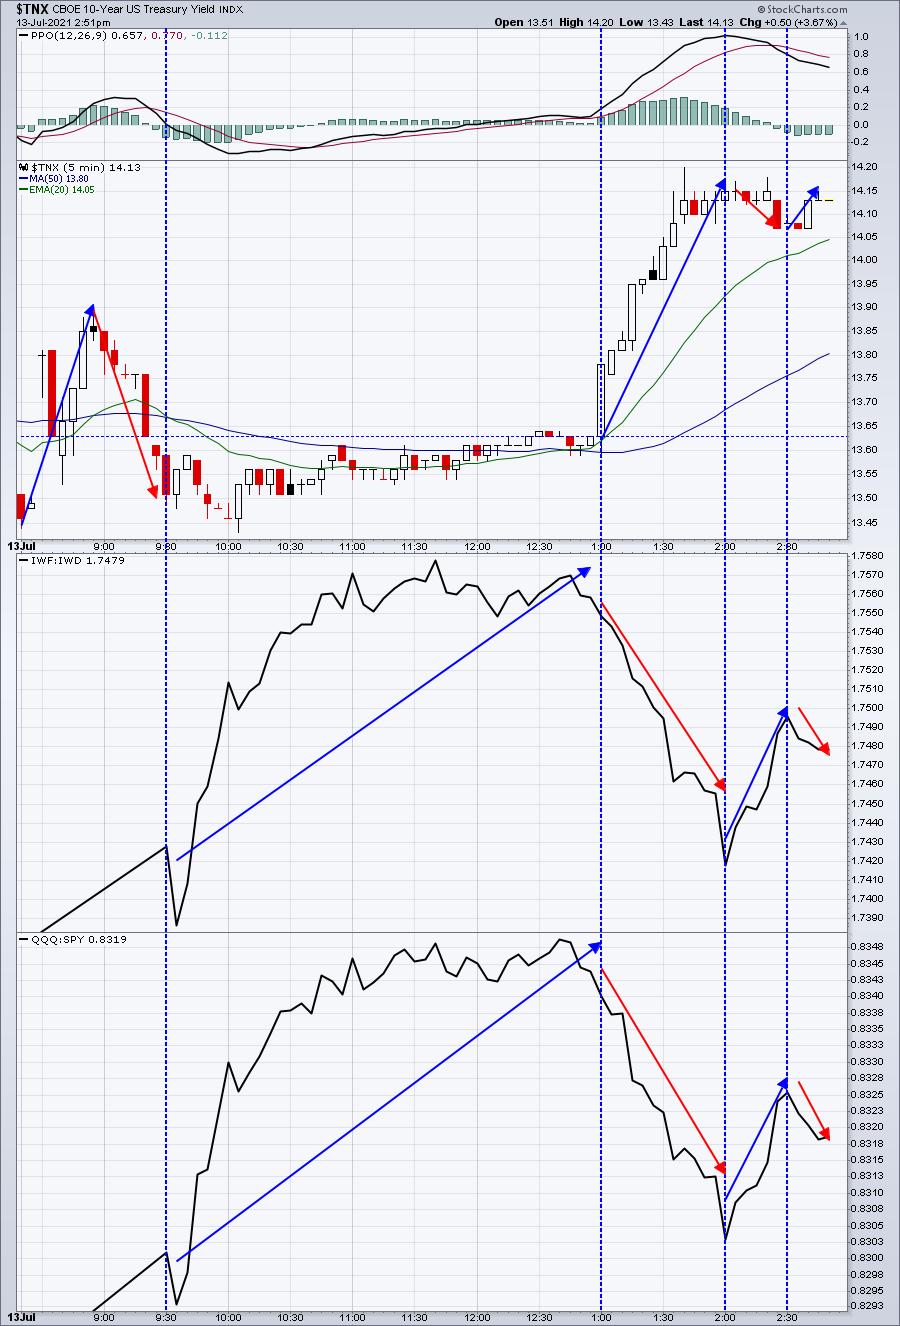
This has been like four days in one as far as rotation is concerned. The TNX initially spiked when the CPI data was released at 8:30am ET. By 9:30am ET, however, the TNX had returned back to its flat line, providing a green light for growth stocks as the yield remained relatively flat for 3-4 hours. However, once the TNX began surging around 1:00pm ET, growth stocks fell out of bed. Not only did we see the IWF:IWD ratio falling apart, but check out the QQQ:SPY ratio. NASDAQ stocks completely turned around. But then, after 1 hour relative selloff in growth, the growth bulls returned and we saw money shift once again, this time lifting growth stocks. In the past 15-20 minutes the tide has shifted once again.
Let's also keep in mind that this is options-expiration week, adding to the utter confusion. So what's going to lead the rest of the afternoon and into Friday options expiration? Anyone have a coin I can flip?
Sector/Industry Focus
Soft drinks ($DJUSSD, +1.63%) are having a strong session after Pepsi (PEP, +2.37%) delivered an excellent quarter today before the bell, beating both revenue and EPS estimates. While the DJUSSD is attempting an absolute breakout, there's still plenty of work to be done to begin a relative uptrend vs. the benchmark S&P 500. It may take more strength from Coca Cola (KO, +1.17%) to provide the impetus to start that relative uptrend:
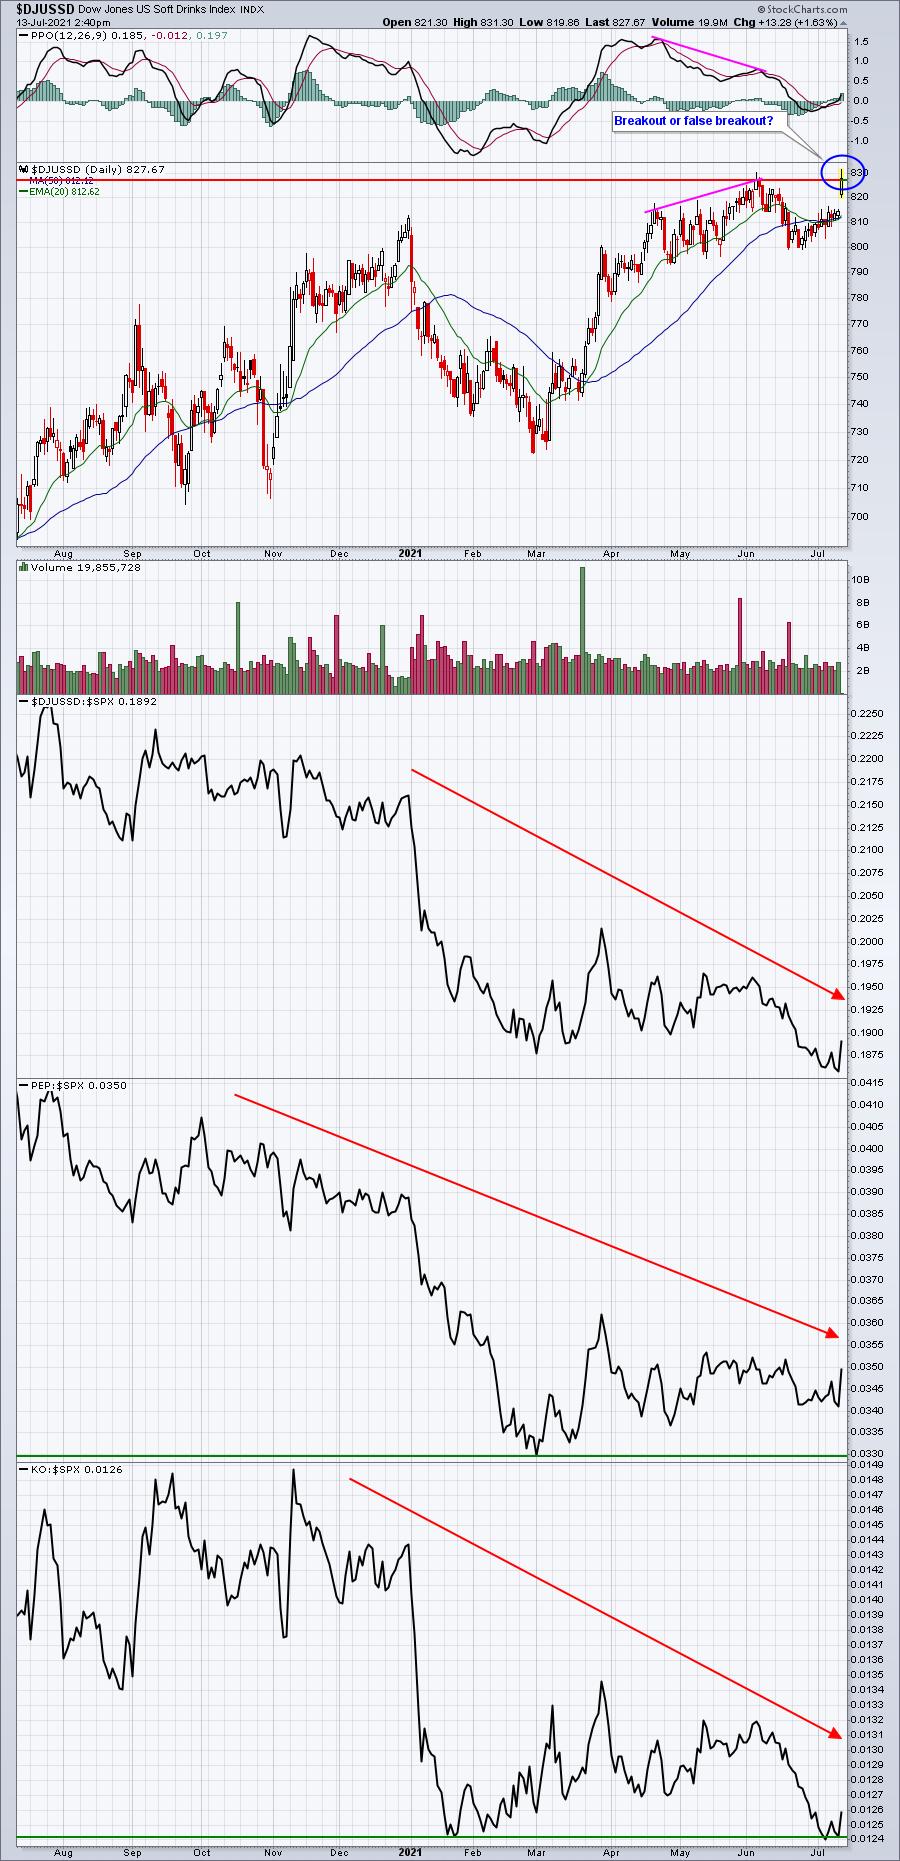
KO has printed a double relative bottom and is starting to bounce off it. That will likely need to continue if the DJUSSD is to see a price breakout. PEP has performed better than KO, but it too has been downtrending on a relative basis.
ChartLists/Strategies
Later today, I'll be discussing July Max Pain, which is intended to provide us another tool to help with short-term market direction. Any time the stock market is at an all-time high heading into options expiration week, the risk of a short-term selling episode increases. We've already seen that to some extend this afternoon. One stock that could be heavily manipulated this week (and perhaps into next week) is Nokia Corp (NOK):
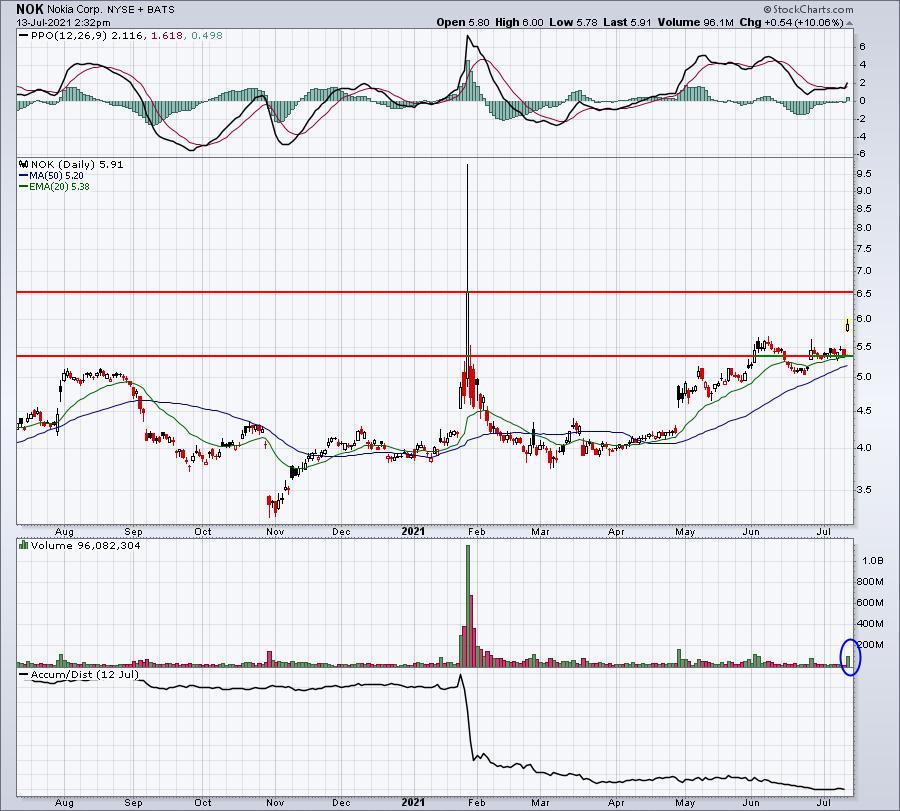
NOK's max pain is 4.73. As we know, that provides no guarantee whatsoever that NOK will lose ground over the next few days, but it warns us of a potential risk of being long a stock like this. There's financial incentive for market makers to drive NOK's price lower as options expire later this week.
We'll be discussing 10 max pain candidates later today, including both the SPY and QQQ.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Tuesday, July 13:
JPM, PEP, GS, FRC, FAST, CAG, ANGO
Wednesday, July 14:
BAC, WFC, C, BLK, INFY, PNC, DAL
Economic Reports
June CPI: +0.9% (actual) vs. +0.5% (estimate)
June Core CPI: +0.9% (actual) vs. +0.5% (estimate)
Happy trading!
Tom