
EB Daily Market Report - Tuesday, July 27, 2021
Executive Market Summary
- Futures were lower, but there's been serious selling since the opening bell
- Today has been the biggest day of distribution since this rally began in May
- Most commodities are lower, despite the U.S. dollar (UUP) falling below its rising 20-day EMA for the first time in 7 weeks
- Meanwhile, the 10-year treasury yield ($TNX) is down 4 basis points, digesting a big slate of economic news
- The Fed has begun its 2-day meeting and part of today's selling of growth stocks could be ahead of the Fed's take on inflation and what impact it might have on its policy statement to be released on Wednesday 2pm ET
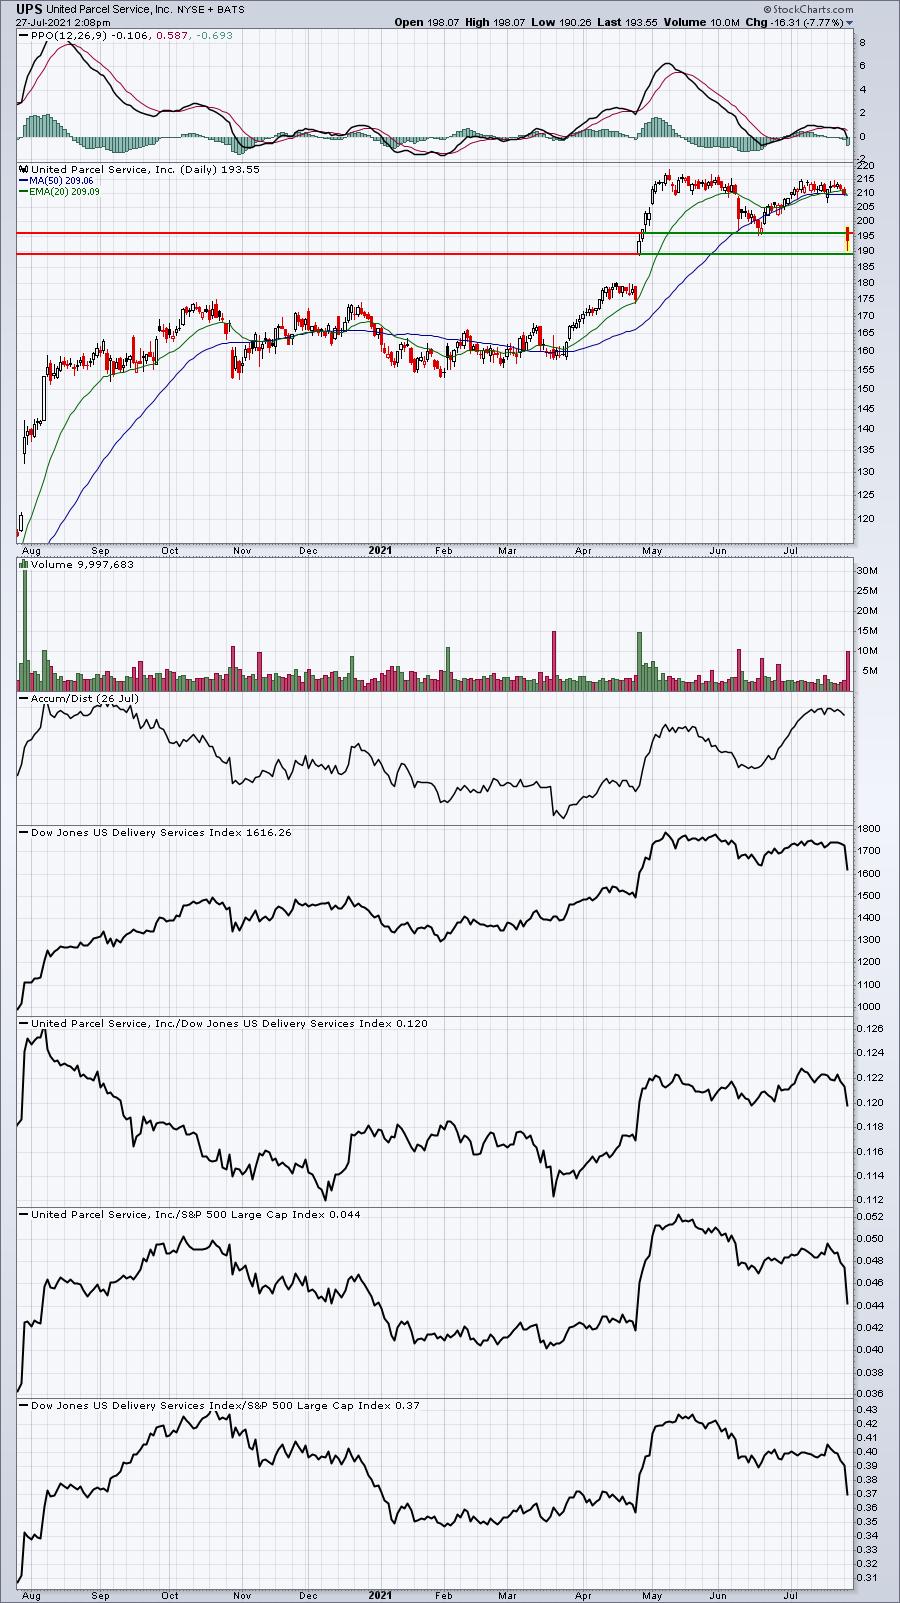
- United Parcel Service (UPS, -7.94%) and Tesla (TSLA, -3.69%) both beat revenue and EPS estimates, but both are considerably lower on the session
- Defensive sectors are leading today's action, which is to be expected when selling accelerates; energy (XLE, -1.81%) is the worst performer
Market Outlook
We know from history that the stock market's biggest gains typically occur as we head into earnings season (buy on rumor) and then the market tends to struggle more as the news hits (sell on news). Today, we're seeing a bit of that. Yes, it's been a bad day for many areas of the stock market, particularly growth stocks. I would not, however, read too much into it. The long-term bullish picture remains unchanged, but unless we see an afternoon rally, the distribution today looks likely to continue in the very near-term. Check out this NASDAQ daily chart:
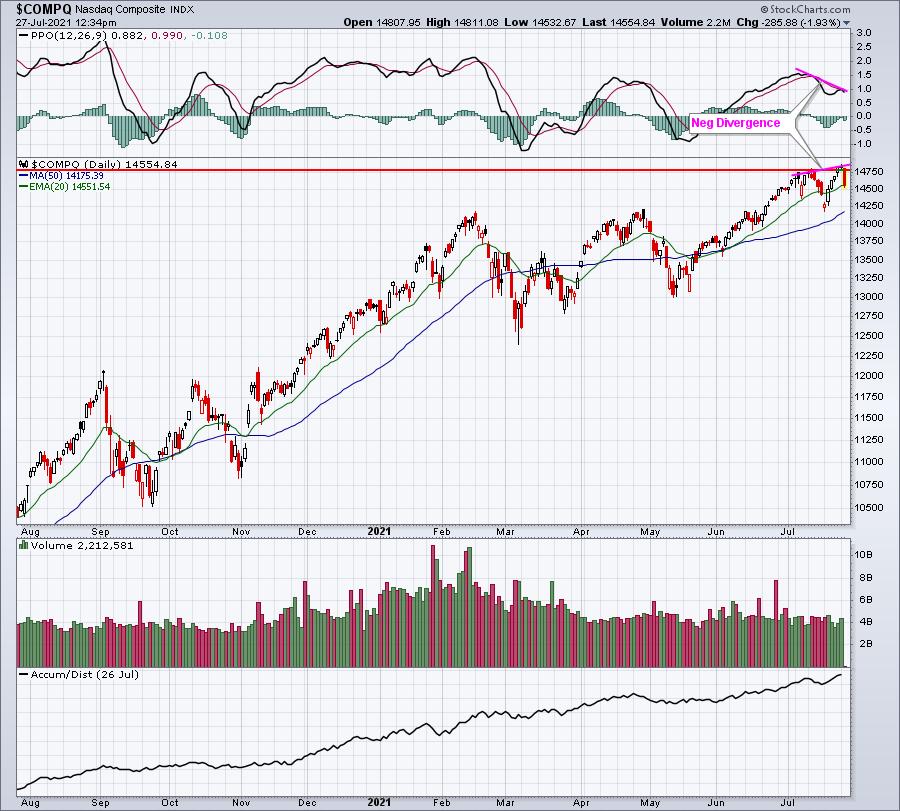
When I see a negative divergence and a failed breakout, I start considering the possibility of a 50-day SMA test and/or a PPO centerline test. That wouldn't be anything horrible, but short-term could certainly impact a trader's portfolio.
Sector/Industry Focus
Utilities (XLU, +1.69%) are clearly benefiting from the renewed fear in the market today, but just remember that absolute strength is a completely different animal than relative strength. The XLU has bounced off recent lows, but the sector remains under a lot of relative pressure:
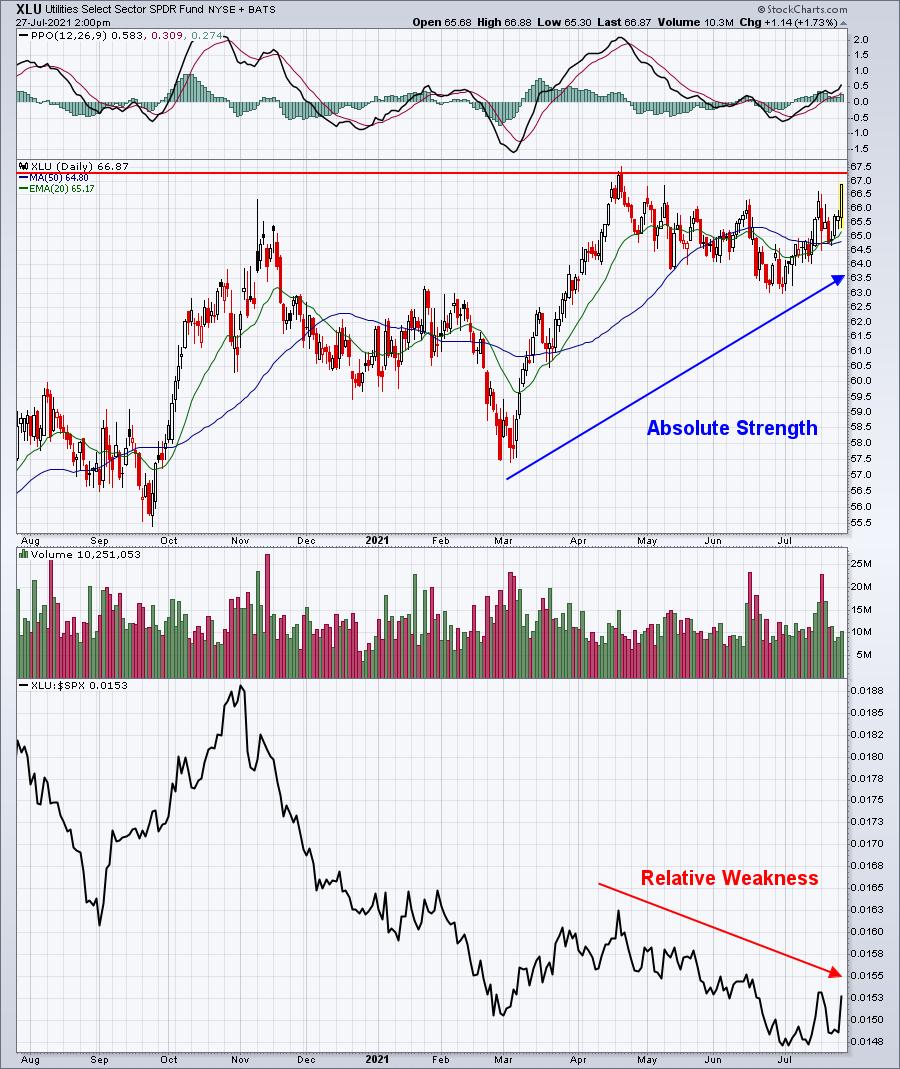
In a secular bull market, you want to be UNDERweight utilities as the sector tends to deliver subpar performance, which is exactly the case over the past year.
ChartLists/Strategies
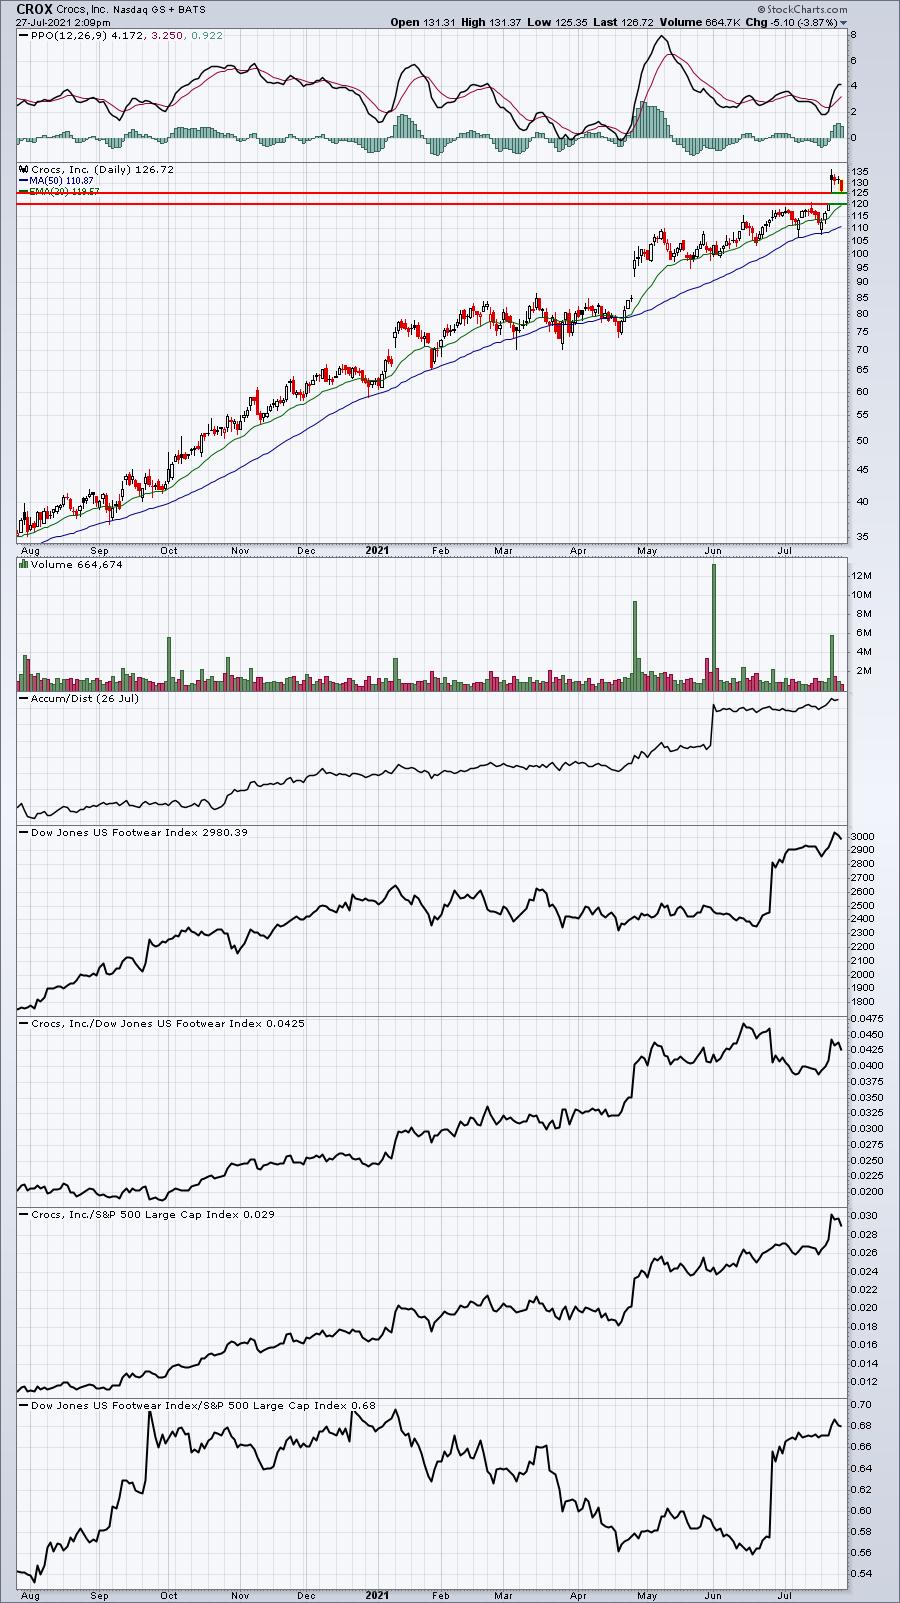
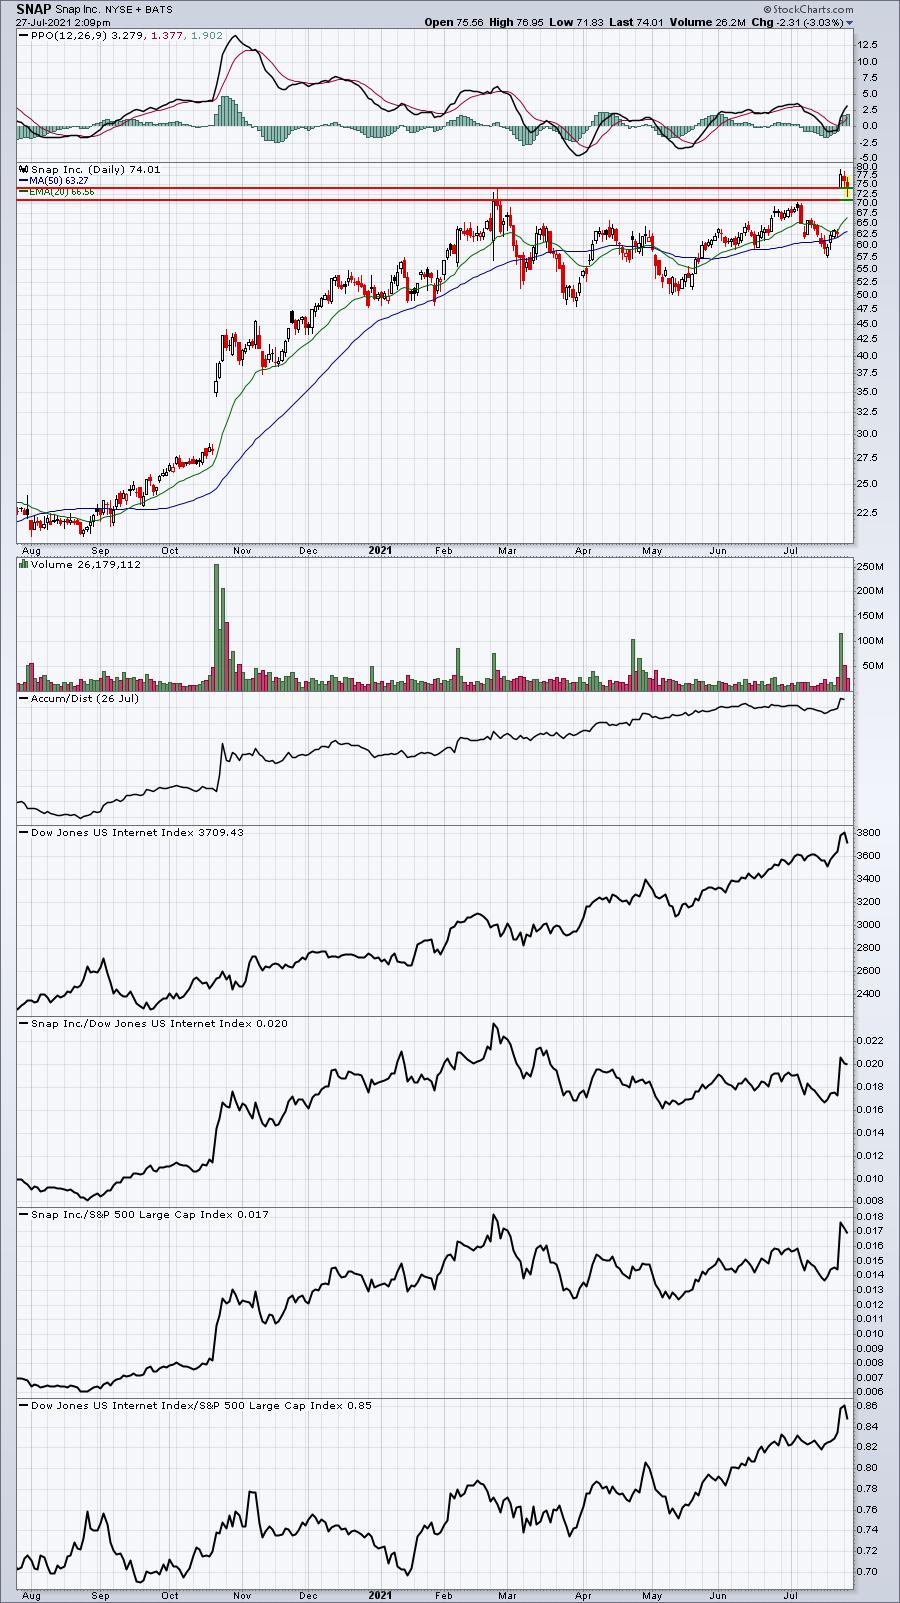
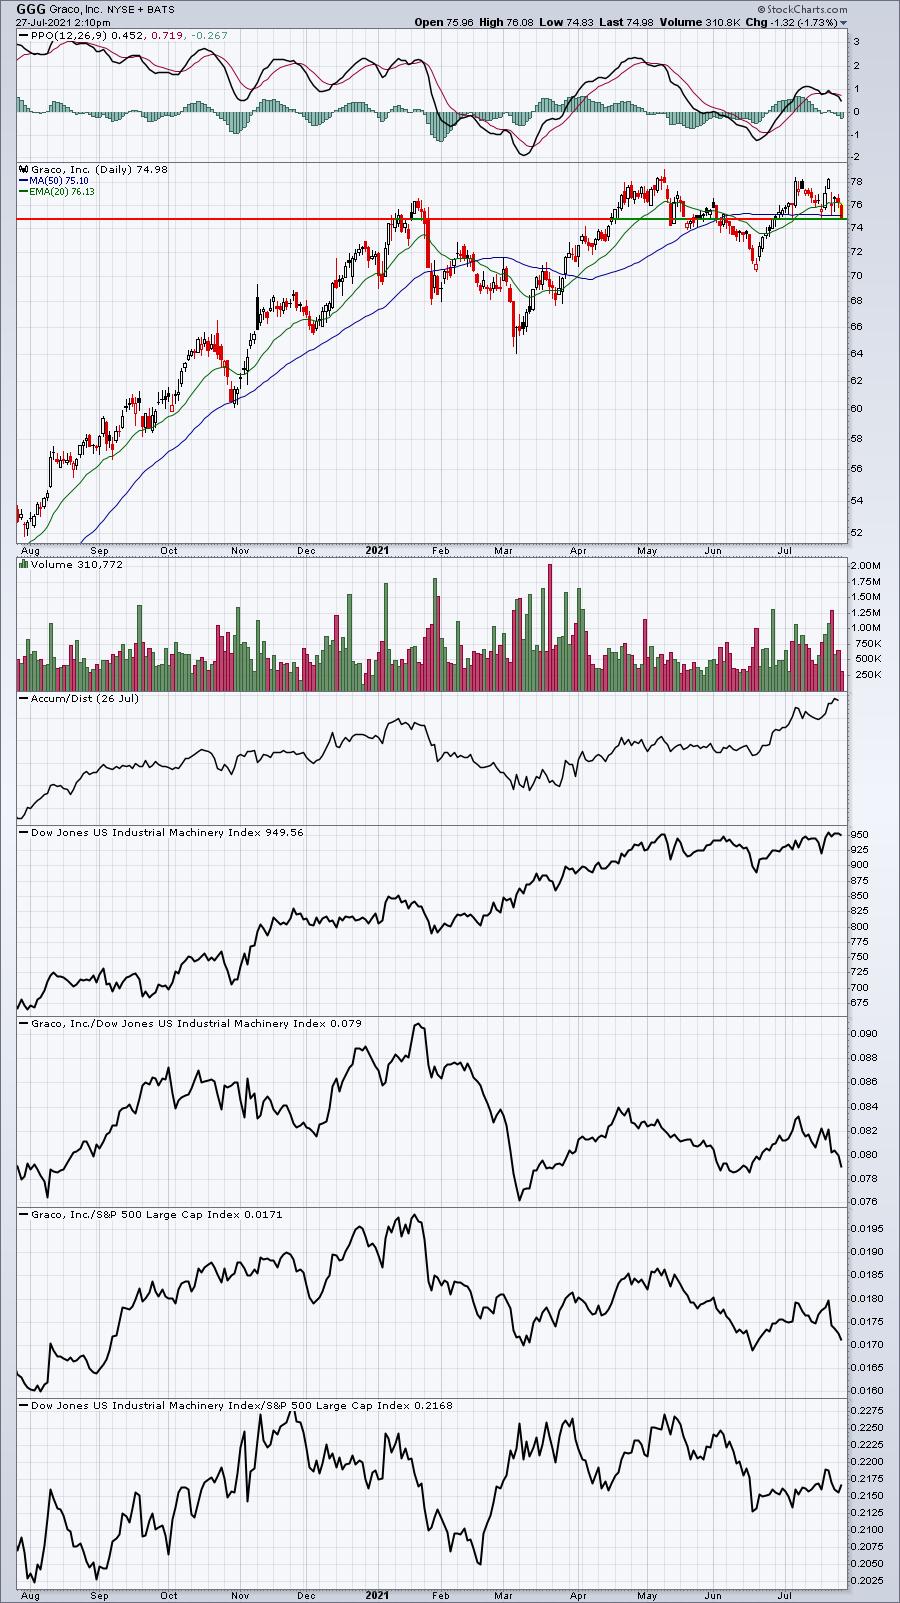
Here are a few key support levels being tested on recent earnings winners (stocks on our SECL):
UPS:
CROX:
SNAP:
GGG:
TXN:
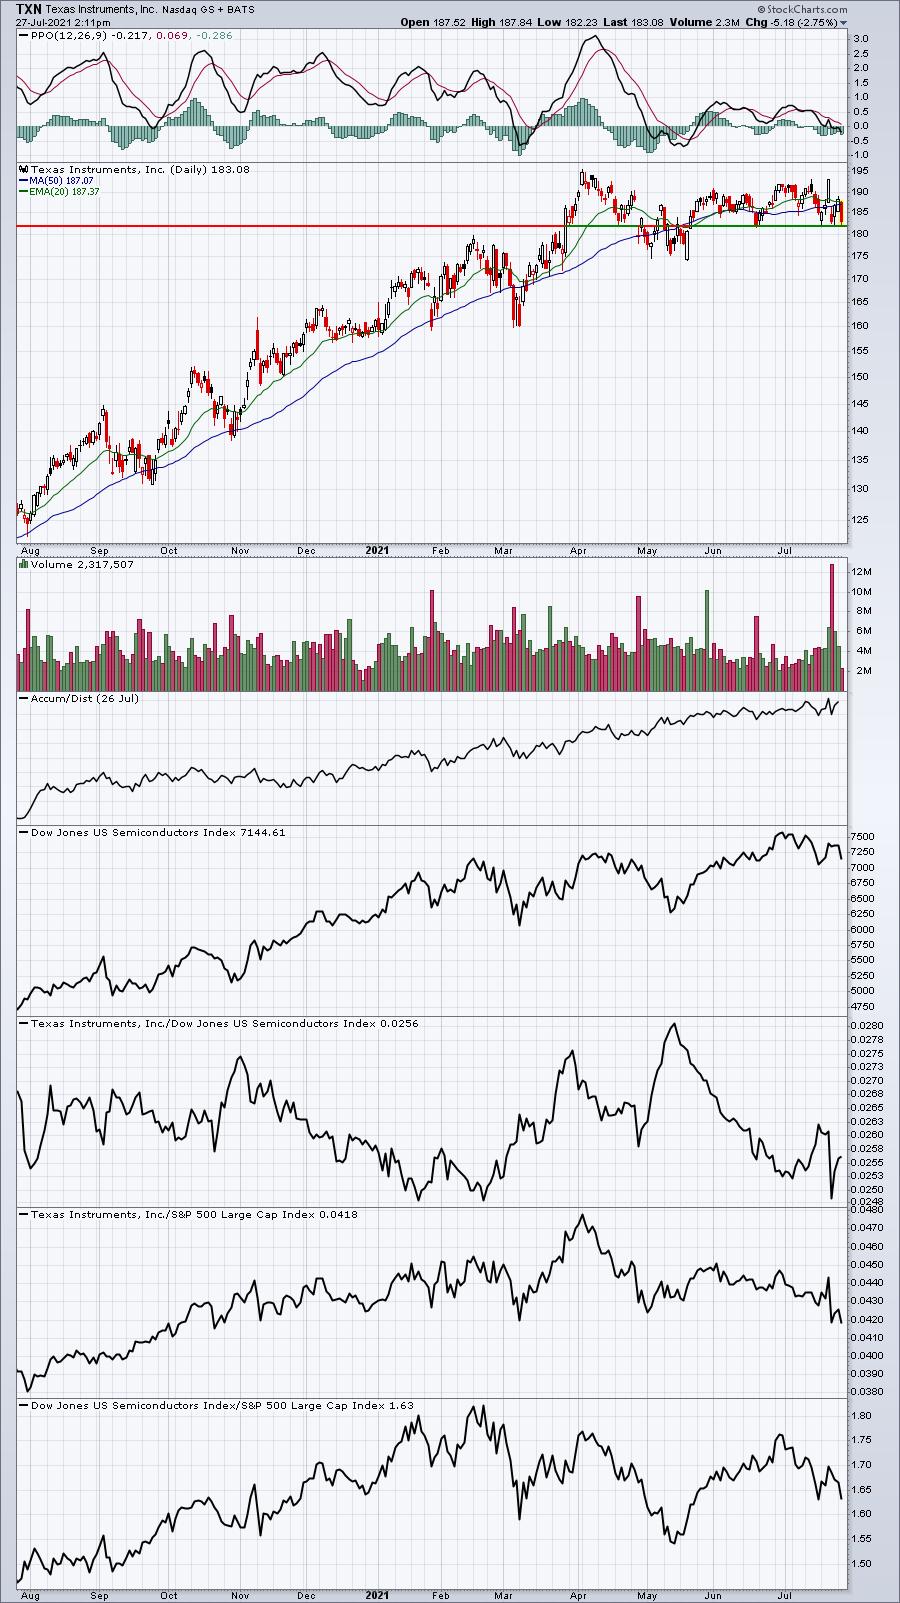
There are no guarantees that these support levels hold, so stops should definitely be considered. However, we know that these companies all beat Wall Street estimates within the past few months and I believe pullbacks represent opportunities to accumulate.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Tuesday, July 27:
AAPL, MSFT, GOOGL, V, UPS, SBUX, RTX, MMM, GE, AMD, SYK, MDLZ, CB, SHW, FISV, BSX, ECL, WM, MSCI, IQV, CNC, CSGP, ROK, GLW, SWK, ADM, EQR, PCAR, SIRI, MXIM, ENPH, TDOC, EXR, DTE, TRU, TER, MPWR, BXP, IEX, PFG, ENTG, NLOK, MASI, PHM, VIV, CHRW, SID, IVZ, PNR, RGEN, TECK, LW, HUBB, QS, MANH, JNPR, PII, EHC, MLCO, BYD, JBLU, TENB, XRX, SSTK, FELE, MTDR, CVLT, NAVI, CAKE, LBRT, AUDC, IMAX
Wednesday, July 28:
FB, PYPL, PFE, TMO, SHOP, MCD, QCOM, BMY, BA, NOW, GSK, LRCX, ADP, CME, EQIX, MCO, NSC, EQNR, HUM, F, GD, EPD, ALGN, CP, TEL, SPOT, ORLY, APH, BCS, CTSH, AFL, XLNX, AVB, SU, ODFL, GRMN, FMX, GNRC, YUMC, CAJ, YNDX, URI, INVH, HES, GIB, UMC, HIG, MAA, IR, TYL, EXAS, SSNC, DRE, ROL, CINF, HOLX, DT, PTC, RJF, VICI, AVY, TDY, UDR, PPD, XPO, ATUS, ACGL, MOH, AEM, BMRN, FBHS, RE, NLY, PEGA, GFL, KL, BG, OC, TEVA, MKSI, TTEK, CCJ, PAG, SLAB, TLRY, IART, INOV, ASGN, WING, CRUS, ENSG, RRR, MTH, NUVA, HP, IRBT, CLB, OII, EXTR, RBBN, COWN
Economic Reports
FOMC 2-day meeting begins
June durable goods: +0.8% (actual) vs. +2.1% (estimate)
June durable goods ex-transports: +0.3% (actual) vs. +0.8% (estimate)
May Case-Shiller home price index: +1.8% (actual) vs. +1.5% (estimate)
May FHFA house price index: +1.7% (actual) vs. +1.8% (estimate)
July consumer confidence: 129.1 (actual) vs. 124.9 (estimate)
Happy trading!
Tom