
EB Daily Market Report - Monday, September 27, 2021
Executive Market Summary
- Futures were mixed overnight as the NASDAQ got off to a rough start
- Small caps ($SML, +2.35%), however, are having a very nice day - more on this below
- Cryptocurrencies are mostly lower as ethereum ($ETHUSD) falls nearly 2%
- Crude oil ($WTIC, +1.85%) has moved back above $75 per barrel as it works its way back toward major multi-year price resistance at $77-$78
- Rising crude has lifted energy names (XLE, +3.58%), which leads all sectors today
- Financials (XLF, +1.44%) are also quite strong, particularly life insurance ($DJUSIL, +3.03%) and banks ($DJUSBK, +2.55%)
- Meanwhile, health care (XLV, -1.37%) and technology (XLK, -0.77%) are both very weak and weighing on the NASDAQ 100 index ($NDX, -0.59%)
- Weakness in software ($DJUSSW, -1.68%) is contributing to the technology decline
Market Outlook
It's important to recognize the possible implications of new developments as they occur. I've discussed the ramifications of movements in the 10-year treasury yield ($TNX) many times. When the TNX rises, we tend to see the S&P 500, financials, industrials, including transportation, all do the same. One other area that tends to benefit from rising treasury yields is the small cap universe ($SML). Below is a chart of the SML, as it's shown tremendous strength over the past week:
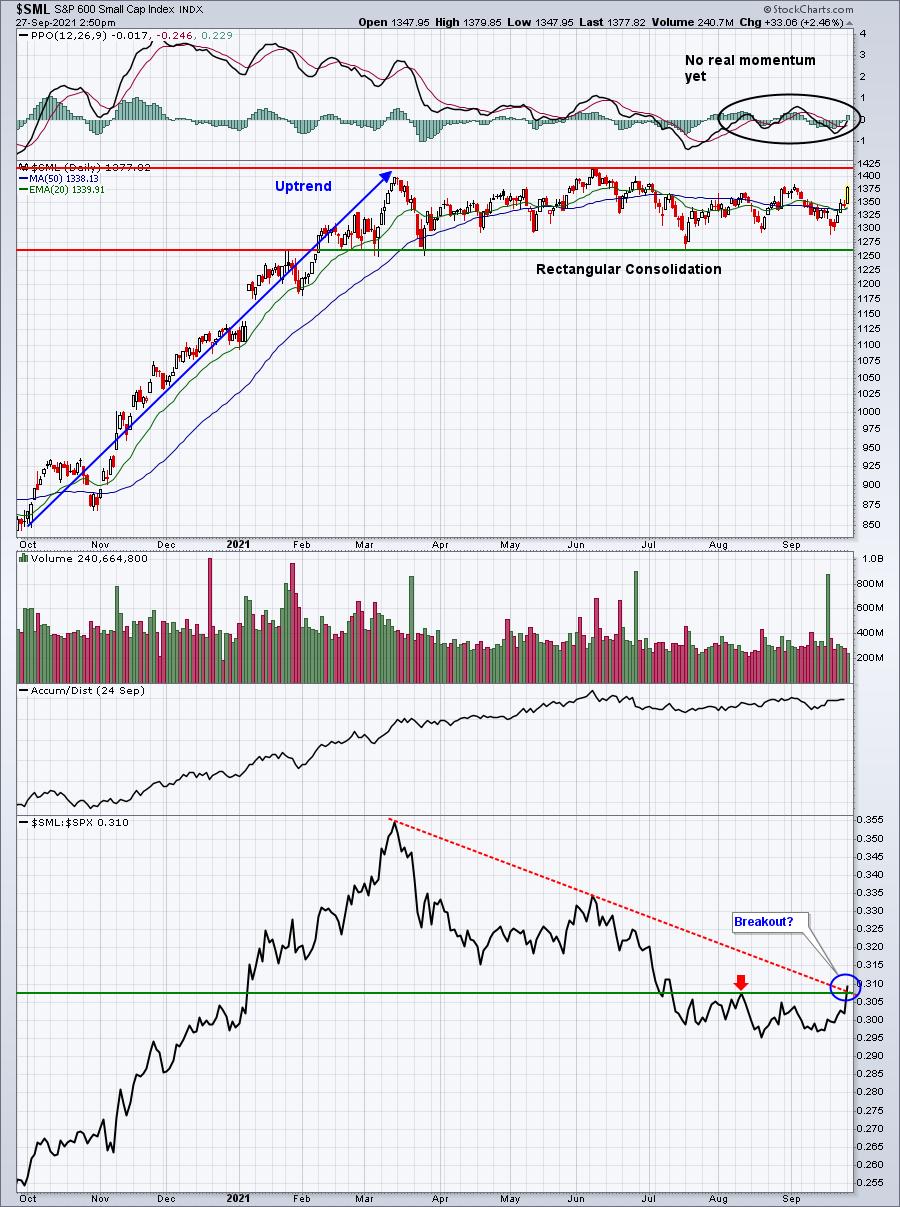
There's definitely reason for hope here. The bottom panel shows that a relative downtrend line AND a relative resistance level are both in the process of being cleared. That is most certainly Step 1 to seeing small caps lead again.
It's also worth pointing out that small caps tend to strengthen in October, and especially in November as you can see from this 9-year seasonal chart below:
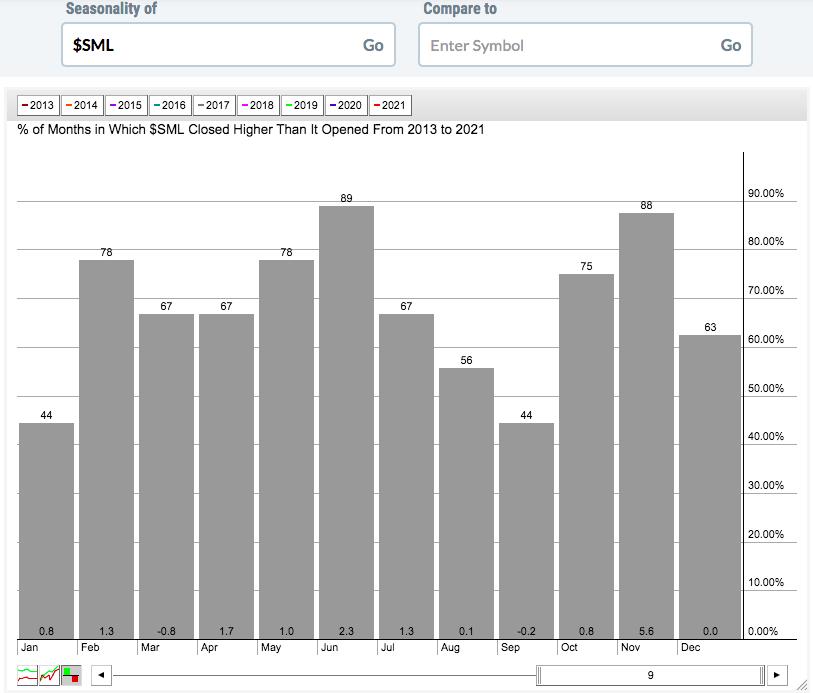
I selected 9 years so that it covers the current secular bull market period, which began in April 2013.
Sector/Industry Focus
Financials (XLF, +1.47%) have shown considerable strength, both absolute and relative, over the past week as treasury yields have soared. The XLF is now on the precipice of a significant absolute breakout above 39. Check this out:
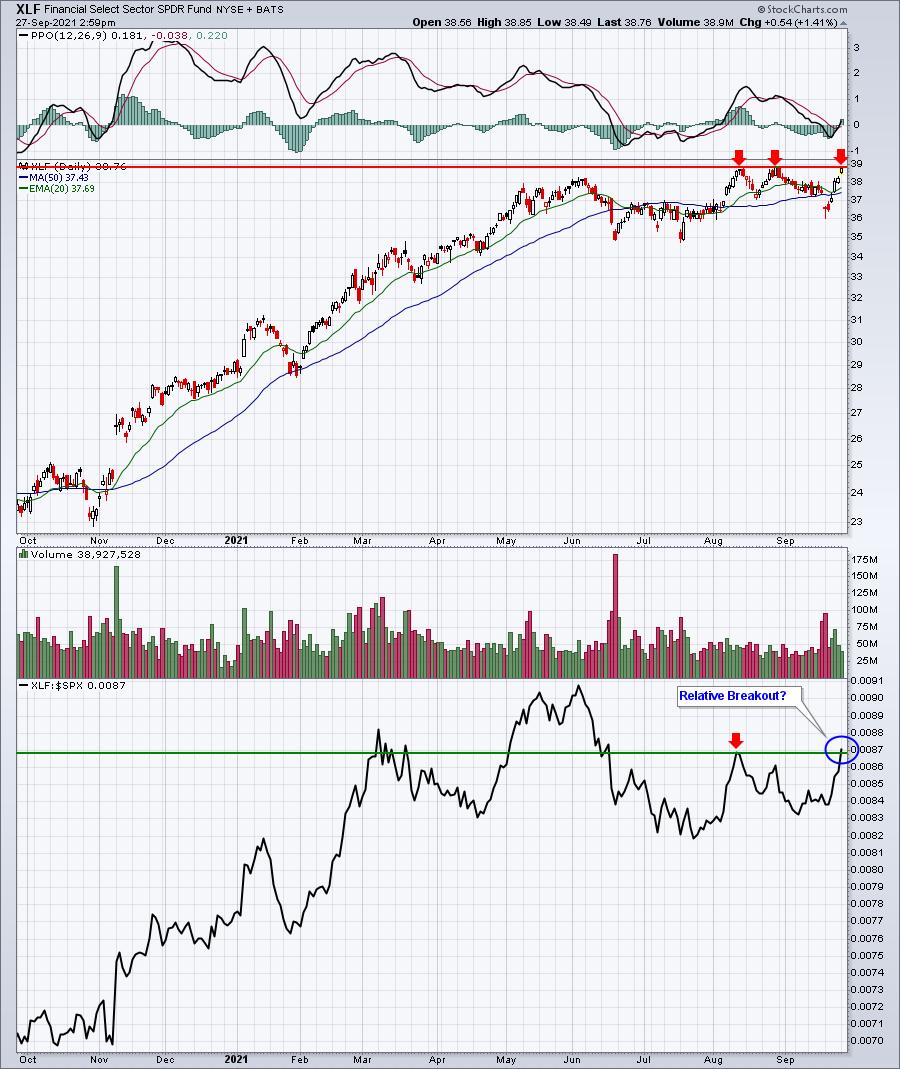
The key from here is whether the XLF can negotiate that price resistance at 39. If so, we could see additional short-term leadership from this sector. Remember, leadership continually rotates during bull markets. There's nothing wrong with leadership from any sector, although defensive groups generally should not lead for extended periods - especially during market uptrends.
ChartLists/Strategies
Because the renewed strength in treasury yields tends to favor small caps, I ran a scan today to highlight S&P 600 Small Cap stocks that are also on both our Strong Earnings ChartList (SECL) and Raised Guidance ChartList (RGCL). Here was the scan syntax to do this:
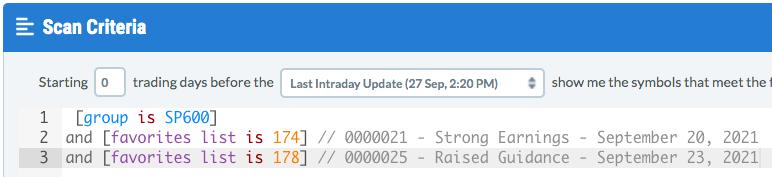
And here were the names that made the list:
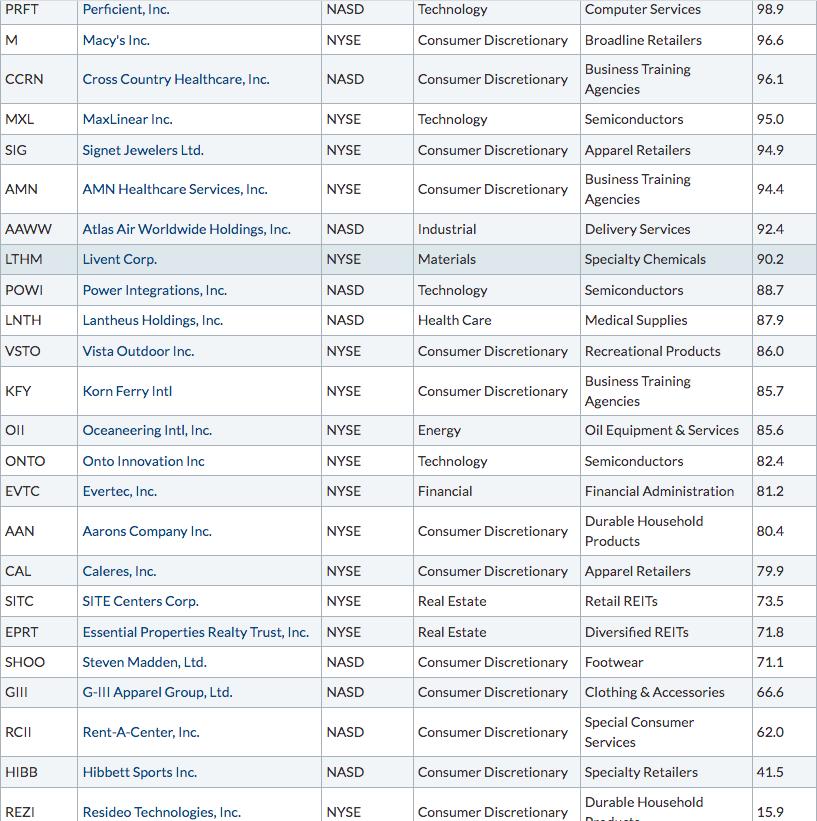
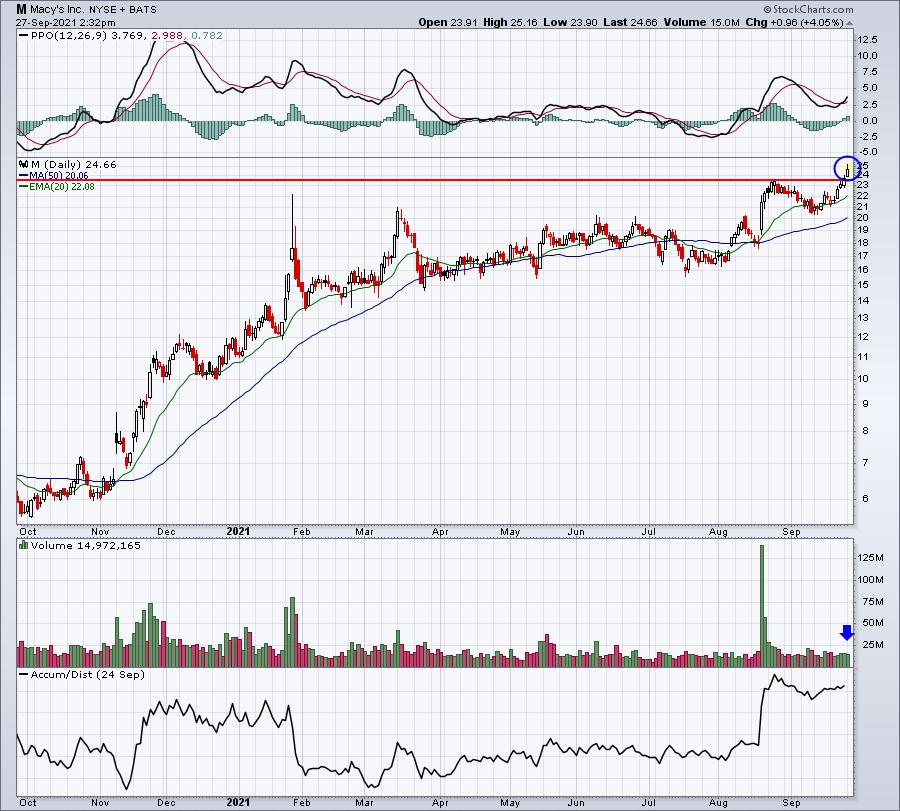
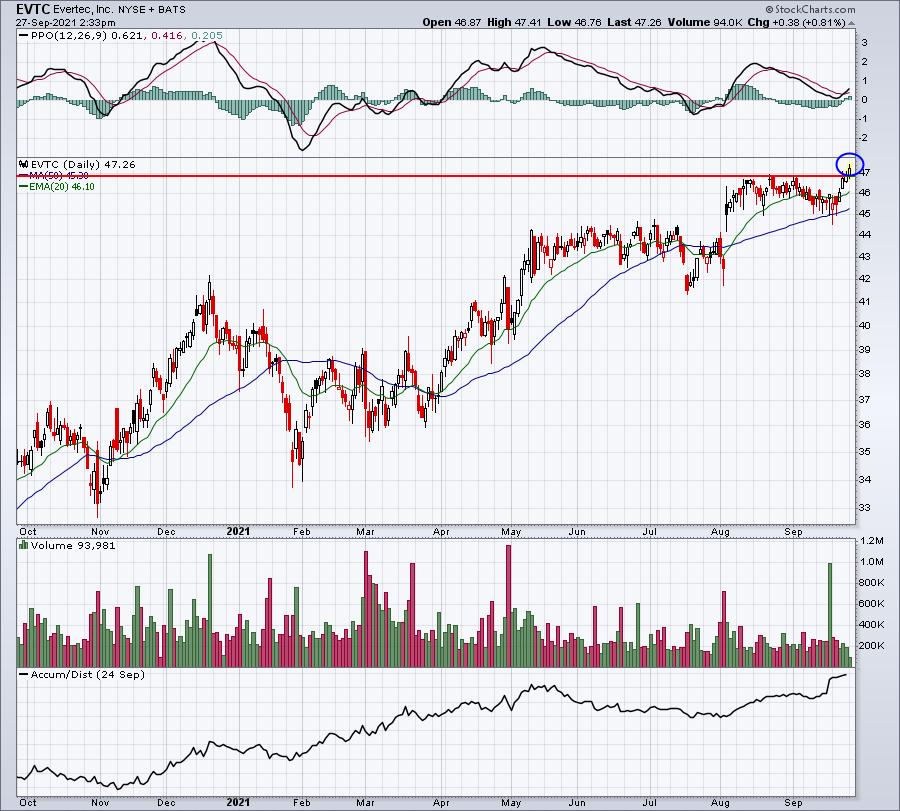
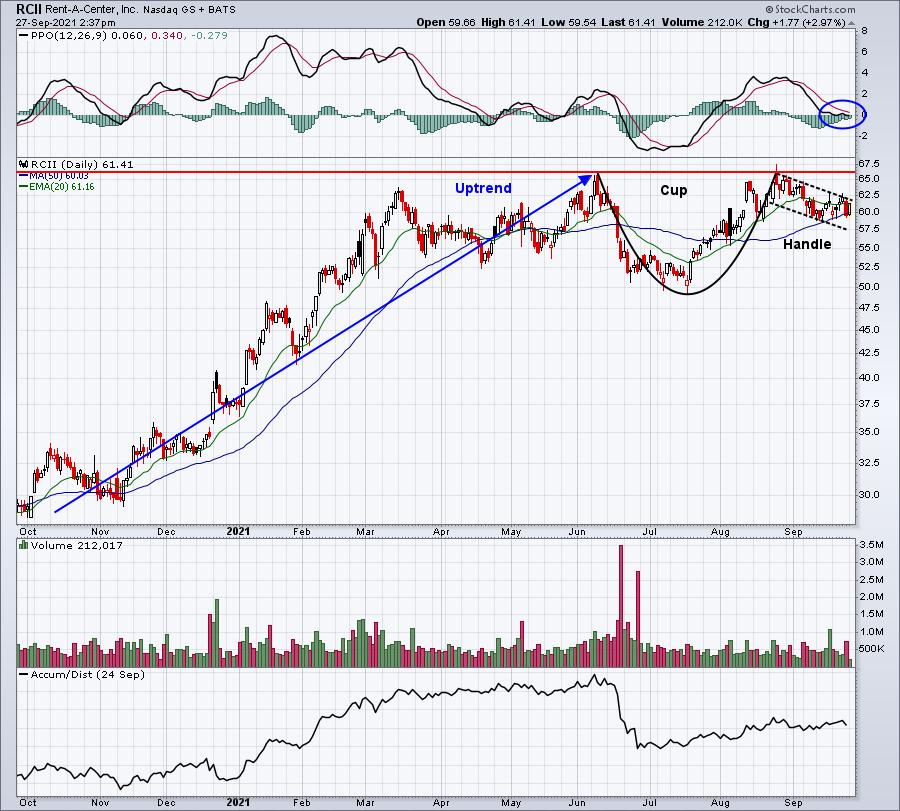
I had a hard time picking which stocks to illustrate, because I like a lot of them. But I'll give you two recent breakouts and one that has been consolidating and is now ready to move:
M (breakout):
EVTC (breakout):
RCII (cup with handle):
If you want to see how powerful cup with handle breakouts can be, check out the Avis Budget Group (CAR) chart that I featured in a recent DMR (September 16th):
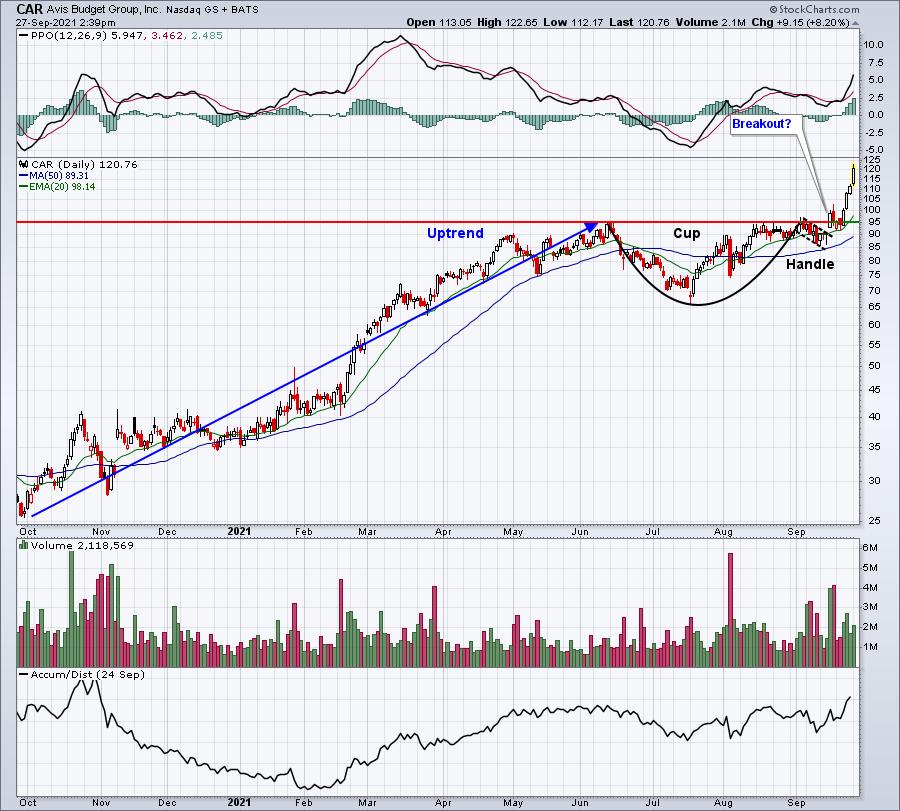
After the breakout, CAR moved back and tested its rising 20-day EMA, then exploded higher.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Monday, September 27:
CNXC, ACB
Tuesday, September 28:
MU, INFO, FDS, DAVA, THO, SNX, UNFI, CALM
Economic Reports
August durable goods: +1.8% (actual) vs. +0.6% (estimate)
August durable goods ex-transports: +0.2% (actual) vs. +0.4% (estimate)
Happy trading!
Tom