
EB Daily Market Report - Wednesday, October 27, 2021
Executive Market Summary
- Futures were higher overnight and our key major indices opened up; mid caps ($MID) and small caps ($SML) have lagged throughout the session
- The NASDAQ is showing relative strength today as consumer discretionary (XLY, +0.87%) shows strength
- Technology (XLK, +0.69%) and communication services (XLC, +0.65%) are the only other sectors in positive territory
- Energy (XLE, -2.18%) and financials (XLF, -1.06%) are weak as crude oil ($WTIC, -1.96%) and the falling 10-year treasury yield ($TNX) weighs on these sectors; the TNX is down 9 basis points
- Microsoft (MSFT, +4.88%) and Alphabet (GOOGL, +6.02%) both reported strong quarterly earnings and are being rewarded
- Hotels ($DJUSLG, +2.29%) are the best-performing discretionary group as Hilton Worldwide (HLT, +2.98%) sets a new all-time high
- Meanwhile, consumer finance ($DJUSSF, -5.19%) is weak with Lending Club Corp (LC, -7.81%) and Capital One Financial (COF, -6.92%) reeling; the latter beat revenue and EPS estimates, but is lower nonetheless
Market Outlook
The short-term market action is most definitely being swayed by the big drop in the 10-year treasury yield ($TNX), which has now fallen over 17 basis points in the past 4 trading sessions. However, the impact on banks ($DJUSBK) has not been what you might think. I'm not quite sure what to make of this yet, but here is the last week's performance of all financial industry groups:
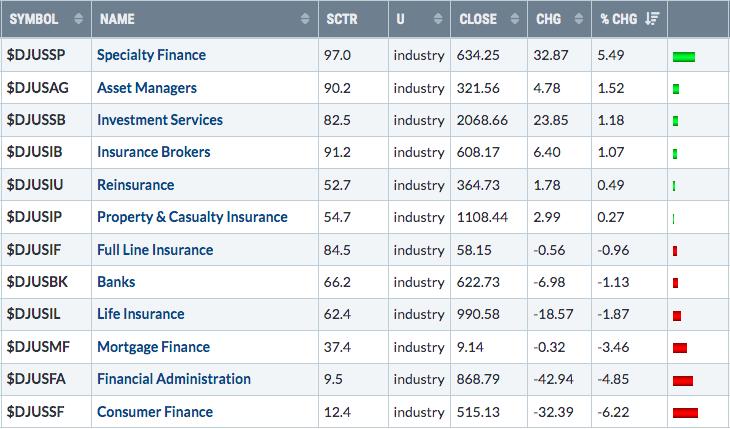
Banks and life insurance companies ($DJUSIL) are typically the most affected by movement in treasury yields, but these two groups have performed relatively well given the large drop in the TNX. I look further into banks in the Sector/Industry Focus section below.
Sector/Industry Focus
Banks remain very strong technically. The falling treasury yields are resulting in some profit taking, but overall the group has held up well and any test of its rising 20-day EMA will likely provide solid reward-to-risk entry:
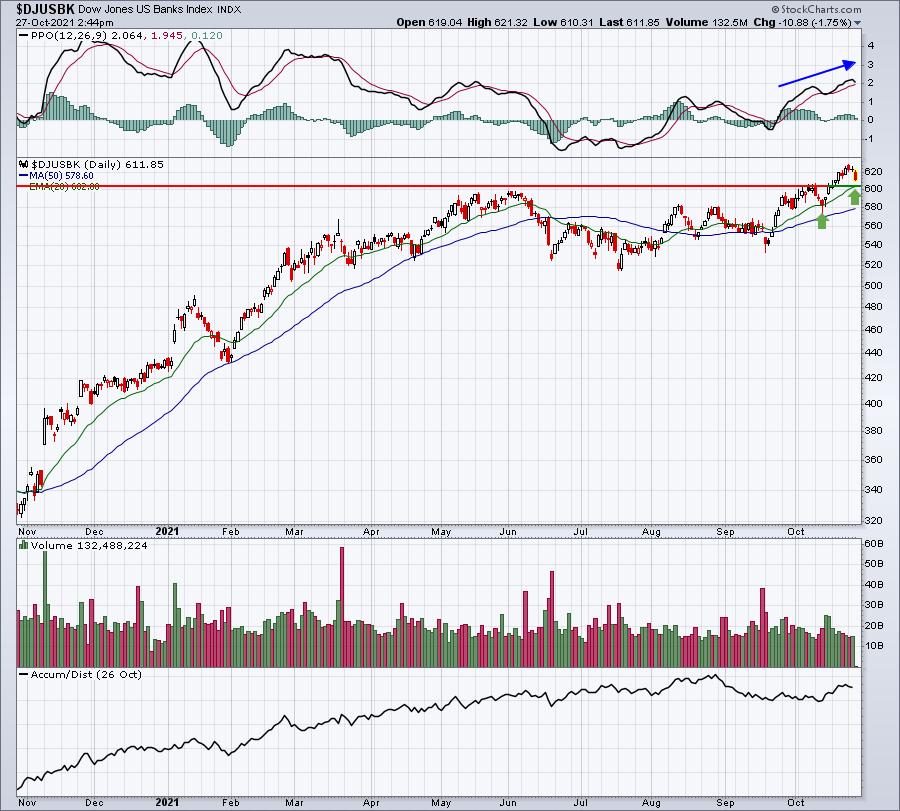
The PPO is setting new highs to accompany those recent price highs, a bullish sign. During uptrends, which I believe the banks have started, the rising 20-day EMA tends to provide great support. And we've already seen that 20-day EMA provide an entry opportunity.
ChartLists/Strategies
I reviewed our Strong Earnings ChartList (SECL) to review many of the better performing banks on that list. Here are two that will likely set up nicely for a trade on any further pullback:
BAC:
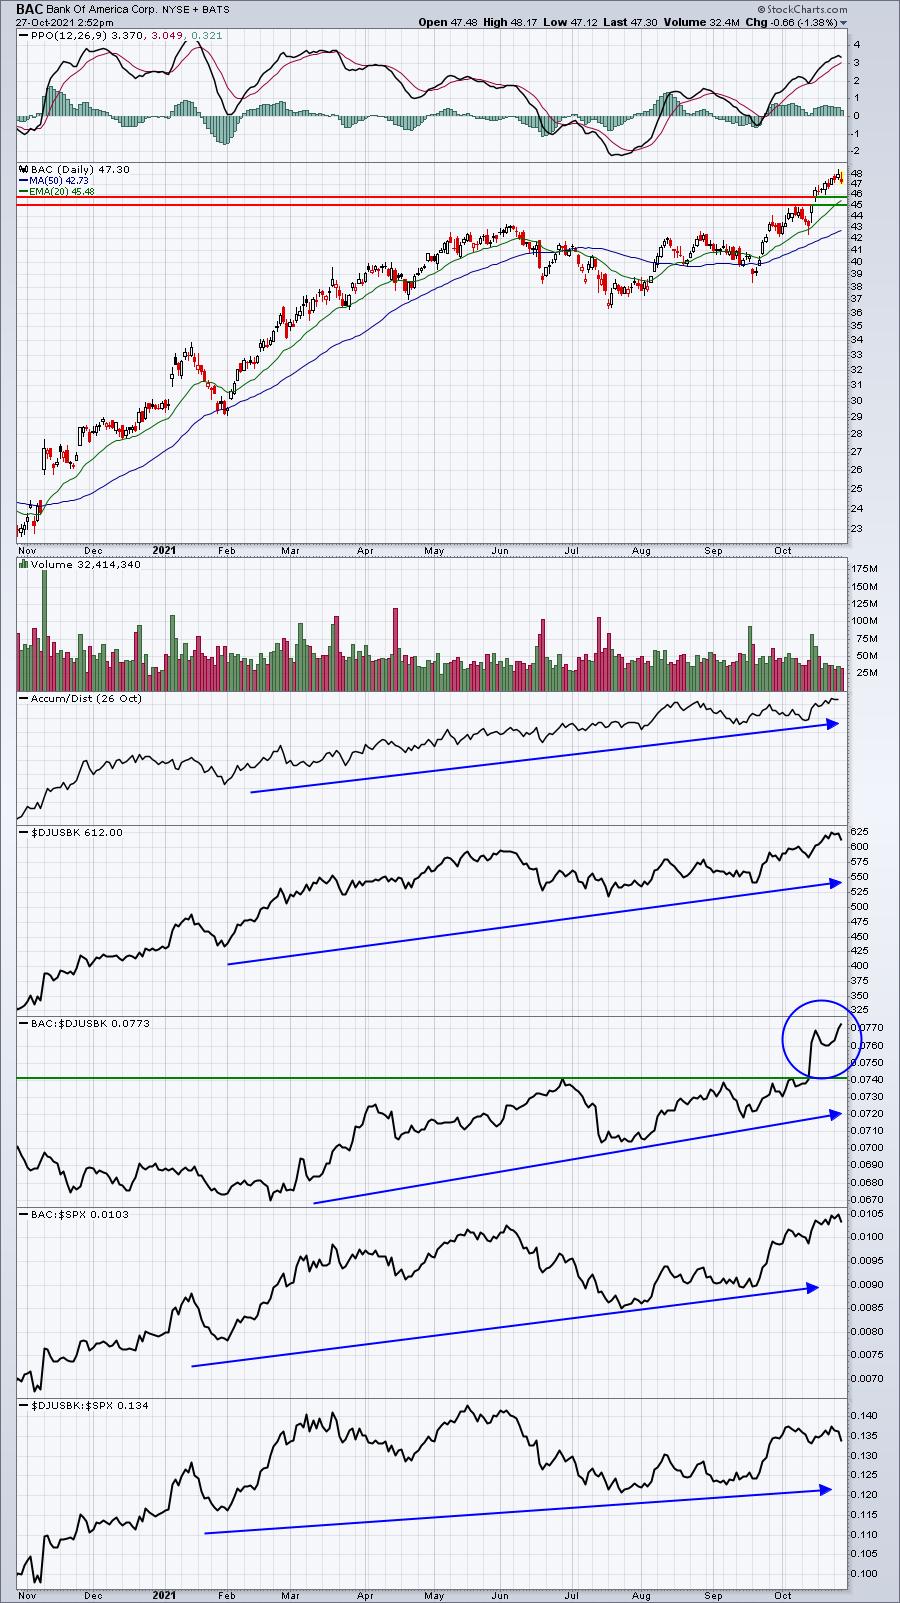
I'm always partial to leading stocks in industry groups and BAC is definitely a leader in this area. It's probably my favorite bank stock. We're seeing a little bit of profit taking here. There's excellent gap support in the 45-46 range, so if BAC sells off another 2-3%, the reward to risk will improve significantly.
FRC:
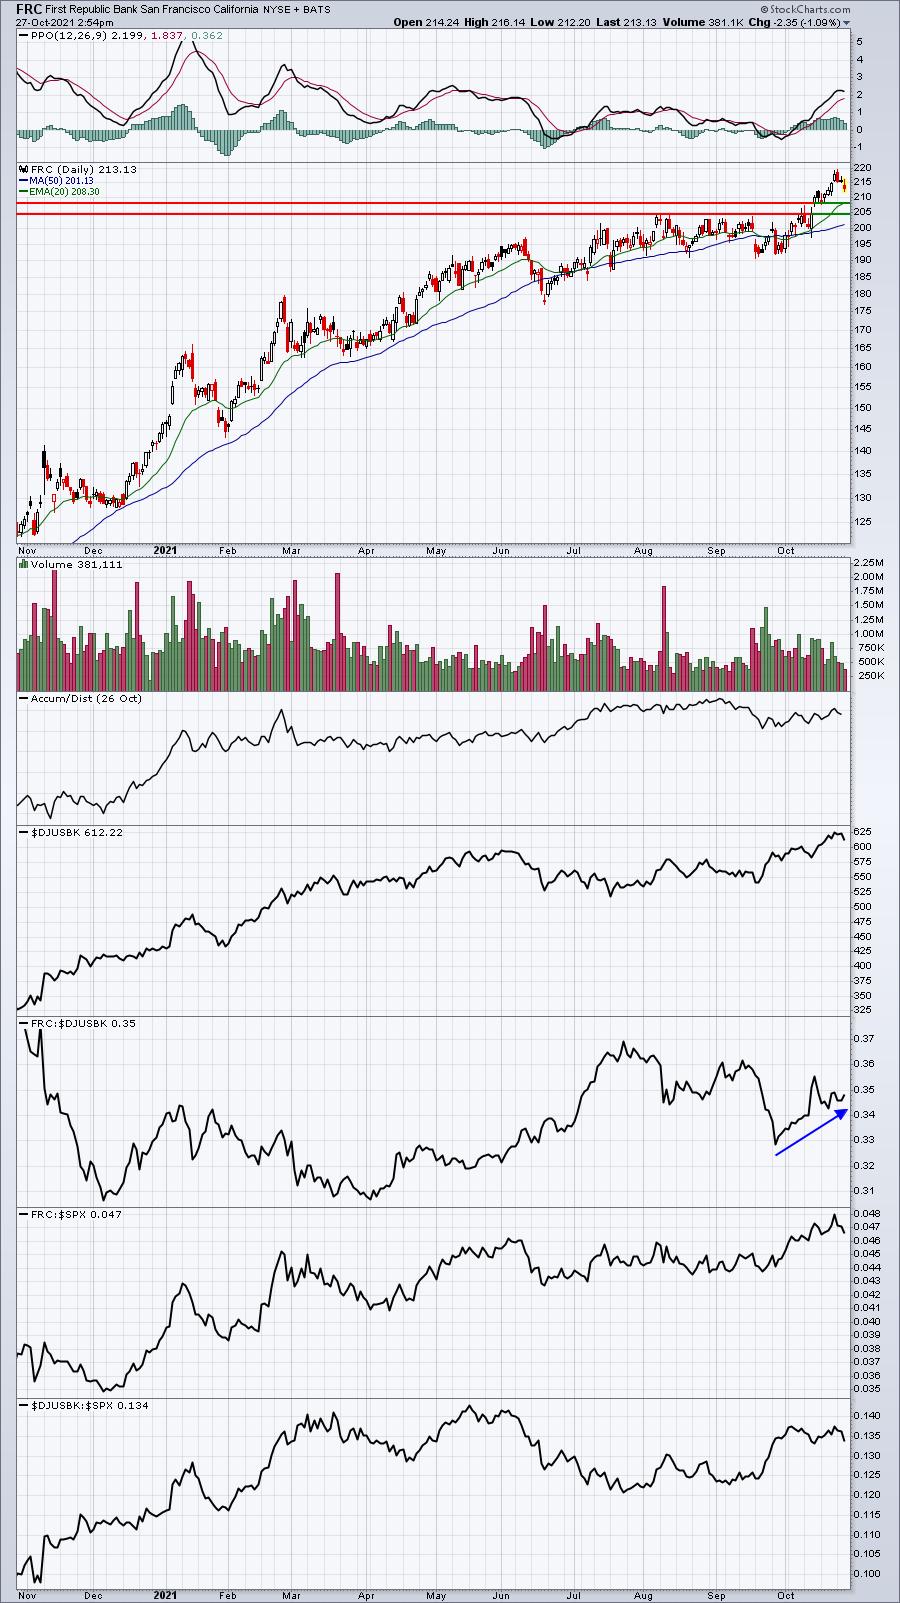
FRC is not as strong as BAC in terms of relative performance, but it is solid and we've seen more selling here as FRC nearly touched 220 on Monday, before falling back the past two sessions. The 205-208 gap support zone is best entry, but it may not get down that far. Buying shares on the way down to accumulate makes sense to me as I expect financials will bounce back nicely in November. Since this secular bull market began in 2013, banks haven't been great performers. However, there's no denying their solid performance in Q4. Check this out:
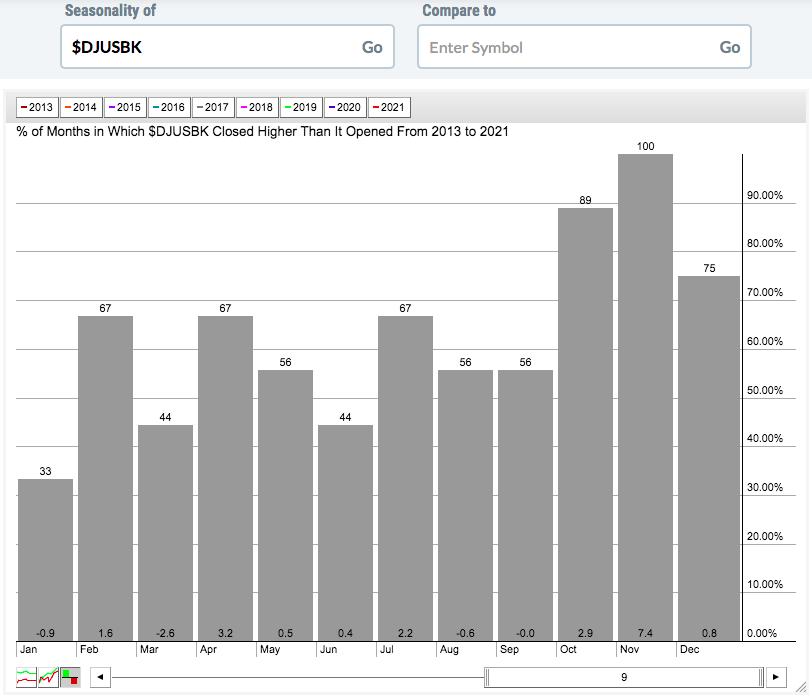
The average return for the entire bank index is 10.3% for the October-November period (2.9% for October and 7.4% for November). There's no other time of the year that's even close to this type of return. Obviously, that doesn't guarantee us that November will be higher, but the odds do favor it. We can only invest based on probabilities as there are no guarantees that I'm aware of.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, October 27:
TMO, KO, MCD, NOW, BMY, BA, GSK, ADP, GM, CME, FISV, EW, NSC, F, BSX, TWLO, GD, EBAY, KLAC, TEL, APH, ALGN, ORLY, SPOT, KHC, XLNX, CTSH, HLT, AFL, ODFL, WCN, SU, AVB, GRMN, HES, YNDX, URI, YUMC, UMC, EXR, INVH, ARES, MAA, DTE, DT, TDOC, TYL, RJF, DRE, TDY, IP, CINF, ROL, VICI, AVY, WAB, MOH, ACGL, PPD, MAS, AEM, BMRN, NLY, BG, TEVA, RE, SCI, AZPN, PEGA, WOLF, CONE, OC, PAG, EQT, KRC, MKSI, UPWK, SLAB, HOG, CHX, MC, MXL, MTH, ALSN, MEOH, TMHC, LC, BOOT, FORM, SIMO, IRBT, SNBR, UCTT, OII, NTGR
Thursday, October 28:
AAPL, AMZN, MA, CMCSA, MRK, RDS/A, SHOP, LIN, SONY, SBUX, AMT, SNY, CAT, SYK, MO, GILD, ICE, MCO, ITW, NOC, TEAM, DXCM, KDP, CARR, NEM, AEP, RSG, BAX, STM, RMD, YUM, HSY, CBRE, XEL, AJG, SGEN, NOK, WLTW, WST, SWK, FMX, LH, FTV, HIG, HBAN, VRSN, SIRI, MPWR, ALNY, BIO, AVTR, FE, TW, CG, SSNC, WDC, TFX, CMS, CHKP, TXT, LKQ, ABMD, CPT, ZEN, RGEN, EMN, ARGX, CLVT, LPLA, MHK, NVCR, MPW, DVA, GLPI, TFII, DECK, AOS, AGCO, RS, TAP, TPX, OSK, MSTR, SKX, HLI, NLSN, X, COLM, TXRH, POWI, ACHC, AUY, PRFT, FTDR, OSTK, TEX, WERN, SWI, TREE, FLWS, EB, VCRA, ATEN
Economic Reports
September durable goods: -0.4% (actual) vs. -0.9% (estimate)
September durable goods ex-transports: +0.4% (actual) vs. +0.5% (estimate)
Happy trading!
Tom