
EB Daily Market Report - Wednesday, November 3, 2021
Sneak Preview - Earnings Reactions Portfolio Event
Today at 4:30pm ET, I'll be discussing our latest portfolio - the Earnings Reactions Portfolio - which has provided a very solid first quarter of existence, outdistancing the S&P 500. I'll be discussing this portfolio later today, including how and why it was created and its initial performance. If you'd like to understand more about this portfolio, be sure to join us. If you can't make it live, all of our events are recorded and we'll be sure to make this recording available to you later this evening.
Here's the link to join me:
https://earningsbeats.zoom.us/j/81251812641
The room will open at approximately 4:00pm ET and the webinar will begin promptly at 4:30pm ET.
ChartList Updated
The Raised Guidance ChartList (RGCL) has been updated and posted to our website. You can now view or download this ChartList at your leisure.
Executive Market Summary
- Futures were mixed overnight and U.S. equities remain mixed
- Small caps ($SML) are leading on a relative basis and breaking out to an all-time high; more on this below
- Mid caps ($MID) are also showing leadership today
- The 10-year treasury yield ($TNX) has jumped 2 basis points to 1.57% after a stronger-than-expected ADP employment report for October; nonfarm payrolls will be released on Friday
- Consumer discretionary (XLY, +0.58%) is leading on a relative basis among sectors, while utilities (XLU, -1.01%) and energy (XLE, -0.95%) are lagging
- Crude oil ($WTIC, -3.66%) has fallen 3.56% today below $81 per barrel, contributing to weakness in energy stocks
- In today's FOMC statement, the Fed announced it would begin tapering its asset purchases later this month and slowly taper moving forward, with changes to this policy if necessary to support the economy
- Activision Blizzard (ATVI, -14.50%) is the worst performer today on the S&P 500 after it announced game and project delays; it was the company's worst 1-day performance in 13 years
Market Outlook
Small caps ($SML, +1.96%), barring a final hour reversal, are breaking out, which is extremely bullish for U.S. equities. A breakout in small caps speaks volumes about the strength of the U.S. economy, as does the breakout in transportation stocks. Here's a chart featuring both, including their price relative charts vs. the S&P 500 in the bottom two panels:
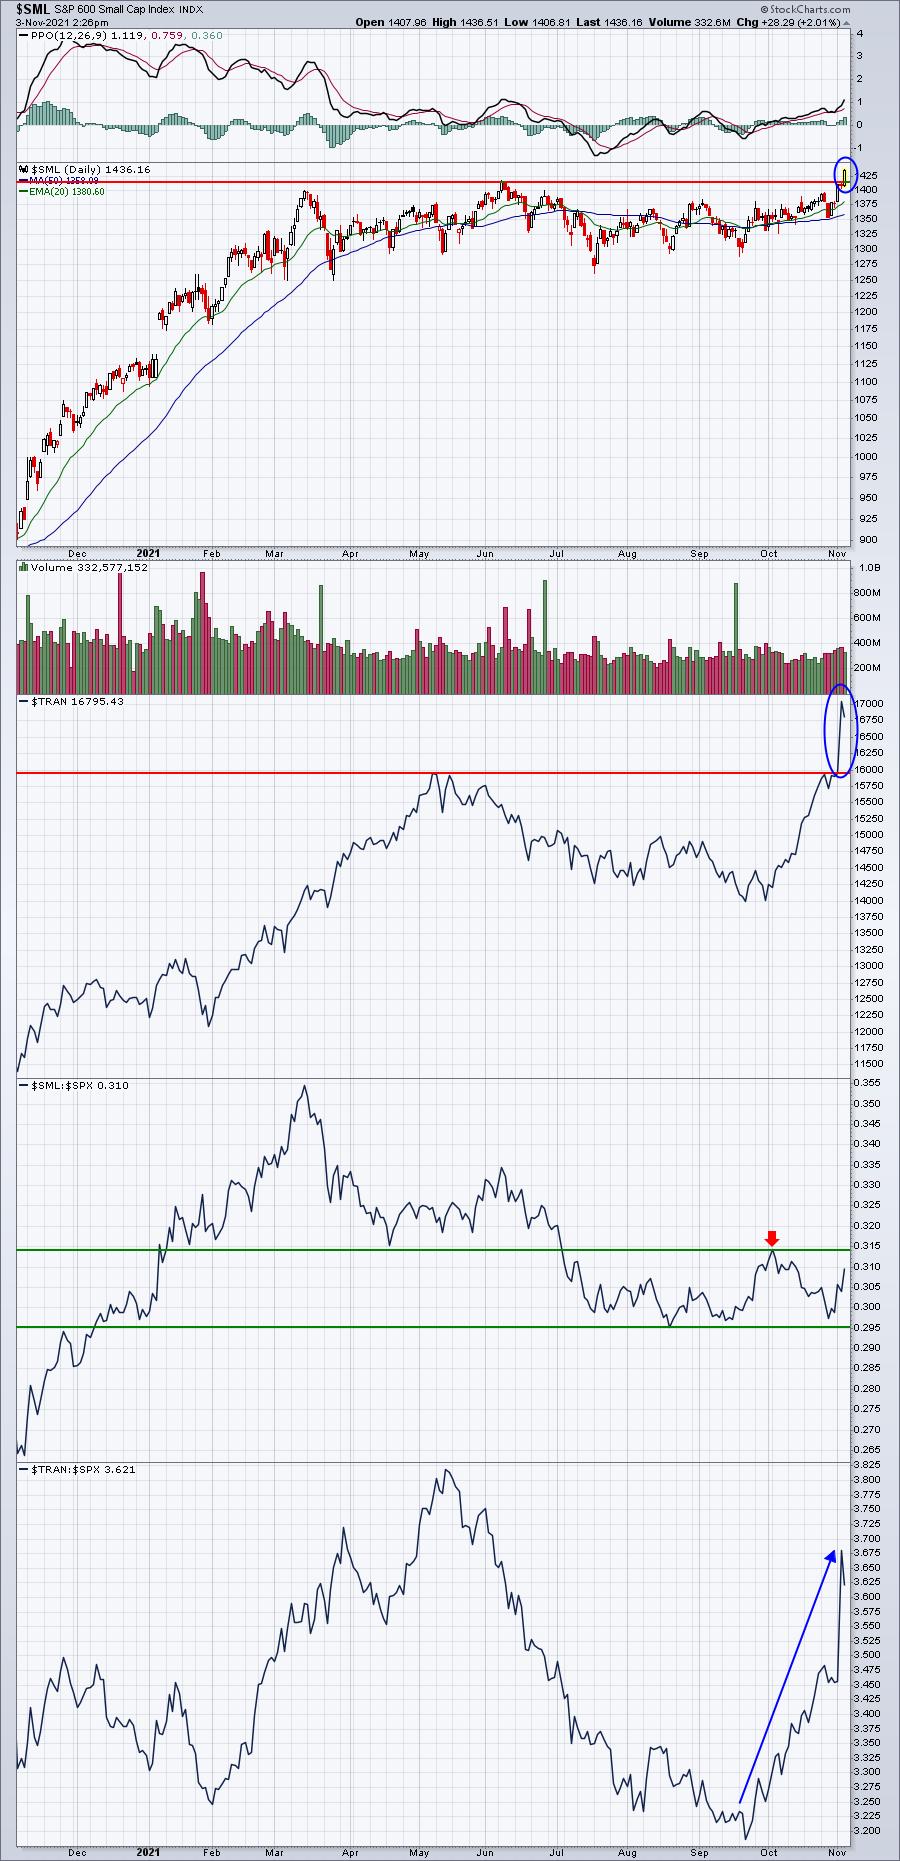
When these two groups lead, it's a testament to the strength of our economy.
Sector/Industry Focus
Life insurance ($DJUSIL) typically performs well when treasury yields are rising. Today, after the FOMC policy statement, yields shot higher (though they're moving back down currently). Should yields begin to trend higher, a beneficiary would be life insurance companies. They're threatening to make a breakout, even with a late pullback in treasury yields this afternoon:
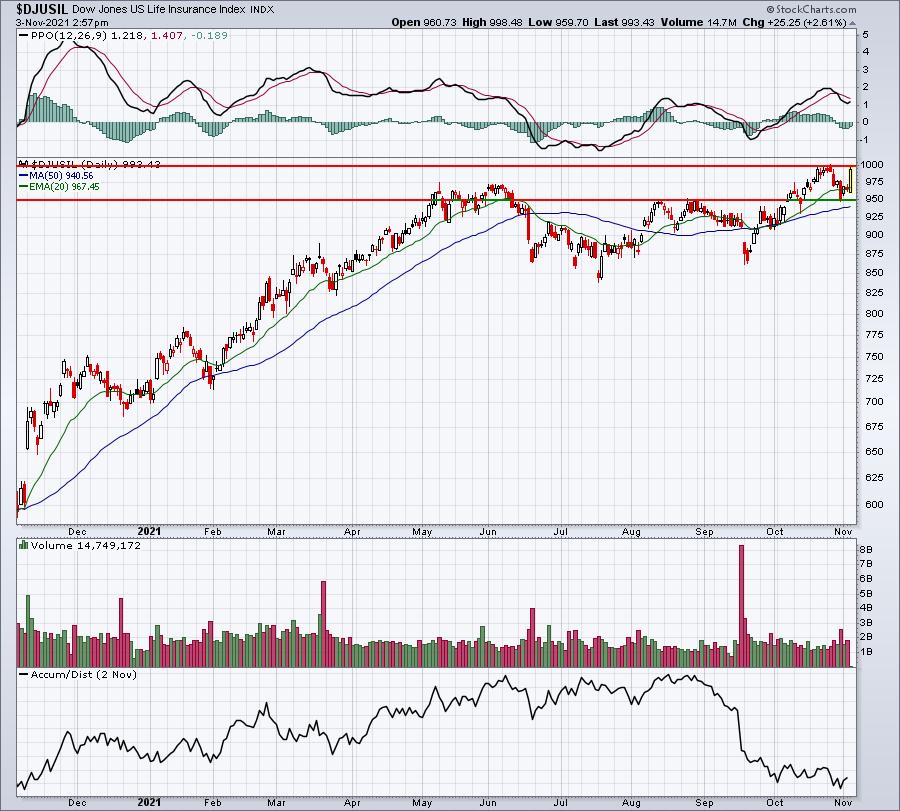
The DJUSIL now resides in a 950-1000 consolidation range, but a breakout that coincides with rising yields would be a breakout worth respecting.
ChartLists/Strategies
Here are a few potential trading candidates from our various ChartLists based on technical developments today:
ORLY:
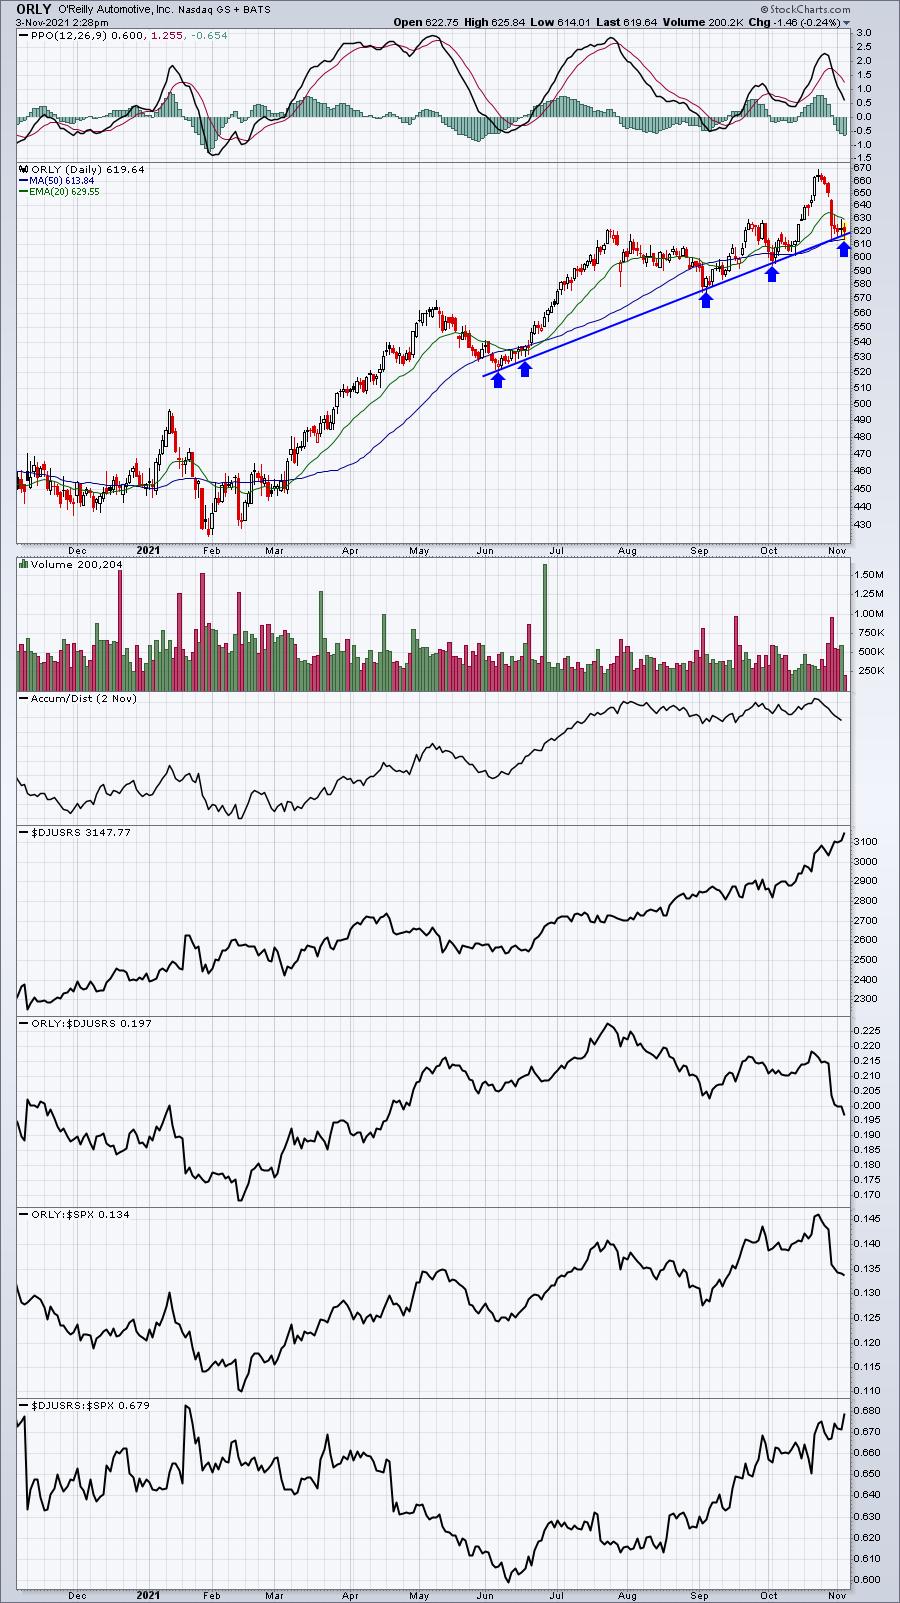
I like the trendline test here with a tight closing stop below the 50-day SMA.
The initial bond market reaction to the Fed's tapering was to sell bonds, sending treasury yields higher. Should that continue, look for a bounce in recent beaten-down financial and industrial names. Here's one potential trade from each sector:
PNC (financials):
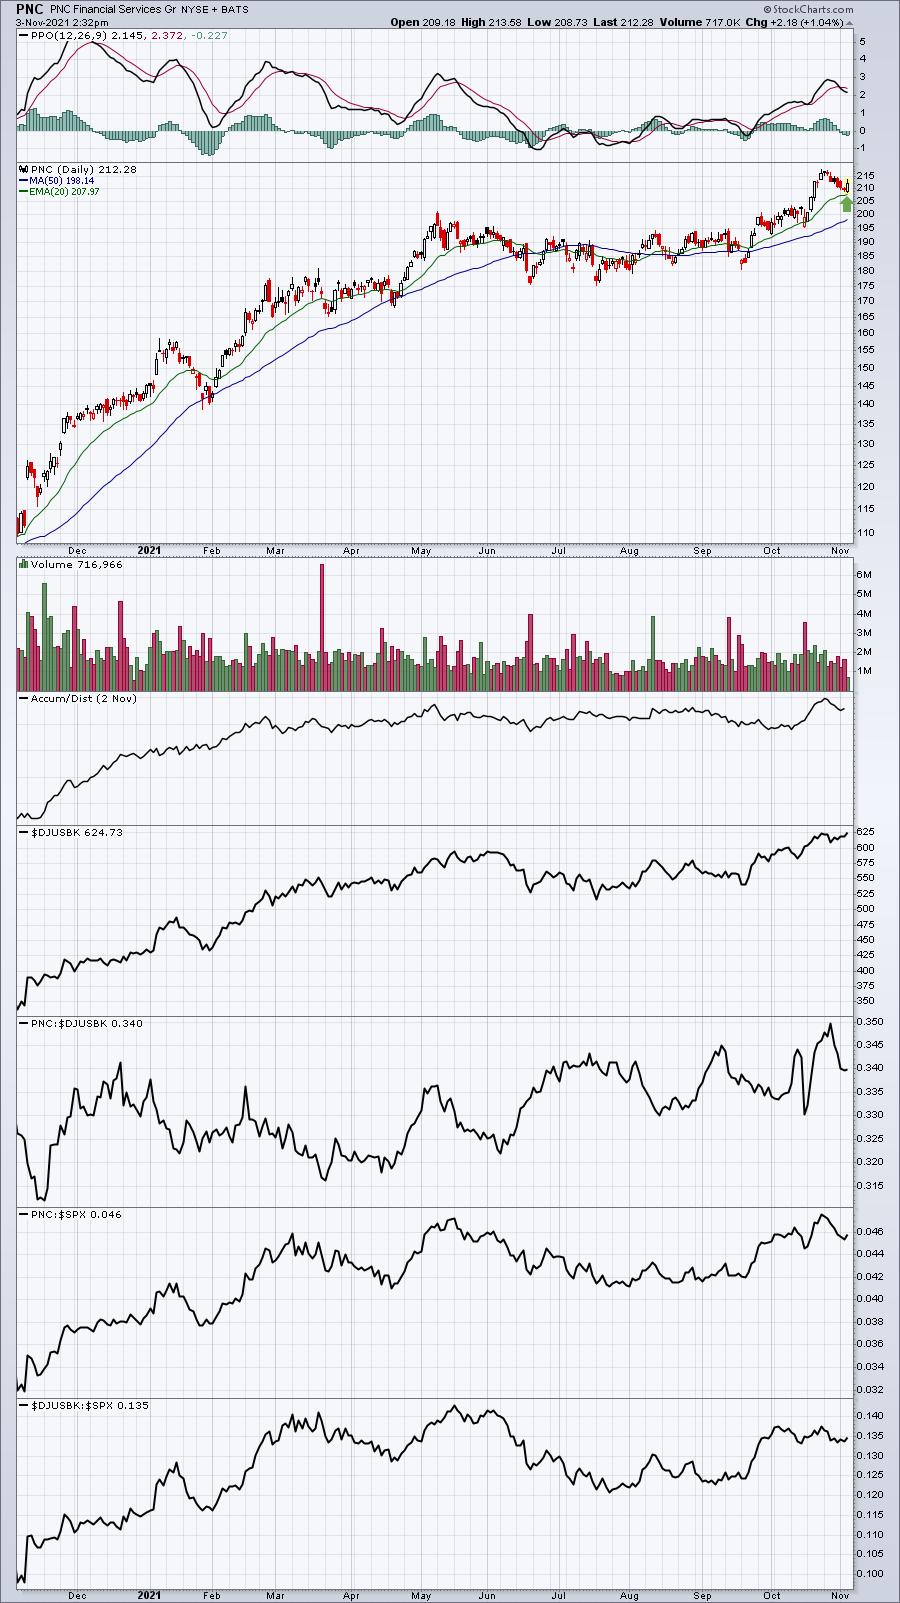
Rising 20-day EMA tests are always a favorite of mine when we're in a secular bull market advance. PNC is a strong relative performer vs. the its banking peers, as evidenced by its 52-week relative high that printed at the end of October. I expect it will begin leading again.
DE (industrials):
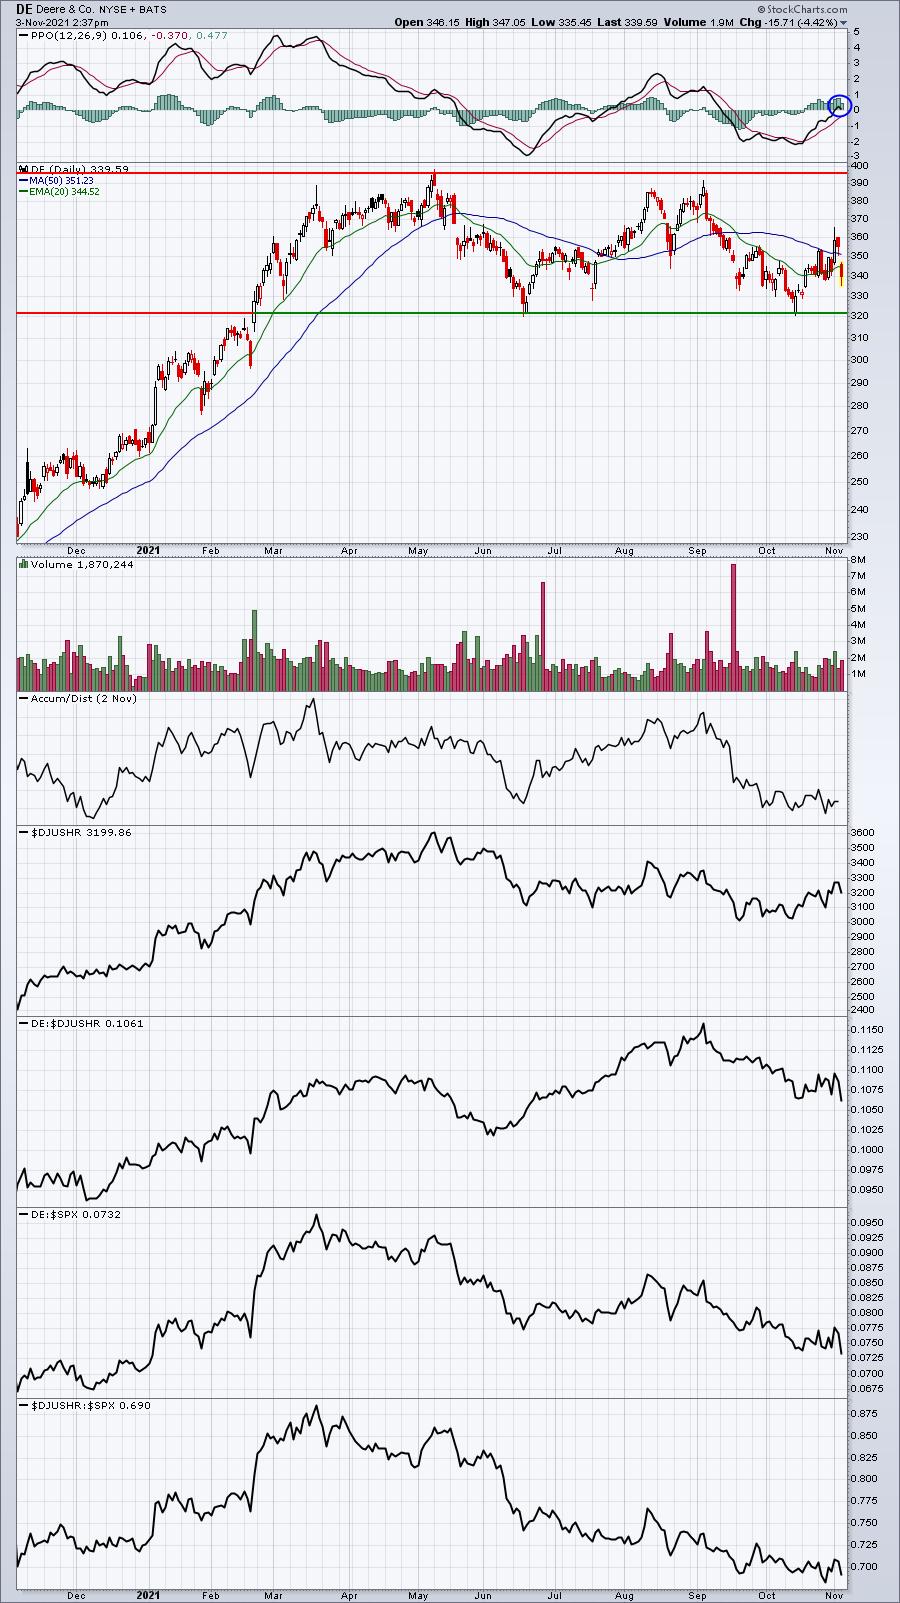
DE is being hurt by a very weak peer group - commercial vehicles & trucks ($DJUSHR), but the group has recently begun trending back above its 20-day EMA. Also, DE absolutely LOVES the month of November as you can see from the seasonal chart below:
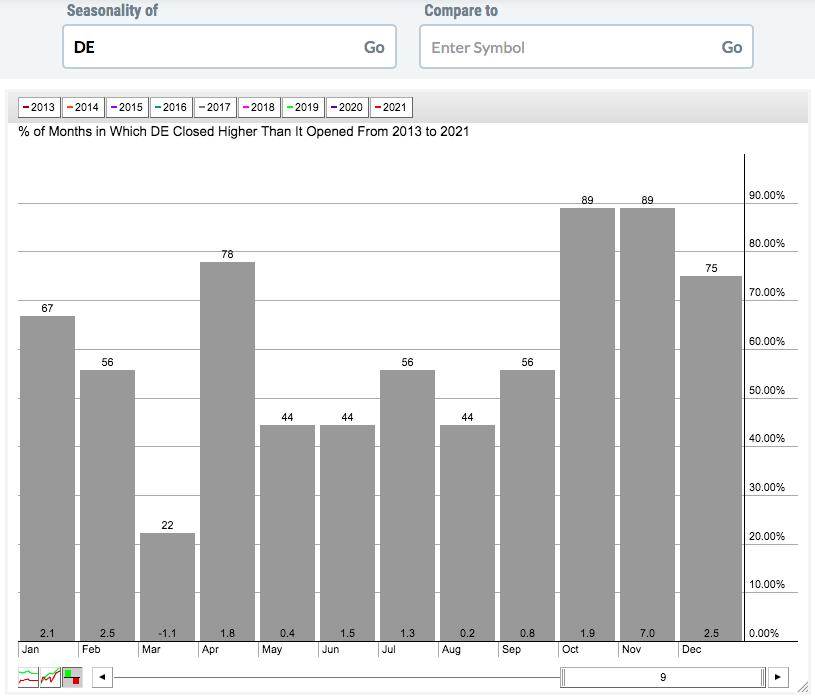
This is just the last 9 years, or since this secular bull market began in 2013. DE has averaged gaining 7% during the month of November. The next closest months based upon monthly performance has been December and February, which have both averaged gaining 2.5%. It's safe to say that DE shows seasonal strength in November, so this slight selloff would seem to represent a solid opportunity.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, November 3:
QCOM, CVS, BKNG, EQIX, HUM, EMR, MET, MAR, EXC, PXD, TT, ROKU, EA, ITUB, SLF, HUBS, MFC, ALL, ANSS, ETSY, CTVA, ALB, FNV, HZNP, ET, CDW, CVE, FOXA, MGM, CRL, IR, TRMB, AEE, TTWO, BR, ETR, FLT, CDAY, QRVO, XP, CLR, TXG, BIP, ATH, LBTYA, PTC, EVRG, UHAL, EQH, GFL, LNC, LUMN, JLL, MRO, QGEN, CF, HST, DISCA, GDDY, PLTK, KL, BWA, SITE, PEN, APA, NI, NCLH, H, TNDM, UTHR, CTRA, SMG, DXC, ITT, CPRI, EXPI, WK, RPD, SRPT, VVV, CLH, FSLY, SPWR, WING, SITM, QLYS, FSR, SKLZ, SPR, KNBE, SHOO, MATX, MGNI, ATRC, REGI, VSH, TTGT, KTOS, EVH, AAWW, EVRI, CRTO, ACLS, ELF, UPLD
Thursday, November 4:
MRNA, SQ, ABNB, ZTS, UBER, DUK, MELI, CI, FIS, BDX, REGN, SO, APD, ILMN, NET, EOG, FTNT, CVNA, AIG, DDOG, CNQ, APTV, BCE, MNST, MCHP, MSI, PH, EPAM, RKT, WELL, MTD, GOLD, OXY, BILL, ZBH, BLL, PINS, SWKS, PTON, ED, LNG, W, ABC, EXPE, VMC, VIAC, CNHI, LYV, PPL, DISH, PODD, K, CFLT, PBA, WPM, AES, PWR, PCTY, AVLR, CGNX, CNP, NLOK, FND, LNT, NWSA, OTEX, LSPD, IRM, AMH, HWM, FSLR, IAC, NVAX, TRGP, XRAY, GH, DBX, BLDR, REG, RUN, CTXS, PENN, PCOR, ICL, NTRA, CUBE, BAP, CABO, TPL, DOCN, NTLA, NRG, OLED, SYNA, HII, WMS, CHH, RBA, GILD, PLNT, CYBR, APPN, ANGI, SWCH, TDC, LITE, QDEL, RDFN, NKLA, MTSI, LTHM, TGTX, MUR, TGNA, ALRM, VG, ONTO, OUT, REZI, ITRI, HL, AXNX, KTB, SHAK, FROG, NKTR, YELP, DVAX, SLQT, TDS, IRTC, ACMR, BGS, TGH, GOGO, MDRX, LNTH, CNDT, GPRO, LASR, VRAY, CNXN, GEO, CARS
Economic Reports
October ADP employment report: 571,000 (actual) vs. 400,000 (estimate)
October PMI composite: 57.6 (actual) vs. 57.3 (estimate)
September factory orders: +0.2% (actual) vs. +0.1% (estimate)
October ISM services: 66.7 (actual) vs. 61.9 (estimate)
FOMC policy statement issued at 2:00pm
Happy trading!
Tom