
EB Daily Market Report - Thursday, November 4, 2021
Executive Market Summary
- Futures were mixed overnight, but NASDAQ shares are showing significant leadership today
- Large cap growth stocks are soaring, especially many of those in semiconductors ($DJUSSC, +6.16%)
- NVIDIA (NVDA, +16.97%) leads the S&P 500 on the heels of positive analyst comments; it's now the 7th largest U.S. company based on market cap
- Leadership today couldn't be in better hands; technology (XLK, +1.69%) and consumer discretionary (XLY, +1.63%) are lapping the field
- Financials (XLF, -2.02%) represent the weakest sector as yields fall
- The 10-year treasury yield ($TNX) has dropped 5 basis points to 1.53%
- The dollar (UUP, +0.53%), meanwhile, is creeping closer and closer to its 2021 high
- That rising dollar is putting pressure on energy (-0.52%) and materials (XLB, -0.24%)
- Broadline retail ($DJUSRB, +2.78%) is pacing the consumer discretionary sector
Market Outlook
One of the growth ratios that I like to follow, IWF vs. IWD, is breaking to a fresh new 2021 relative high, a very bullish development for growth stocks overall. There's been plenty of news talking about how inflation will be so problematic. Wall Street completely disagrees. You don't load up on growth stocks ahead of a significant inflationary jolt. It makes no sense. So while the media focuses on the negativity of inflation, we'll continue to follow the MBAs on Wall Street and their money. Here's the IWF:IWD chart that says NO to inflationary worries:
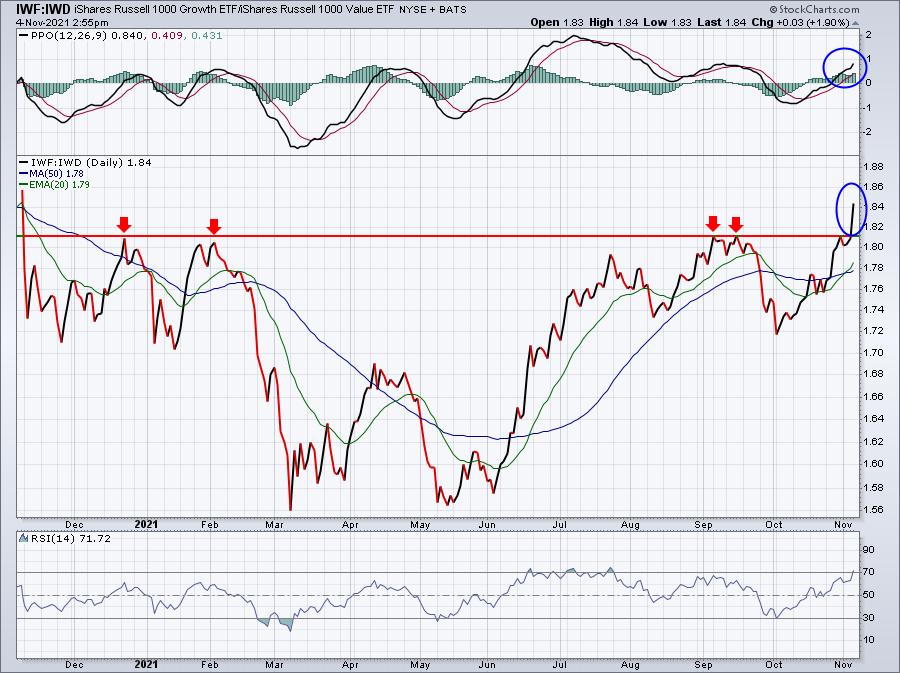
I know it always seems like the market can't go any higher, but when the risk-on investments like growth stocks are setting new highs and records, it's very difficult to be bearish.
Sector/Industry Focus
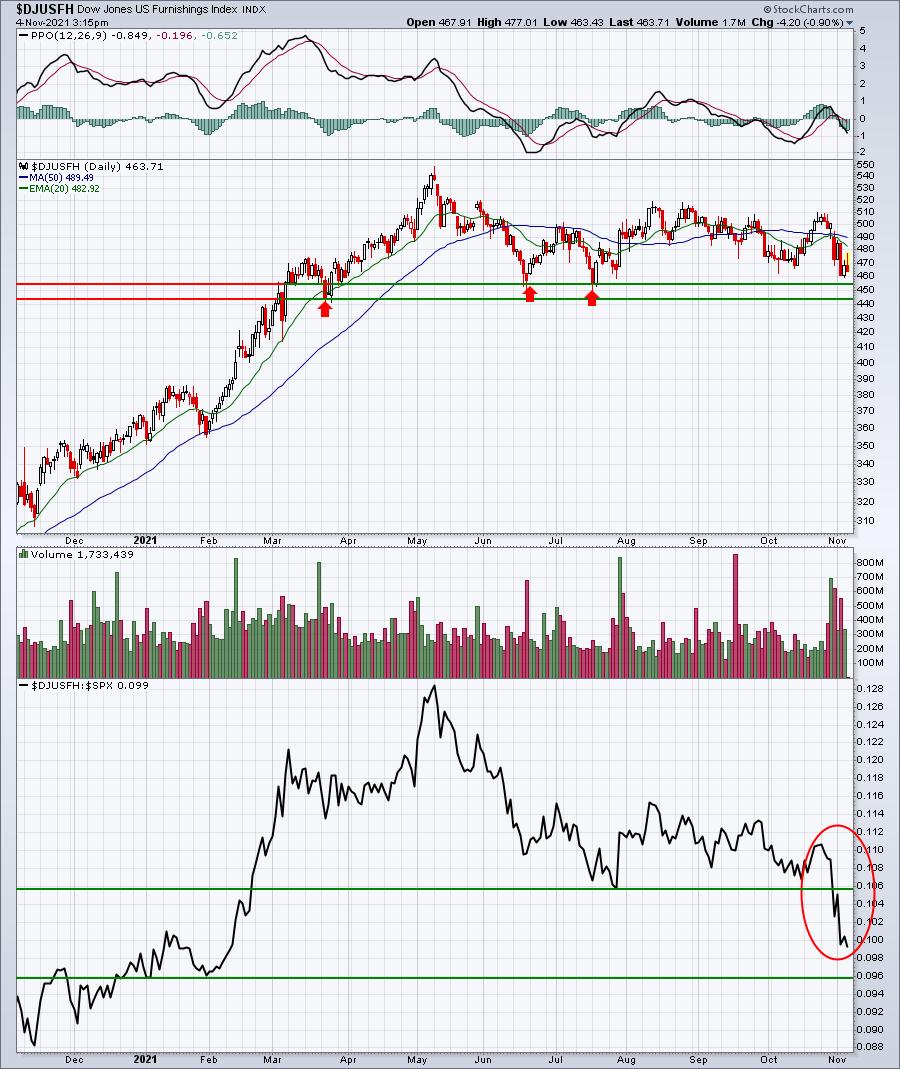
One area in consumer discretionary that was a prior leader in 2020, but has fallen upon hard times in 2021, is furnishings ($DJUSFH). This group needs to hold the absolute price support shown below. I then want to see relative strength kick in again:
ChartLists/Strategies
I searched through our ChartLists for possible furnishings stocks to consider for trade since that group is nearing key price support and the overall consumer discretionary area has been so strong. There was one on the Raised Guidance ChartList (RGCL).
TILE (reports earnings 11/5 before market opens):
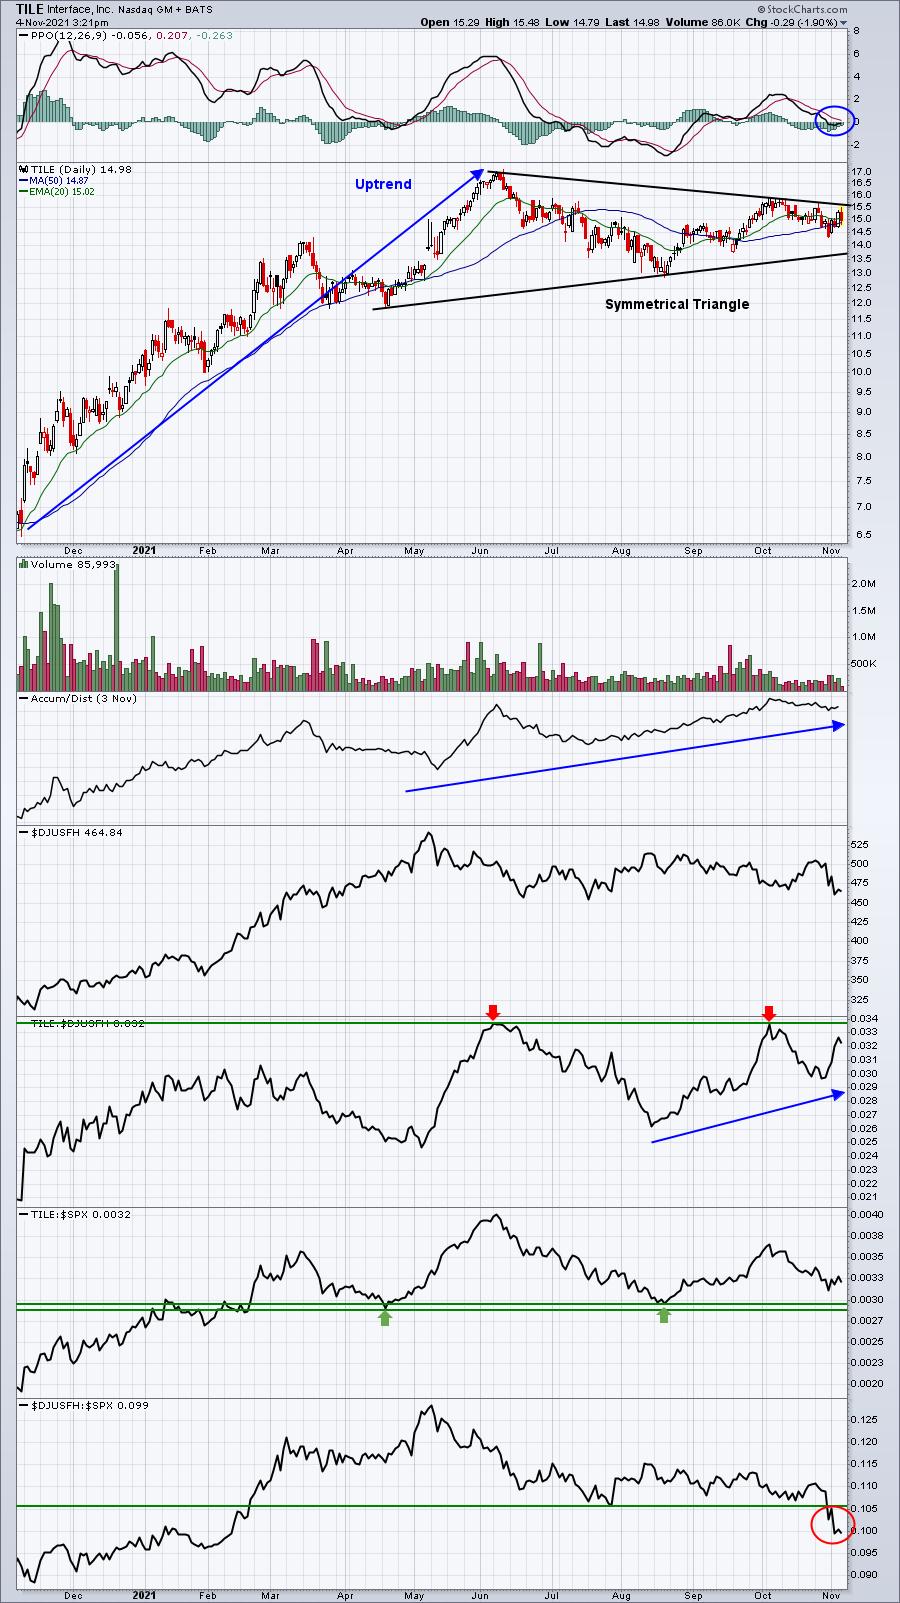
We could see a triangle breakout tomorrow morning with earnings, but obviously that increases the risk of buying now quite substantially. While the DJUSFH has been weak on both an absolute and relative basis, TILE has been an elite performer within the group, recently testing its relative strength high vs. its peers. It also has held relative support vs. the S&P 500, something its peers have been unable to do. Finally, the AD line has remained strong on TILE, suggesting that it's being accumulated during this period of weakness. Of course, everything could change depending on that earnings report Friday morning.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, November 4:
MRNA, SQ, ABNB, ZTS, UBER, DUK, MELI, CI, FIS, BDX, REGN, SO, APD, ILMN, NET, EOG, FTNT, CVNA, AIG, DDOG, CNQ, APTV, BCE, MNST, MCHP, MSI, PH, EPAM, RKT, WELL, MTD, GOLD, OXY, BILL, ZBH, BLL, PINS, SWKS, PTON, ED, LNG, W, ABC, EXPE, VMC, VIAC, CNHI, LYV, PPL, DISH, PODD, K, CFLT, PBA, WPM, AES, PWR, PCTY, AVLR, CGNX, CNP, NLOK, FND, LNT, NWSA, OTEX, LSPD, IRM, AMH, HWM, FSLR, IAC, NVAX, TRGP, XRAY, GH, DBX, BLDR, REG, RUN, CTXS, PENN, PCOR, ICL, NTRA, CUBE, BAP, CABO, TPL, DOCN, NTLA, NRG, OLED, SYNA, HII, WMS, CHH, RBA, GILD, PLNT, CYBR, APPN, ANGI, SWCH, TDC, LITE, QDEL, RDFN, NKLA, MTSI, LTHM, TGTX, MUR, TGNA, ALRM, VG, ONTO, OUT, REZI, ITRI, HL, AXNX, KTB, SHAK, FROG, NKTR, YELP, DVAX, SLQT, TDS, IRTC, ACMR, BGS, TGH, GOGO, MDRX, LNTH, CNDT, GPRO, LASR, VRAY, CNXN, GEO, CARS
Friday, November 5:
ENB, D, TRP, JCI, HMC, SRE, TU, MGA, VTR, DKNG, ELAN, KIM, BEP, TIXT, VST, PNW, GT, CGC, GOOS, FLR, CNK, AMCX, SSP, NOG, TEN, AXL
Economic Reports
Initial jobless claims: 269,000 (actual) vs. 277,000 (estimate)
Q3 productivity: -5.0% (actual) vs. -1.5% (estimate)
Happy trading!
Tom