
EB Daily Market Report - Tuesday, November 30, 2021
ChartList Updated
I was finally able to update our Raised Guidance ChartList (RGCL). It's been updated on our website and is now available for viewing/downloading.
Executive Market Summary
- Futures were much, much lower overnight as COVID-19 variant Omicron saw Selling 2.0
- Federal Reserve Chief Powell also suggested that the Fed would be discussing an accelerated tapering program during its December meeting
- Commodities are mostly lower today, especially crude oil ($WTIC, -5.33%), which has dropped to $66 per barrel
- Money is rotating to safety today as treasuries sell off; the 10-year treasury yield ($TNX) has fallen 9 basis points to 1.44% as a result
- Communication services (XLC, -2.62%) is today's laggard among sectors, though 9 of the 11 sectors have dropped more than 1% today
- Technology (XLK, -0.62%) is the best performing sector as computer hardware ($DJUSCR, +2.47%) is being led higher by Apple, Inc. (AAPL, +2.81%)
- Pfizer (PFE, +2.89%) is the only stock in the S&P 500 to outperform AAPL
Market Outlook
Communication services (XLC) is no longer set up bullishly on its daily chart. I really thought we'd see 79 hold as support on its chart, but it didn't:
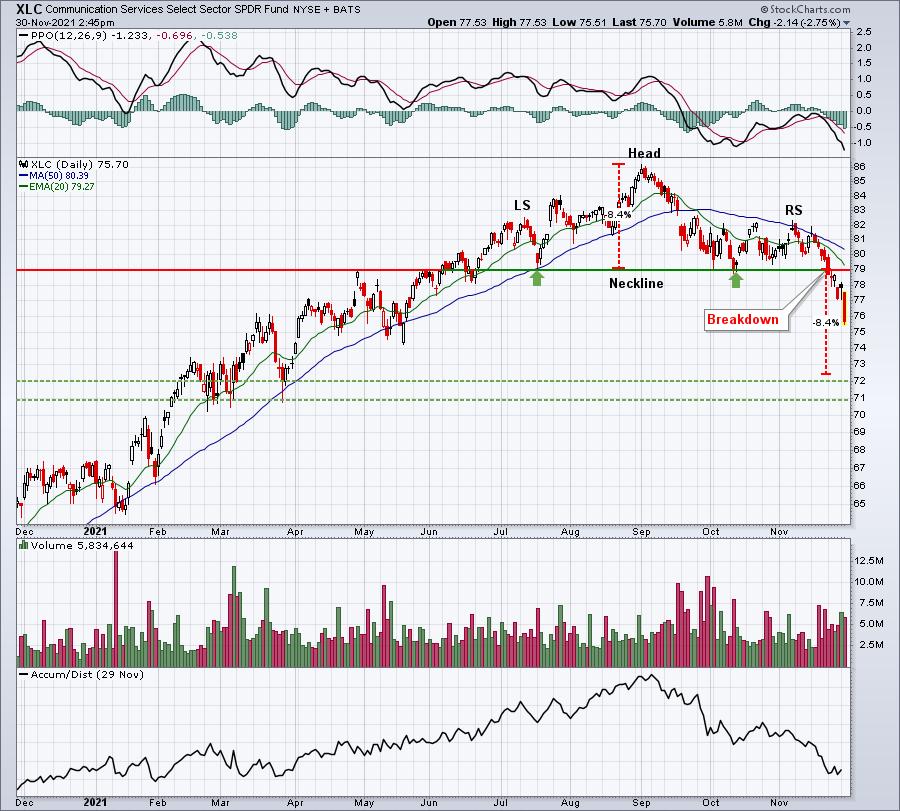
The AD line on this group has clearly weakened considerably and trading any stock within this sector will be more challenging because of the current technical environment. I'm seeing that 79 level as a neckline that was just violated. The distance between the top of the head and that neckline is roughly 8.36%. A potential measurement on the XLC is another 8.36% beneath the recent neckline breakdown, which would be roughly 72.50. I've drawn in two green-dotted horizontal lines that mark potential support areas near that measurement. I don't know if the XLC will make it that far to the downside, but you should at least be aware of this pattern breakdown.
Sector/Industry Focus
Don't lose sight of the absolute and relative breakout of the computer hardware space ($DJUSCR). This is an aggressive part of technology and seeing this group breaking out should be construed bullishly:
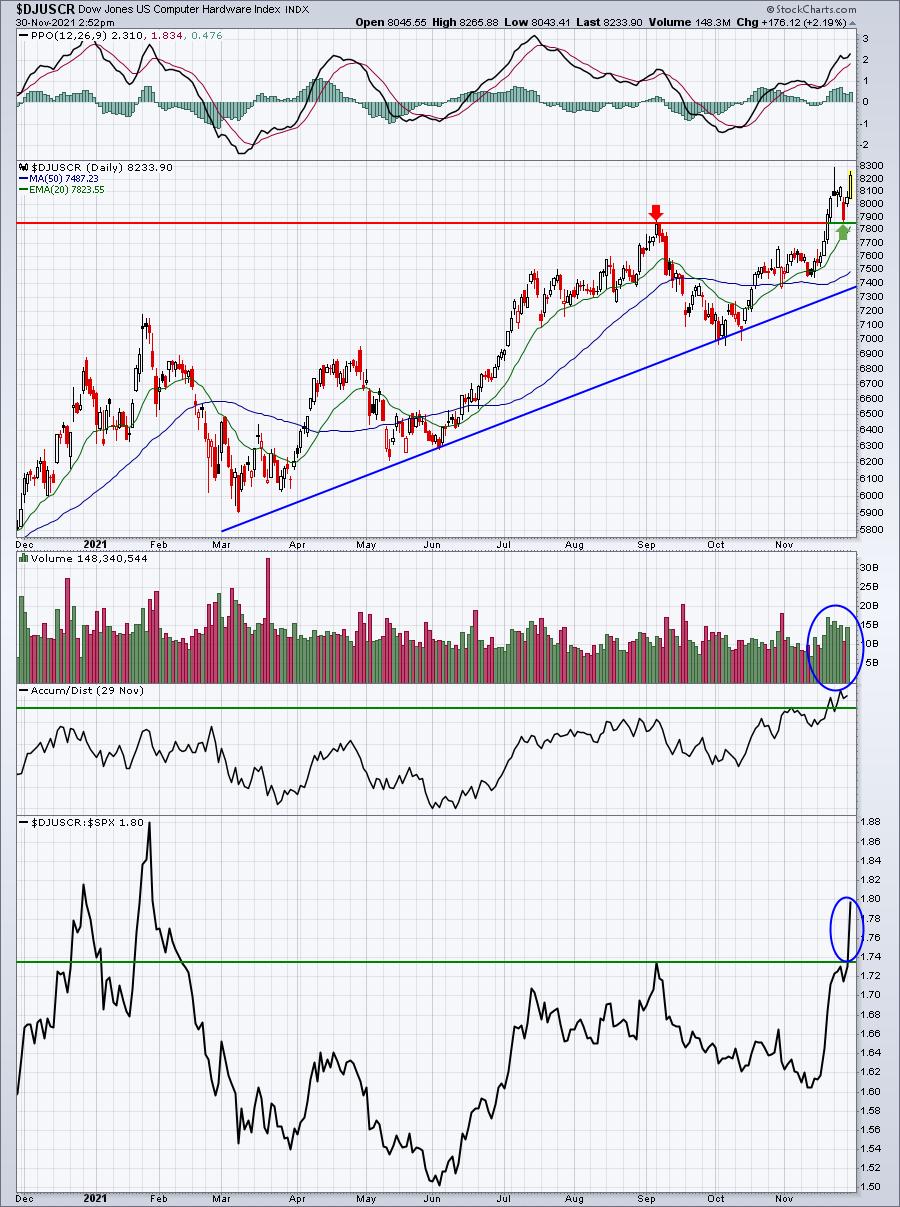
As I mentioned earlier, AAPL is performing very well today, helping to limit the overall damage on both the S&P 500 and NASDAQ. Another stock benefiting from this rotation is Synaptics (SYNA), which is slightly higher today. The AD lines on these stocks is strong as we're seeing further signs of accumulation in this area.
ChartLists/Strategies
I'm mostly a momentum trader, so looking at downtrending stocks isn't something that I spend a lot of time on. However, I know many of you prefer buying stocks that are not in "nose-bleed" territory. I just updated our Raised Guidance ChartList (RGCL) and here are stocks included on it that also are at or near key price or gap support:
UNVR:
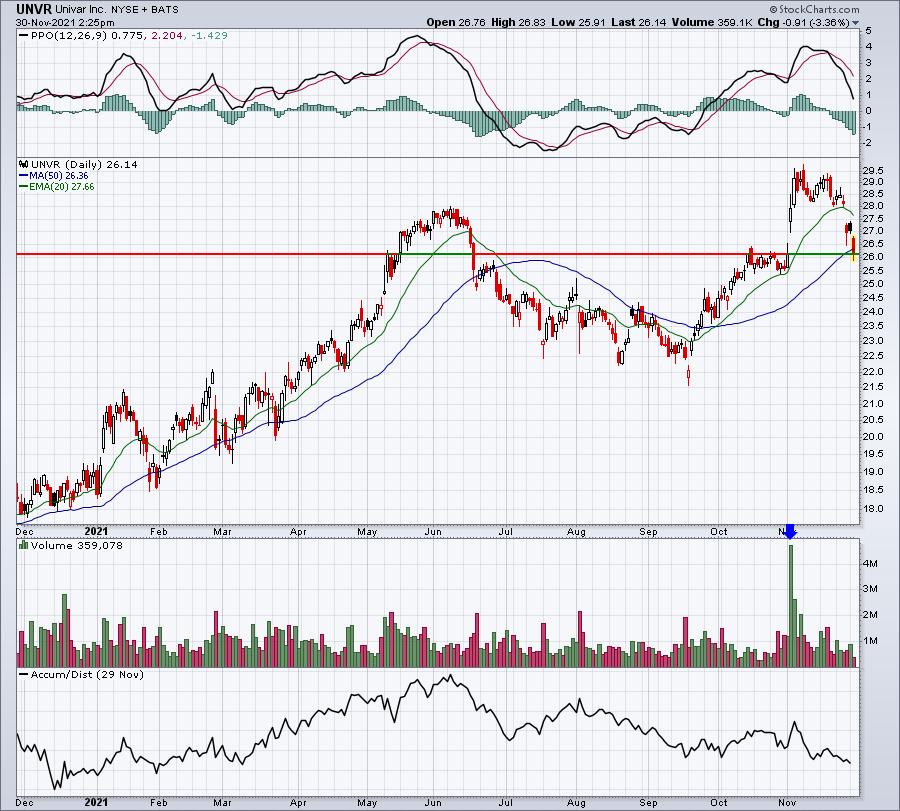
UNVR gapped higher on massive volume, but patience here has been a virtue as it's testing gap support today. A close below 26.18 would be a short-term issue. We're actually trading just beneath that level right now.
AMGN:
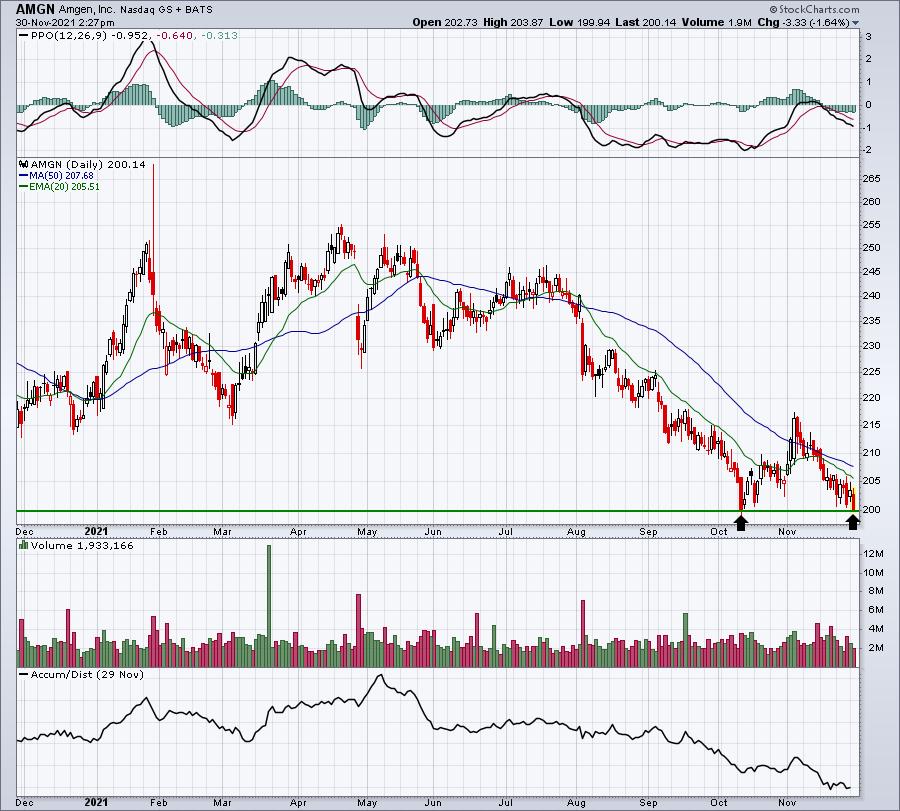
Double bottoms can be excellent entry levels. Of course, we need to see closing price support at 200.21 hold. Currently, we're just a fraction beneath it.
SMCI:
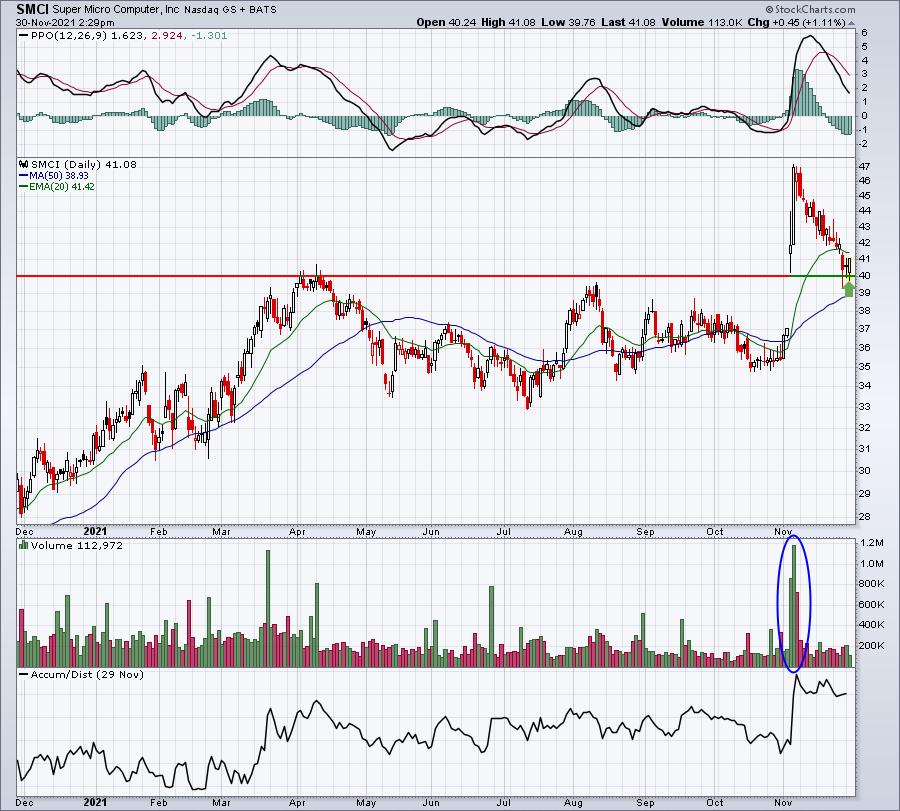
Huge volume accompanied the big gap up and breakout earlier in November. But again, patience has been rewarded as SMCI has fallen back to test key price support from the breakout above the April high.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Tuesday, November 30:
CRM, BNS, ZS, GFS, NTAP, HPE, AMBA, BOX, JKS, MOMO
Wednesday, December 1:
RY, SNOW, CRWD, SNPS, VEEV, OKTA, SPLK, ESTC, FIVE, PVH, DCI, DSGX, DOOO, SMTC, AI, PDCO, ZUO, GIII
Economic Reports
September Case-Shiller home price index: +1.0% (actual) vs. +1.1% (estimate)
September FHFA house price index: +0.9% (actual) vs. +1.0% (estimate)
November Chicago PMI: 61.8 (actual) vs. 68.4 (estimate)
November consumer confidence: 109.5 (actual) vs. 110.7 (estimate)
Happy trading!
Tom