
EB Daily Market Report - Wednesday, December 15, 2021
ChartLists Updated
The following ChartLists have been updated and are available for viewing/download on our website:
- December Max Pain
- Raised Guidance (RGCL)
- Short Squeeze (SSCL)
Executive Market Summary
- Futures were mixed overnight, but our major indices mostly opened flat
- The Fed meeting ends with a policy statement at 2:00pm ET; no interest rate change is expected, but the market's interpretation of wording changes from the last meeting will be critical
- Most commodities are lower, with silver ($SILVER, -1.73%) approaching its September and 18-month lows
- The U.S. Dollar (UUP, +0.07%) remains near its 18-month high - unusual if inflation is truly a problem
- The 10-year treasury yield ($TNX) is up 1 basis point to 1.45%, little changed prior to the Fed announcement
- Defensive sectors are higher, but that's about it; energy (XLE, -1.41%) and consumer discretionary (XLY, -1.19%) are the weakest sectors
- Steel ($DJUSST, -7.71%) is very weak as Nucor Corp (NUE, -11.57%) leads the S&P 500 to the downside
- All eyes are on the Fed
Market Outlook
We are less than an hour away from something. I'm not sure what that something is, but this has a much more interesting feel to it than prior Fed announcements. Inflation is the primary reason why. Growth stocks have been out of favor much of 2021, but especially over the past month. In the second week of November, the Dow Jones U.S. Small-Cap Growth Index ($DJUSGS) was at an all-time high. Today? It's testing 6-month lows:
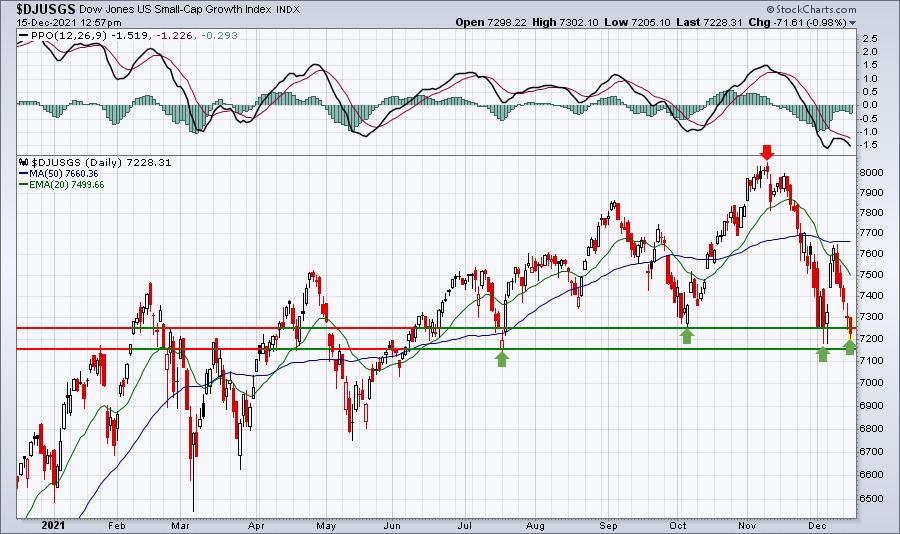
Technically, we're at a very critical area on this chart. Throw in the seasonality, which favors U.S. equities in the second half of December (today is the 15th) and that spices things up a bit. The annualized return of the S&P 500 since 1950 is broken down in December as follows:
- December 1-15: +1.80%
- December 16-31: +35.79%
That's a very wide disparity in performance and favors the bulls as today's close approaches.
Throw in max pain, which shows a TON of net in-the-money put premium on many of the more volatile technology names, and it would be easy to call for a big rally here. But we may have more pain to endure first. Let's see what the Fed has to say, but in the meantime, I'd remain very cautious. Only aggressive money should be invested here until we have a more definitive direction.
Sector/Industry Focus
One of the best ways to visualize the rotation to defensive stocks right now is to simply view the relative price charts of our four defensive sectors:
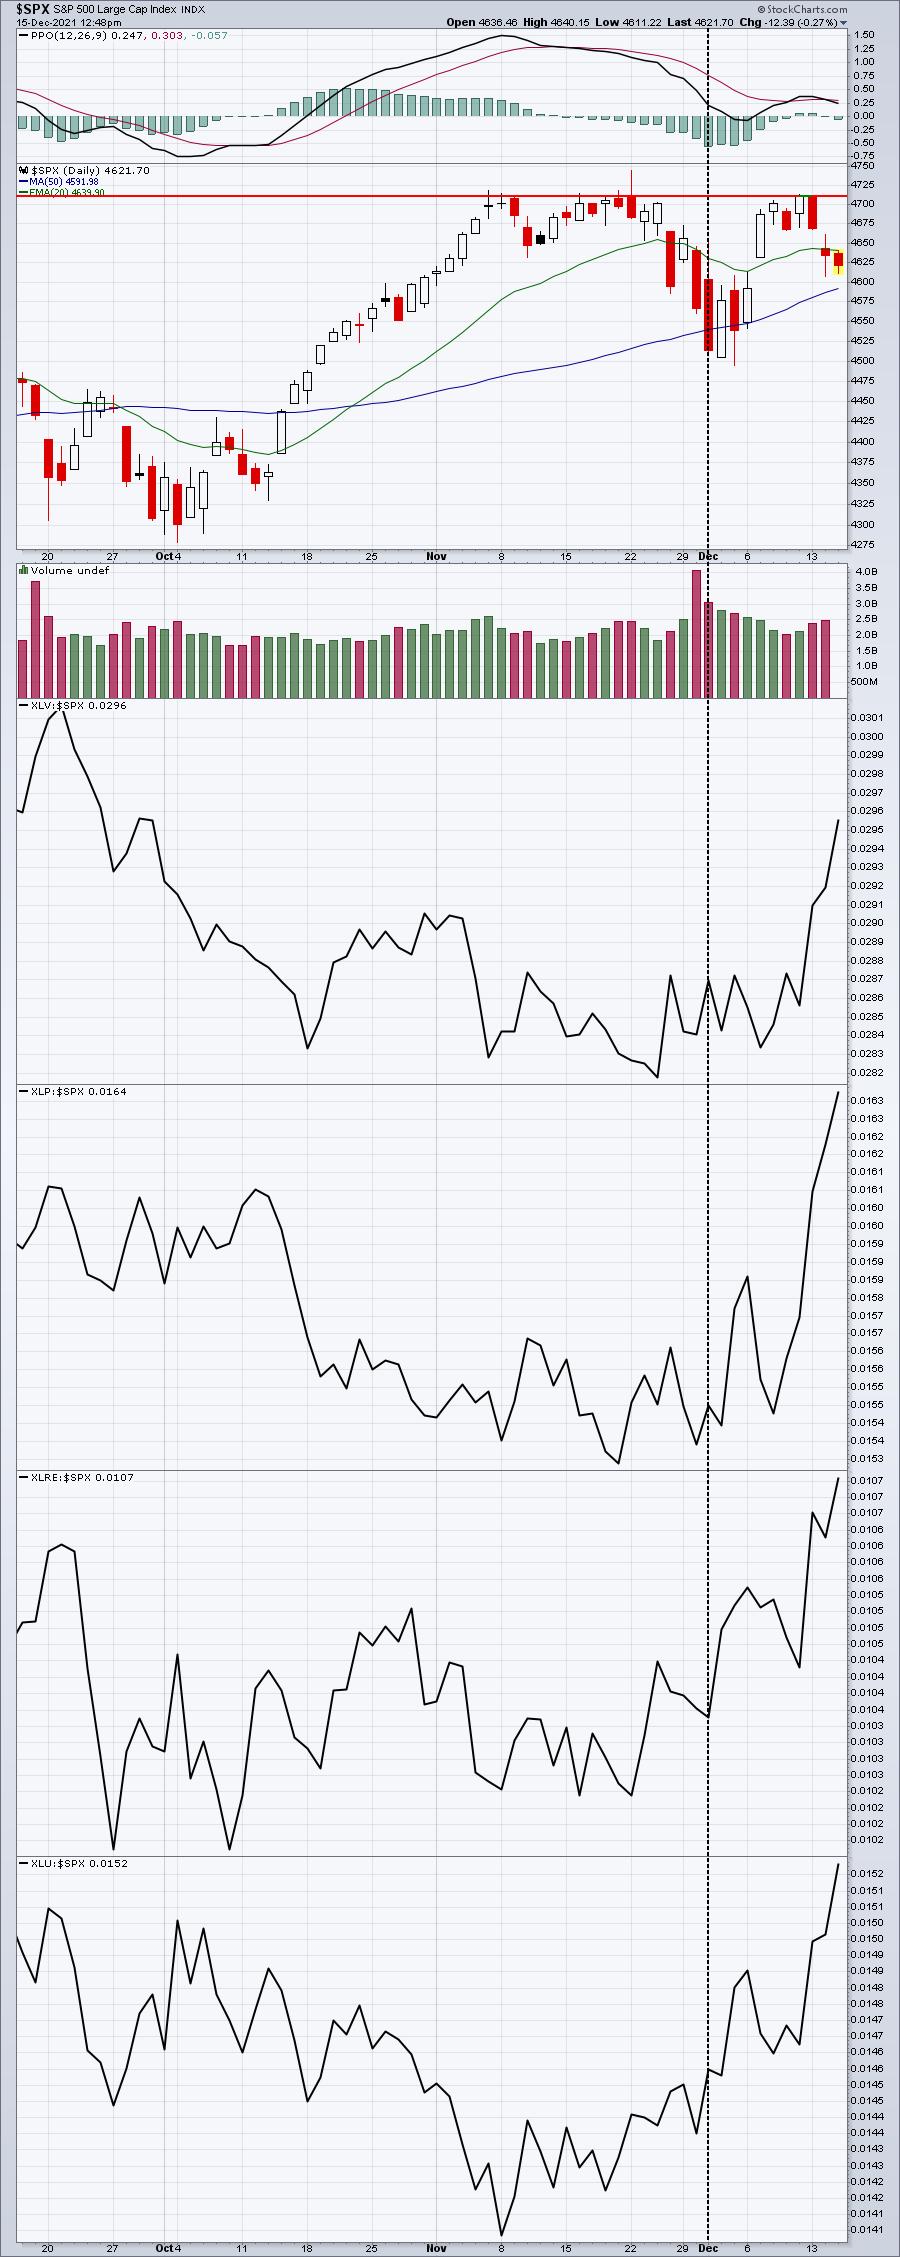
This latest rally on the S&P 500 was set up to fail. The question, though, is how long will it fail? I believe market participants have simply grown more cautious ahead of today's FOMC policy statement and I can't blame them. The short-term has been dicey since mid-November when we had our primary sentiment issue - rising VIX with rising S&P 500.
ChartLists/Strategies
The Fed announcement this afternoon creates the potential for huge reward in growth areas if we see a relief rally. That's a really big IF, however, and the risk that accompanies trading these stocks right now is significant. A safer place to trade is in those defensive sectors mentioned above. I ran a scan of stocks setting new 22 day highs (one month) with SCTRs > 90. Only 20 stocks were returned, underscoring how weak the market is right now. Here was the breakdown of these 20 stocks by sector:
- Health care: 9 (PFE, FHTX, TNDM, VIR, DGX, LLY, UNH, CNC, ABBV)
- Real estate: 4 (EXR, LSI, MAA, PSA)
- Consumer staples: 3 (DOGZ, CHD, PG)
- Technology: 3 (CCMP, LITE, RDWR)
- Financial: 1 (NAVI)
Here are the three I find most interesting:
CNC:
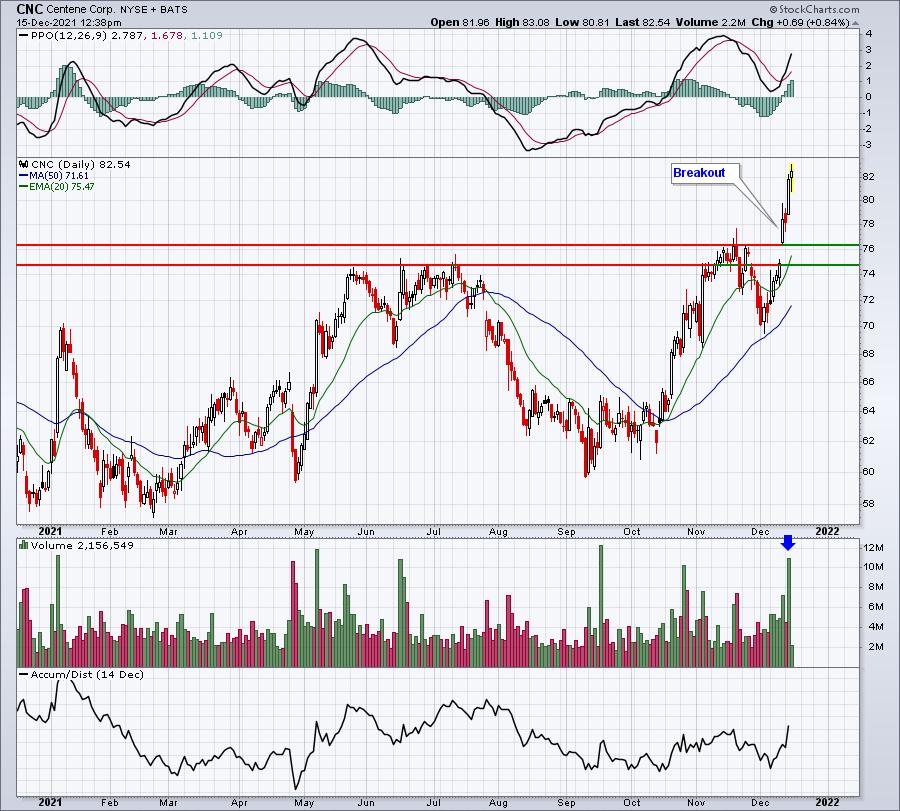
The AD line breaking to a 4-month high is adding to the bullishness of this breakout. Any future pullbacks into the upper 70s would be an interesting level for entry.
LLY:
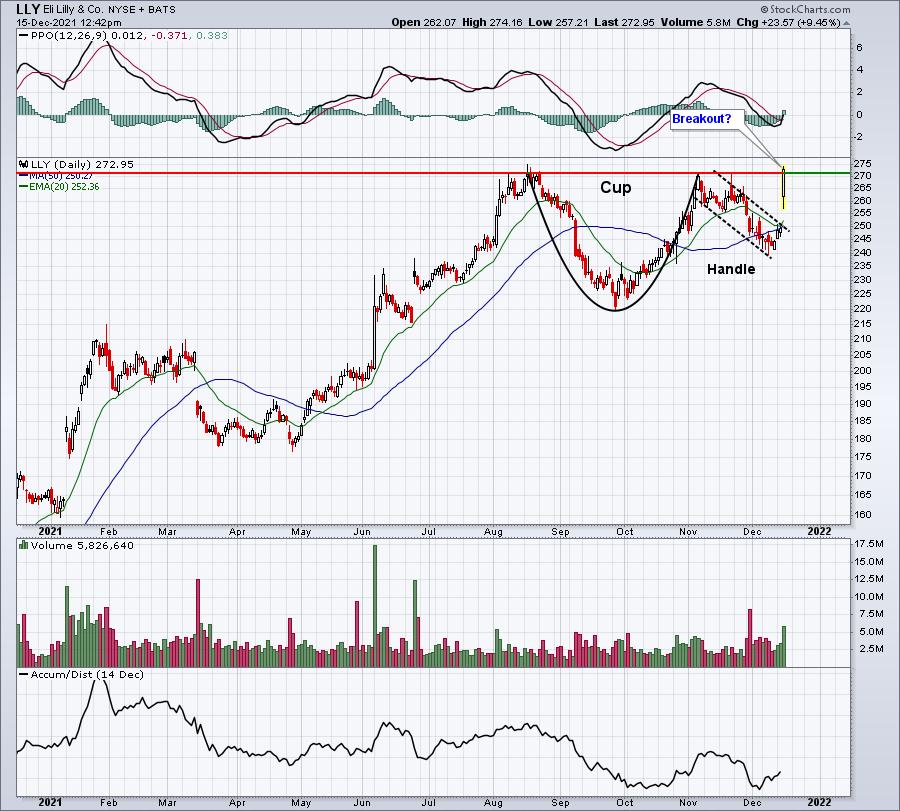
Today's volume is strong and would confirm a cup with handle breakout. The measurement on this pattern would be 320.
TNDM:
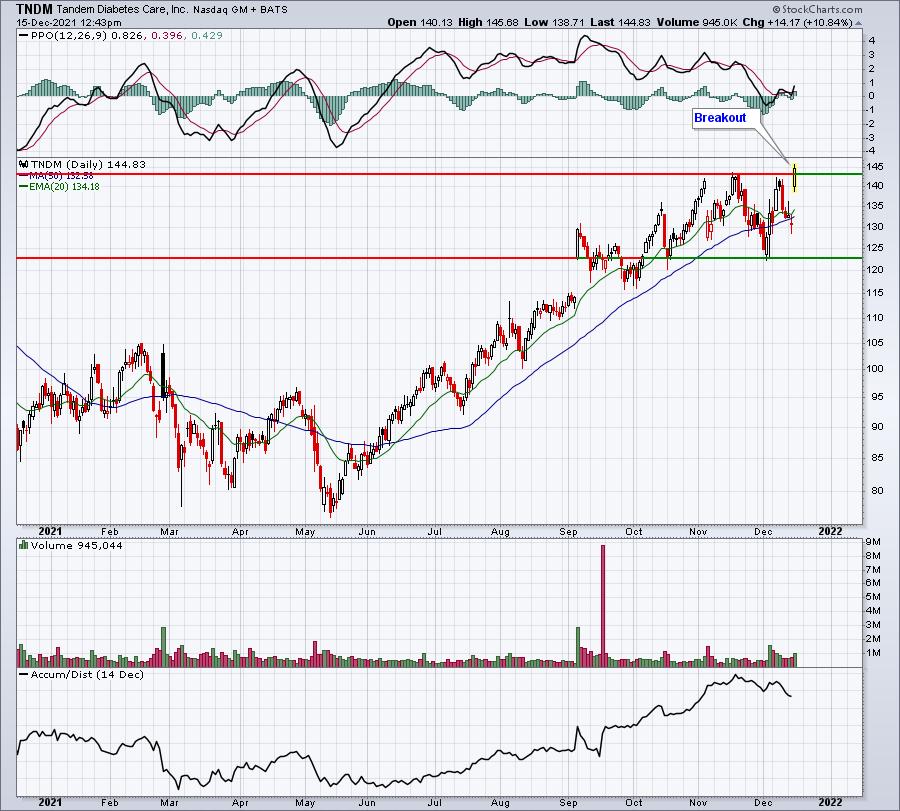
After a period of sideways consolidation, TNDM appears poised to make this breakout. It'll require a close today over 144. The recent consolidation did bring down the PPO to centerline support, so a breakout here would likely be sustainable.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, December 15:
LEN, HEI, NDSN, TCOM, TTC, JOBS, ABM
Thursday, December 16:
ADBE, ACN, RIVN, FDX, JBL, WOR
Economic Reports
November retail sales: +0.3% (actual) vs. +0.8% (estimate)
November retail sales less autos: +0.3% (actual) vs. +0.9% (estimate)
December empire state manufacturing: 31.9 (actual) vs. 25.5 (estimate)
December housing market index: 84 (actual) vs. 84 (estimate)
Happy trading!
Tom