
EB Daily Market Report - Thursday, December 16, 2021
ChartLists Updated
The following ChartLists have been updated and are available for viewing/download on our website:
- Strong AD (SADCL)
- Bullish Trifecta (BTCL)
Executive Market Summary
- Futures were strong overnight and we saw a modest gap higher across our major indices
- That follow through didn't last long, especially in the growth-oriented stocks
- Technology (XLK, -3.10%) and consumer discretionary (XLY, -2.13%) are both being sold off hard
- Six sectors are actually higher, including three of the four defensive sectors
- Financials (XLF, +0.96%) are moving higher today, despite the 10-year treasury yield ($TNX) falling four basis points to 1.42%
- Meanwhile, a weaker dollar (UUP, -0.35%) has buyers attracted to both materials (XLB, +0.79%) and energy (XLE, +0.71%)
- The tech-laden NASDAQ is down 400 points, erasing all of the gains made after Tuesday's Fed announcement
- The Volatility Index ($VIX), which fell nearly 5 points yesterday, has spiked nearly 12% higher today
- It's been a roller coaster ride for 24 hours, but the loser in all of this so far have been growth stocks
Market Outlook
It's been a crazy 24 hours since the Fed announcement. The Fed made it clear that they would speed up the tapering of bond purchases as there really was no further need at this time to boost economic activity. Given the rate of tapering discussed, the Fed is likely to be done buying bonds by March 2022. Furthermore, the Fed announced that they're likely to have a series of three interest rate hikes in 2022. I will go on record right now and say they'll probably raise once, but I'm not so sure about hikes #2 and #3. Once inflation peaks and begins to turn lower, I believe further rate hikes will be aborted.
Maybe the most interesting reaction to the Fed's announcement has been in the treasury market. The Fed just announced to the world that their pace of buying treasuries would be reduced significantly. You'd think we'd see bond sellers lined up, selling ahead of the Fed. Also, there's tremendous incentive to sell bonds if inflation is a a problem. So that's two HUGE reasons to be selling treasuries and driving the corresponding yields higher. Yet look at this chart of the 10-year treasury yield ($TNX):
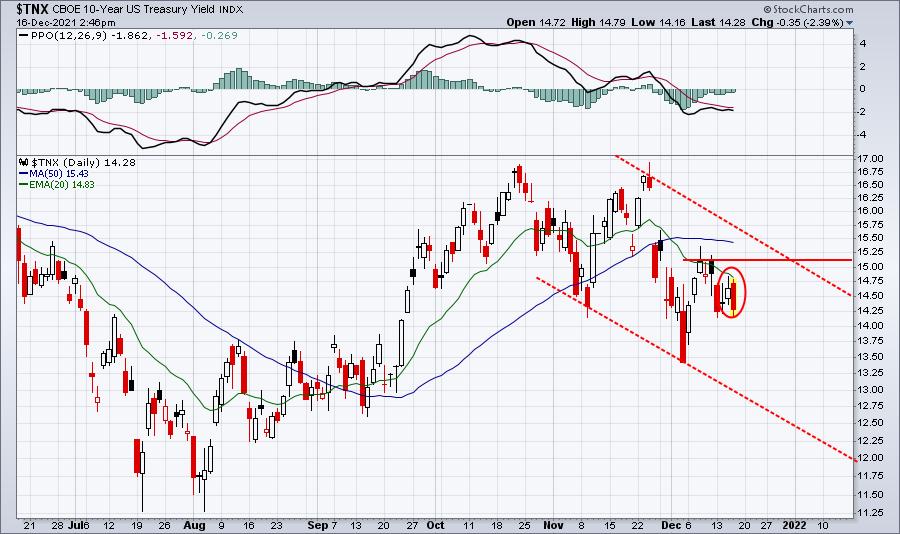
This looks like a bond market more concerned about a possible economic slowdown than it does one worried about inflation. The stock market's reaction - a relief rally, followed by further selling of growth stocks could be sending the same signal. So is the Fed sending out the wrong message? The credibility of the Fed is at stake right now. If the bond market turns out to be smarter than the Fed, it would not be a good look for Fed Chair Jay Powell.
Sector/Industry Focus
Money continues to pour into defensive sectors. I'm going to pull up that intraday chart again, highlighting the relative performance of the defensive sectors:
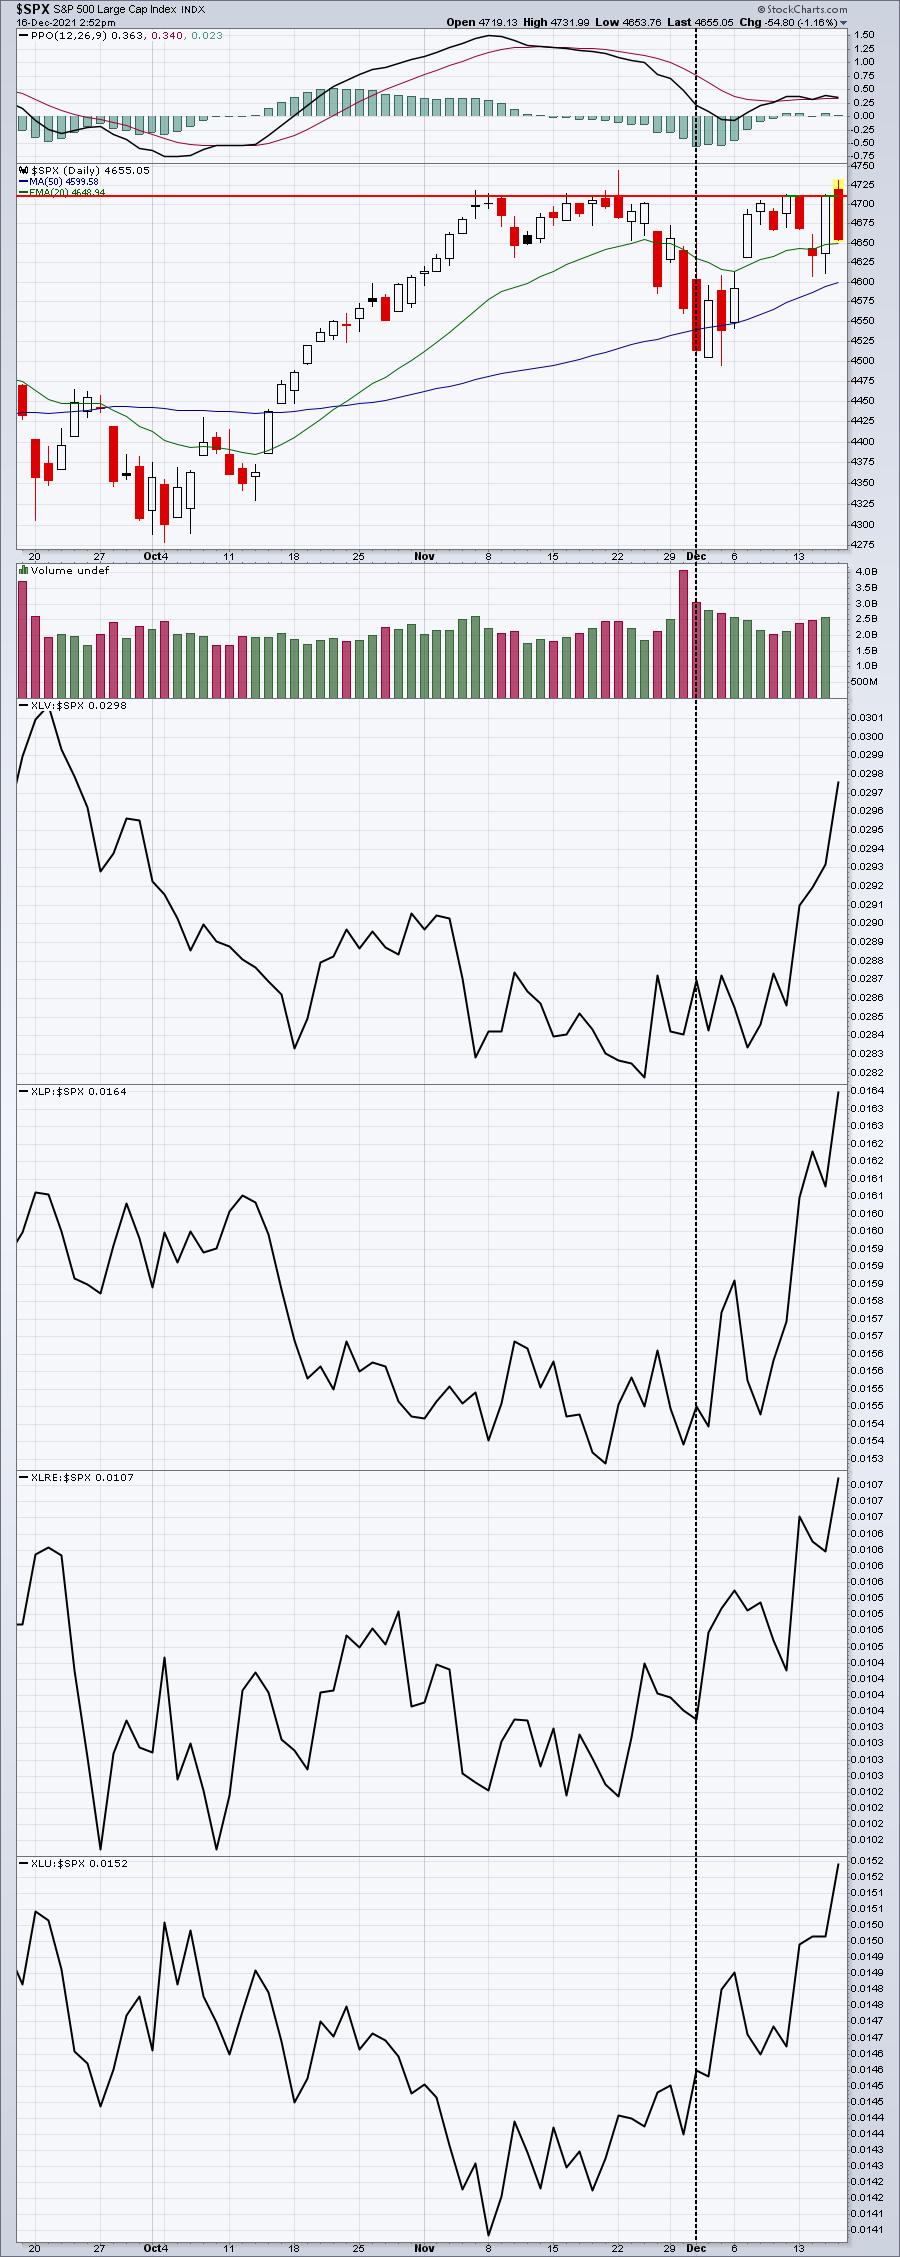
Until the market settles down, I'd continue to trade very cautiously and stick with what's working - the four defensive sectors above. Do the small cap growth stocks ($DJUSGS) hold this support zone:
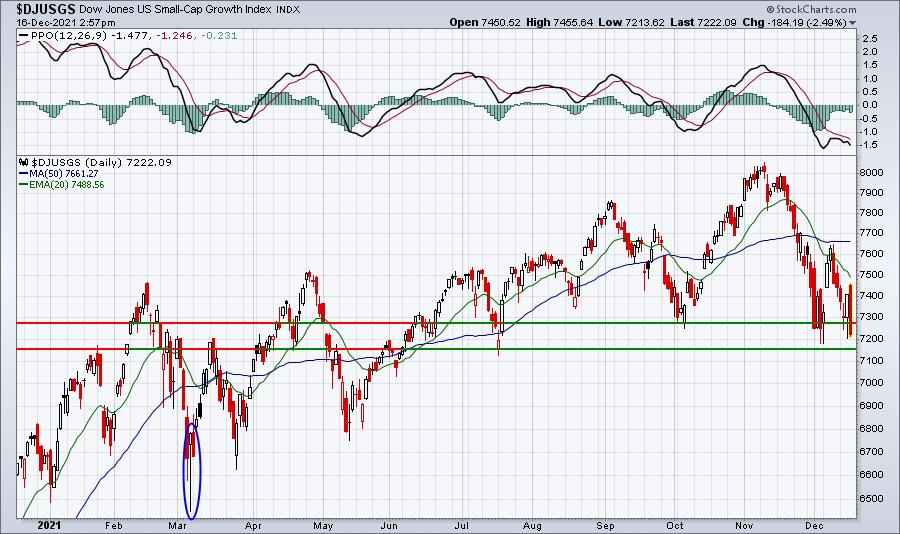
It may take a major selloff and huge reversal similar to the early-March low to mark a significant low. I wouldn't count that out.
ChartLists/Strategies
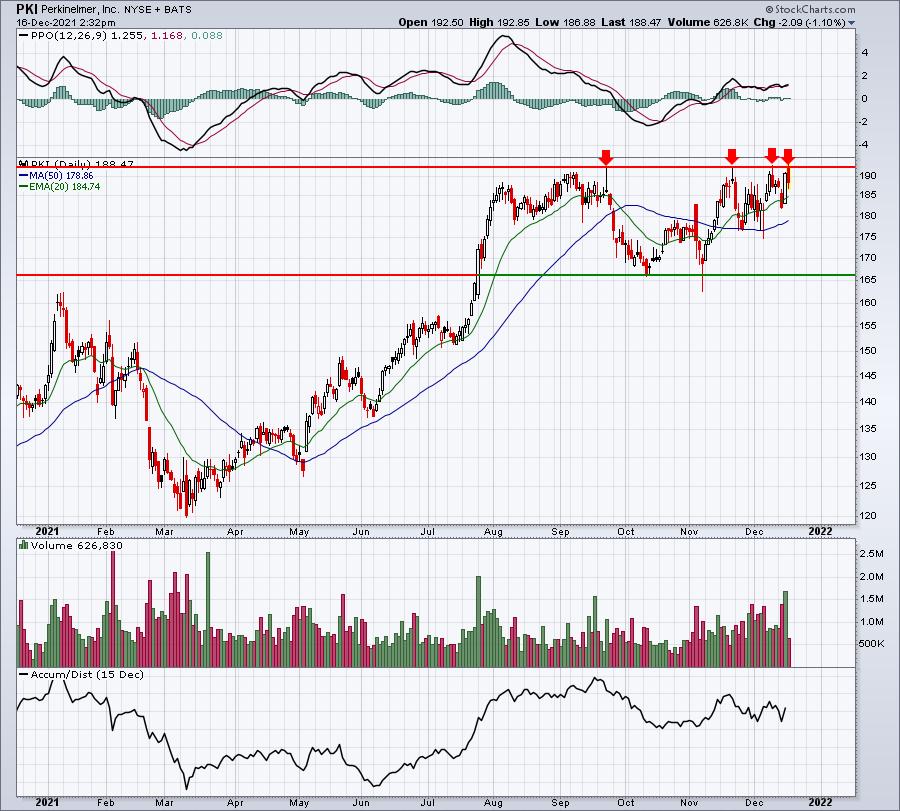
There will be plenty of time to trade growth names in technology and consumer discretionary. The big reversal today suggests we're not quite done with the near-term selling. Many of the key stocks in these two sectors are trading below where they were at 2pm ET on Wednesday, the time of the latest Fed announcement. Therefore, from a short-term trading perspective, I'd stick with the defensive groups for now. Here are 2 of those that we should keep an eye on:
PKI:
RGEN:
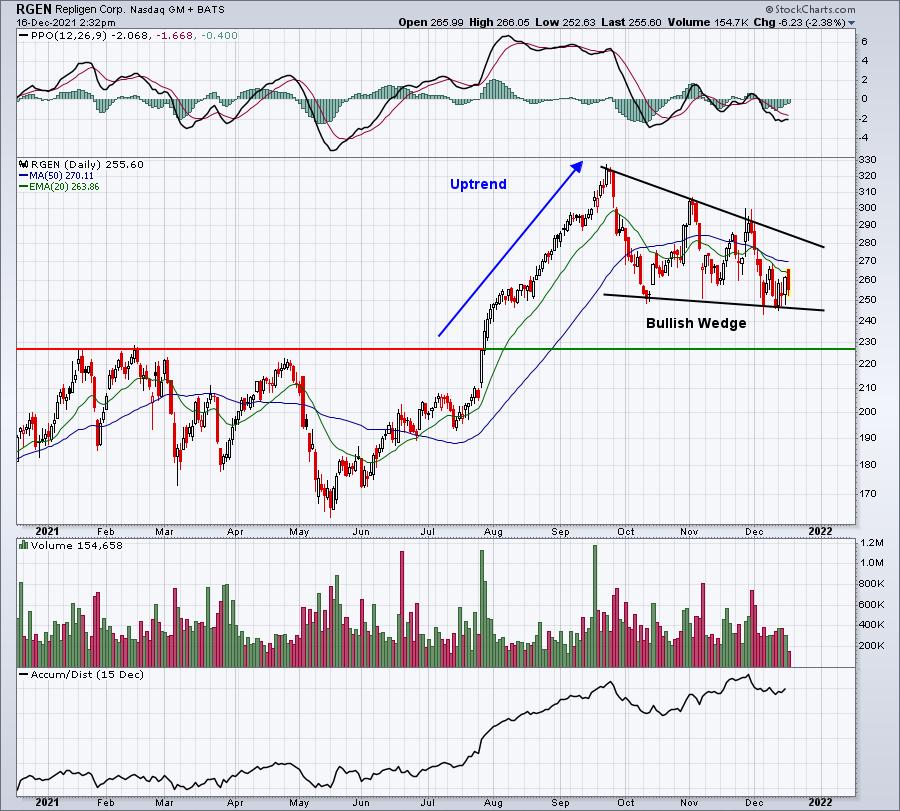
Both of these stocks are on our updated Bullish Trifecta ChartList (BTCL).
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, December 16:
ADBE, ACN, RIVN, FDX, JBL, WOR
Friday, December 17:
DRI, WGO
Economic Reports
November housing starts: 1,679,000 (actual) vs. 1,563,000 (estimate)
November building permits: 1,712,000 (actual) vs. 1,655,000 (estimate)
Initial jobless claims: 206,000 (actual) vs. 200,000 (estimate)
December Philadelphia Fed Manufacturing Index: 15.4 (actual) vs. 28.8 (estimate)
November industrial production: +0.5% (actual) vs. +0.7% (estimate)
November capacity utilization: 76.8% (actual) vs. 76.8% (estimate)
Happy trading!
Tom