
EB Daily Market Report - Monday, January 3, 2022
Market Vision 2022
Our annual Market Vision event will be held this Saturday, January 8th, beginning at 8:45am ET. There is NO COST to EB.com subscribers. In fact, we are not even offering the event to non-members. This is exclusive EarningsBeats.com content and we're happy to provide it as yet another benefit of being a loyal EarningsBeats.com member. So thank you!
We'll be sending out room instructions later this week. If you cannot attend on Saturday, no worries. We'll record the event and make it available for all EB.com members so that you can enjoy it at your convenience.
Executive Market Summary
- Futures were strong overnight and U.S. equities are starting off 2022 on the right foot
- The NASDAQ is showing relative leadership with a gain of nearly 1% on the session
- Tesla (TSLA, +12.27%) announced record 2021 deliveries and is leading the strong automobile industry ($DJUSAU, +10.71%); Ford (F, +4.72%) is breaking out in sympathy
- Apple (AAPL, +2.31%) has set a new all-time high and, in the process, topped $3 trillion in market cap on an intraday basis - the first company in history to do so
- The 10-year treasury yield ($TNX) has surged 12 basis points to 1.63%, one of the strongest moves in the TNX in recent memory
- Energy (XLE, +2.79%) is the top performing sector as crude oil prices ($WTIC, +1.13%) are on the rise
- Consumer discretionary (XLY, +2.54%) is strong given the huge rise in auto shares; financials (XLF, +1.15%) are benefiting from the higher treasury yields
- 6 sectors are lower, however, led by defensive groups; real estate (XLRE, -1.45%) and health care (XLV, -1.38%) are the hardest hit
Market Outlook
Happy New Year!
The XLY:XLP ratio has taken a bit of a tumble as we closed out 2021, but the longer-term relationship here does still remain bullish. I wouldn't be surprised to see discretionary stocks outperform in January because of the recent relative weakness in November/December:
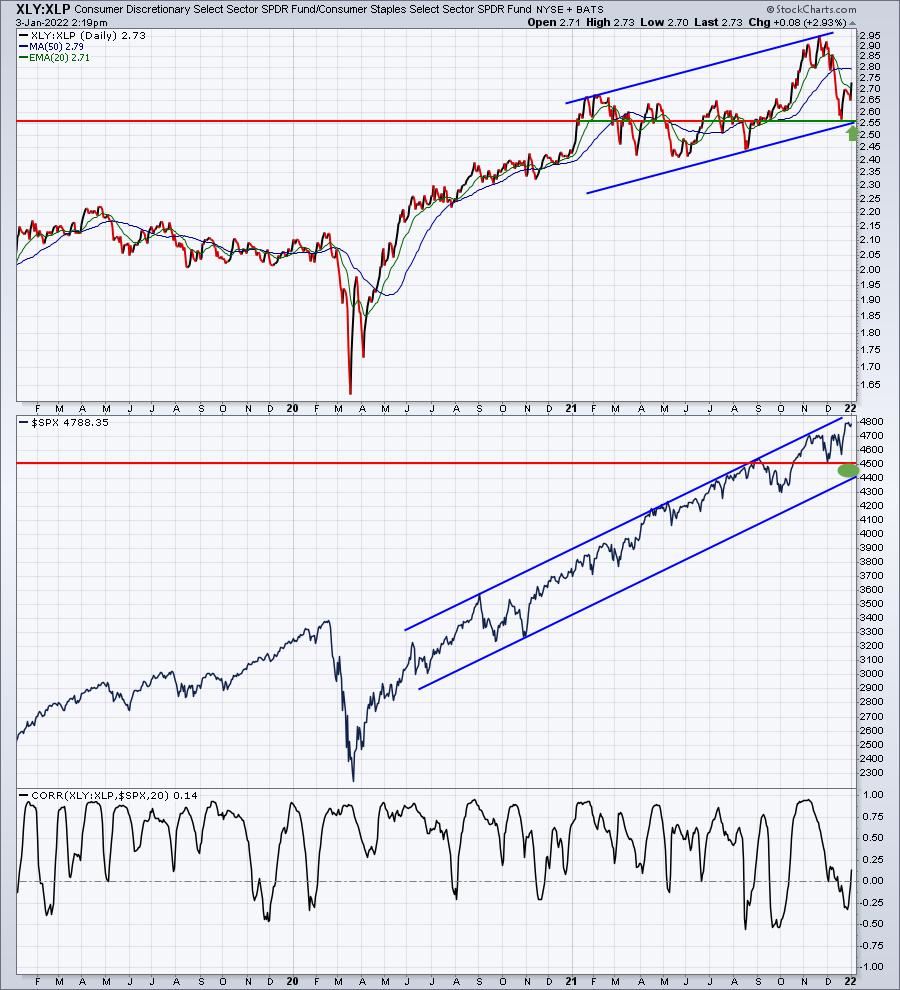
We've seen this relative behavior before. It's normally associated with market issues as money understandably rotates towards safety. In Q4 2018, it was the trade war. In March 2020, it was COVID-19. In February-May 2021, it was the big spike in inflation. As we head into 2022, there remain concerns about higher inflation and interest rates, including the Fed's announcement of its swift tapering of bond purchases. If the XLY:XLP ratio were to break the channel support line, that would be more of an intermediate-term red flag for U.S. equities. Right now, I'm ok with the relative pullback in Q4 2021.
Take particular note of the very tight positive correlation between the direction of this relative ratio and the direction of the benchmark S&P 500. Watching consumer stocks and their relative performance is absolutely one of the best measures to assess the sustainability of a market advance. The fact that the S&P 500 made new all-time highs last week, and in recent weeks, without the relative strength of discretionary stocks is a concern no doubt. But I don't believe the concern is a long-term one. It simply adds to the short-term uncertainty that U.S. equities face as we start 2022.
Sector/Industry Focus
If we look at the large cap technology ETF (XLK) and the small cap technology ETF (PSCT) and compare both to the S&P 500, I think it'll help to explain a primary trading theme in 2021. Check out this chart:
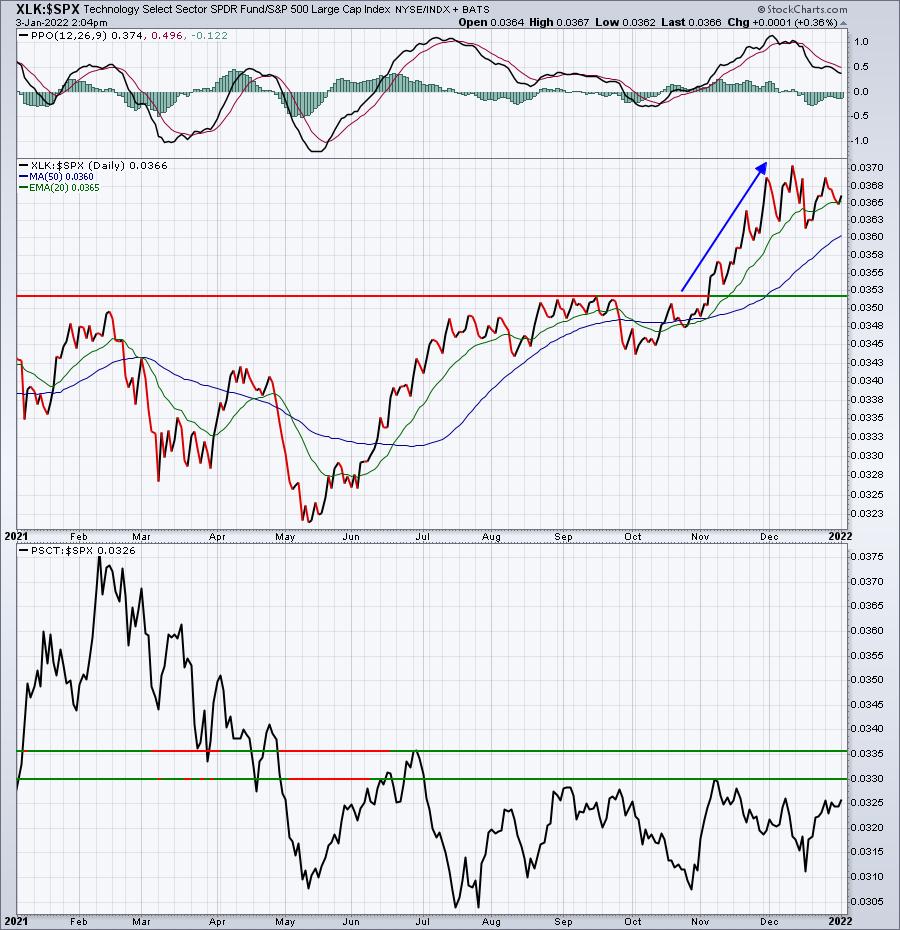
So if you've been trading large cap tech names like AAPL, MSFT, and others, you've likely performed much, much better than if you've been sticking more with mid cap or small cap names. This theme continues to hold true right into 2022 and will be worth watching as January unfolds.
ChartLists/Strategies
I remain very defensive at the moment, not really feeling compelled to trade too much. However, if you do want to trade on the long side, finding stocks making breakouts to 52-week highs with low SCTRs (ensures that the stock is likely not too overbought) and pulling back closer to key support would probably we the way I'd go. Here are 3 such stocks today:
ITW:
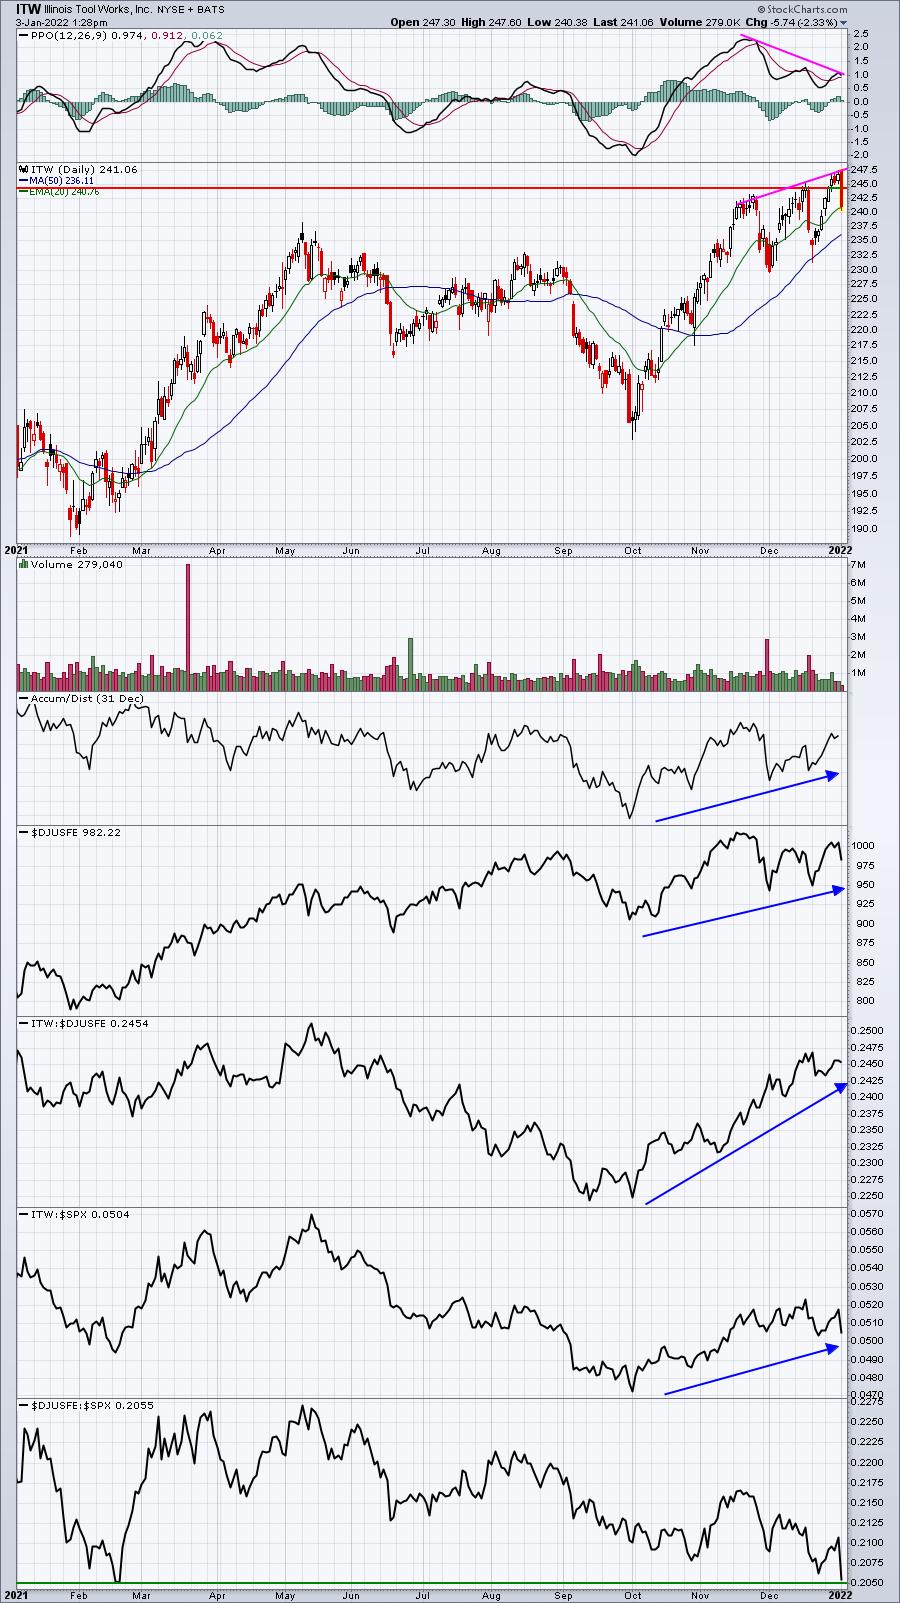
ITW is showing relative strength against its industrial machinery ($DJUSFE) peers, while its industry group is challenging relative support vs. the S&P 500. If the DJUSFE rebounds on a relative basis off support, ITW appears poised to benefit. An aggressive strategy would be to enter here and exit on any close beneath the 20-day EMA, keeping the potential for losses small. A more defensive way to trade ITW would be to use weakness to accumulate. So you could consider buying 1/2 here and the other 1/2 on a 50-day SMA test. Then a stop could be considered beneath the recent lows - perhaps a close beneath 229.
MCD:
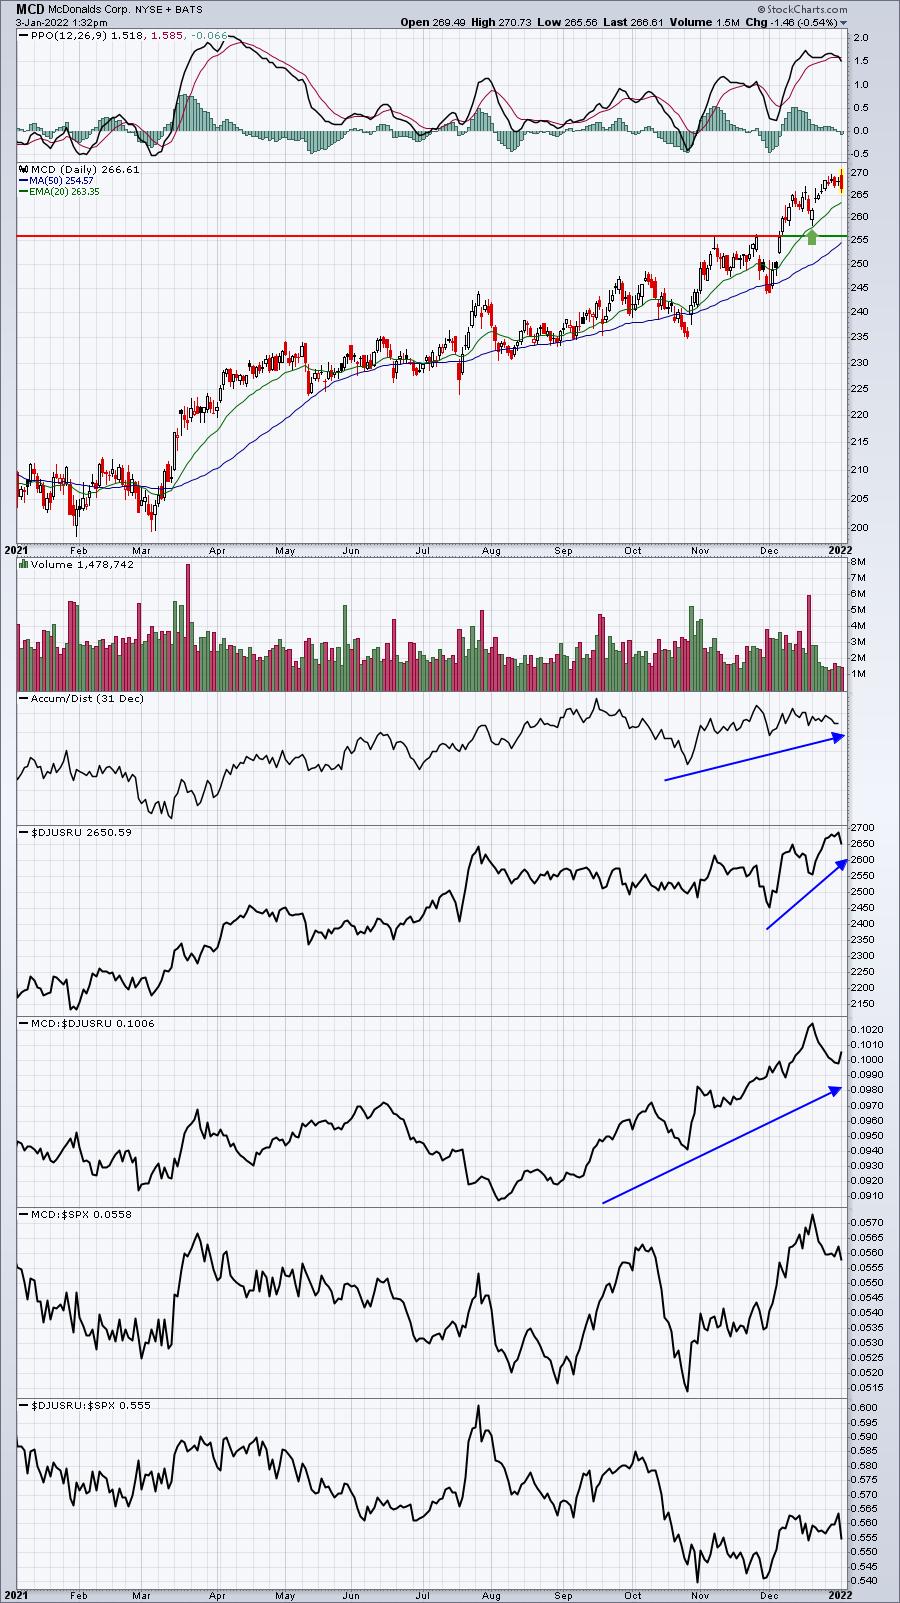
I love the recent technical behavior of MCD. Restaurants & bars ($DJUSRU) just broke out and MCD is showing considerable leadership in the space. MCD broke out and then had a successful 20-day EMA test afterwards. This points to further gains ahead.
DOV:
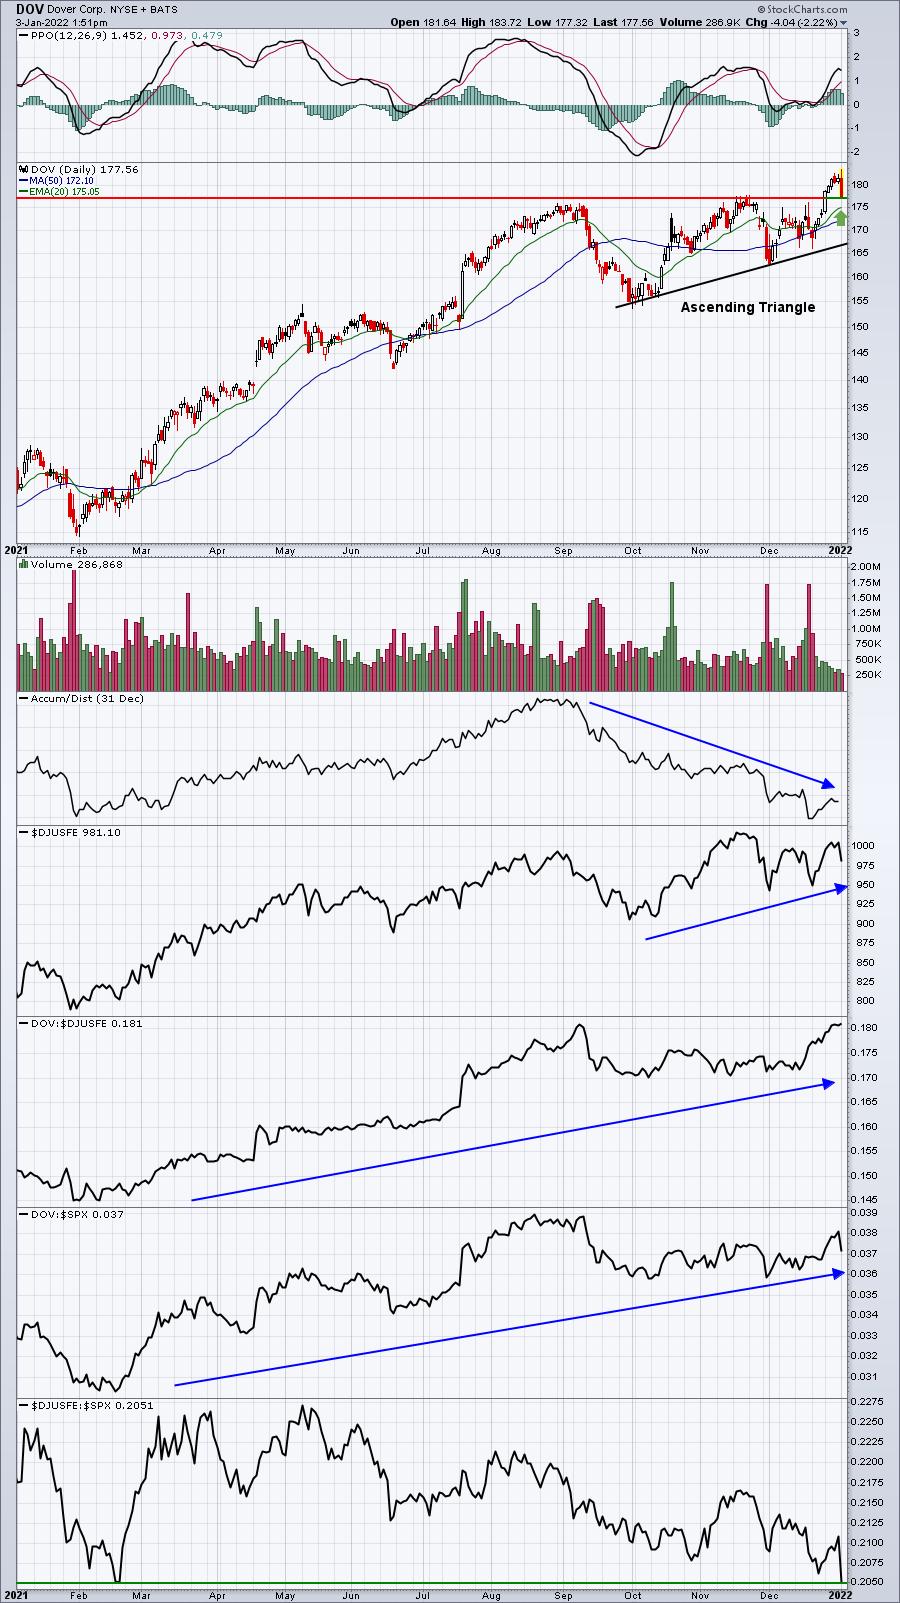
DOV is also in the industrial machinery ($DJUSFE) industry. The bullish argument here is the recent ascending triangle breakout that measures to roughly 200, but I'm concerned about the sudden nosedive in the AD line. Therefore, I'd be more likely to keep a very tight stop here on any close beneath the 20-day EMA.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Monday, January 3:
None
Tuesday, January 4:
SGH
Economic Reports
December PMI manufacturing: 57.7 (actual) vs. 57.8 (estimate)
November construction spending: +0.4% (actual) vs. +0.6% (estimate)
Happy trading!
Tom