
EB Daily Market Report - Thursday, January 13, 2022
ChartList Updates
We have updated two more ChartLists today:
- Strong ETF ChartList (SETFCL)
- Raised Guidance ChartList (RGCL)
I'll be looking to update the Strong AD ChartList (SADCL), which, in turn, will lead to an update of the Bullish Trifecta ChartList (BTCL). For newer members, the BTCL features stocks that are included on the Strong Earnings ChartList (SECL), RGCL, and SADCL. In my view, these truly are great trading candidates as they've reported strong results, raised guidance, and also show solid signs of accumulation.
Executive Market Summary
- Futures were higher across the board this morning, but strength only lasted for the first 30 minutes
- Small caps ($SML, +0.35%) and mid caps ($MID, +0.04%) are hanging onto gains, while the NASDAQ has dropped more than 300 points, or 2.07%
- The Volatility Index ($VIX) has surged more than 11% today, nearing 20
- Earnings season kicks off tomorrow morning with JP Morgan (JPM, +0.11%), Wells Fargo (WFC, -0.52%) and Citigroup (C, +0.85%) set to report; WFC, by far, is the best relative performer among the three
- Cryptocurrencies and most commodities are lower on today's session as the dollar (UUP, -0.10%) attempts to reverse higher off its opening gap lower
- Technology (XLK, -2.07%) and consumer discretionary (XLY, -1.55%) are both very weak today
- Meanwhile, defensive groups are outperforming, including today's best sector - utilities (XLU, +0.47%)
Market Outlook
We continue to see a steady decline in how discretionary stocks (XLY) are performing relative to staples stocks (XLP) within the consumer space. We're still clearly in a relative uptrend, but the latest push higher in the S&P 500 in December occurred with the XLY:XLP ratio declining. Here's a chart to illustrate:
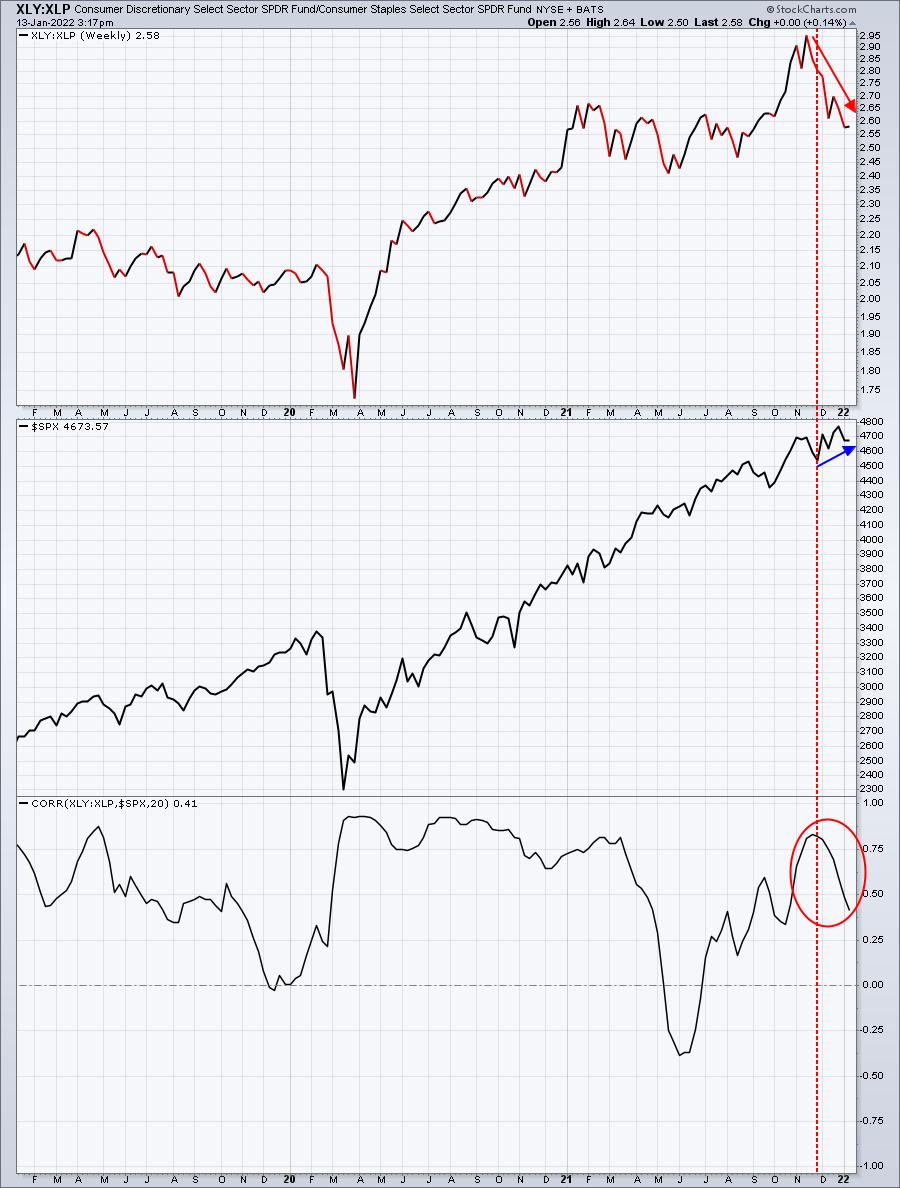
The red circle highlights the disconnect right now between the S&P 500 and the XLY:XLP ratio. One of my favorite ways to determine the sustainability of any S&P 500 rally is to see if Wall Street continues to remain in a "risk-on" type environment. That would mean a XLY:XLP ratio that climbs. Instead, we're seeing the opposite.
Be careful.
Sector/Industry Focus
Yesterday I pointed out that growth stocks were losing momentum, especially in the mid cap and small cap spaces. Well, that's grown much worse today and large cap growth has joined the party to the downside. Here's the chart I featured yesterday, updated with today's action:
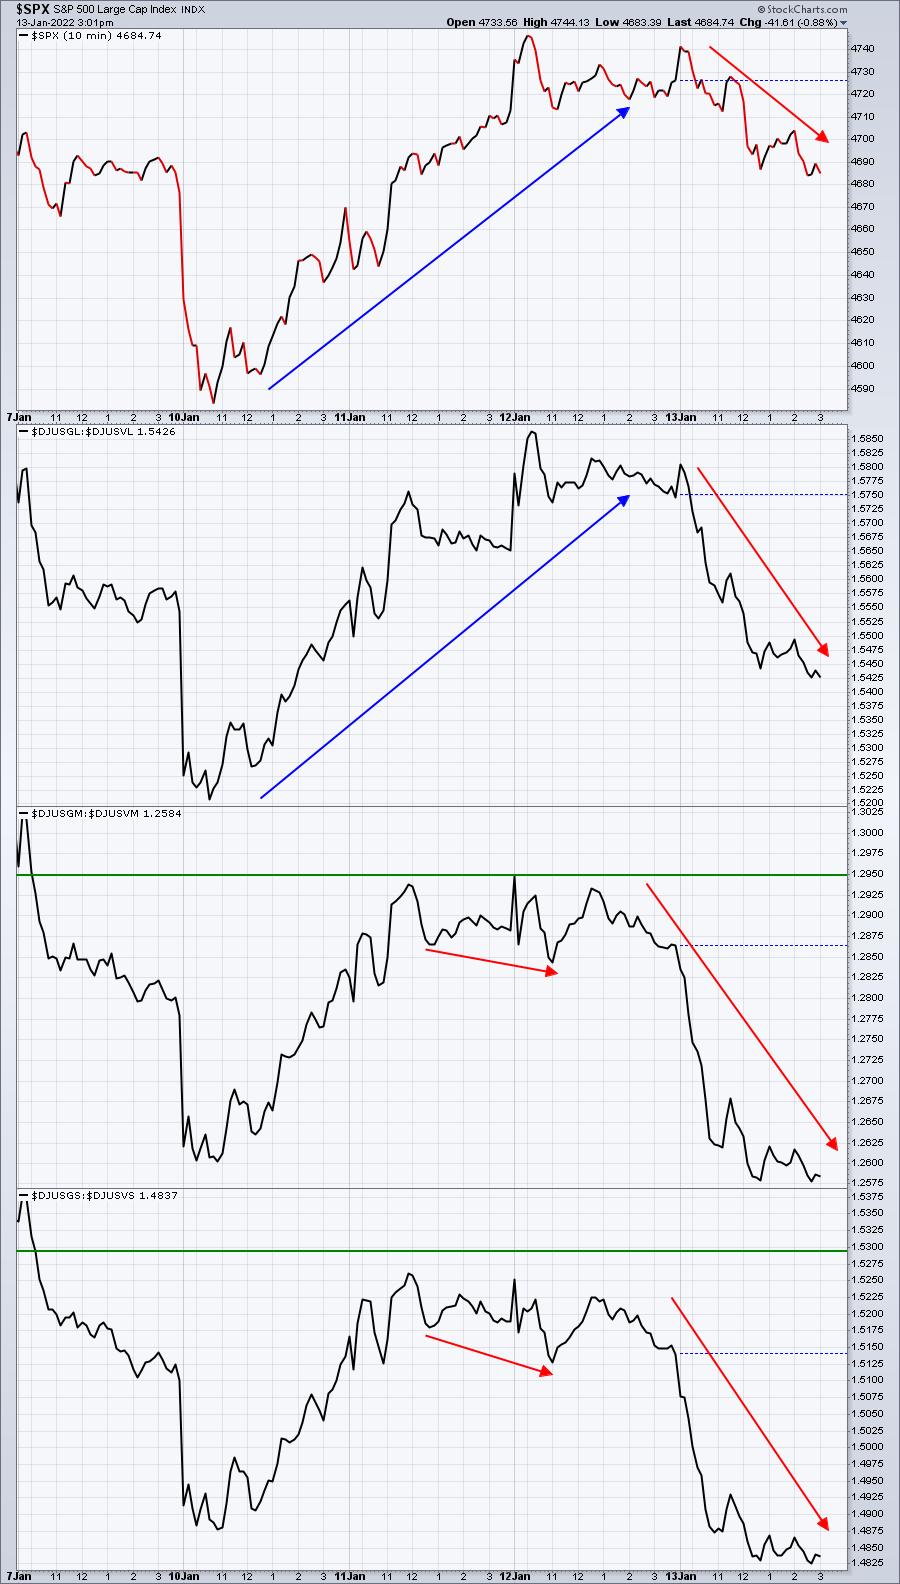
While the overall market remains well above its intraday low on Monday, the DJUSGS:DJUSGV (small cap growth vs. value ratio) was unable to hold its relative support from Monday. In other words, we're seeing further deterioration among small cap growth names.
ChartLists/Strategies
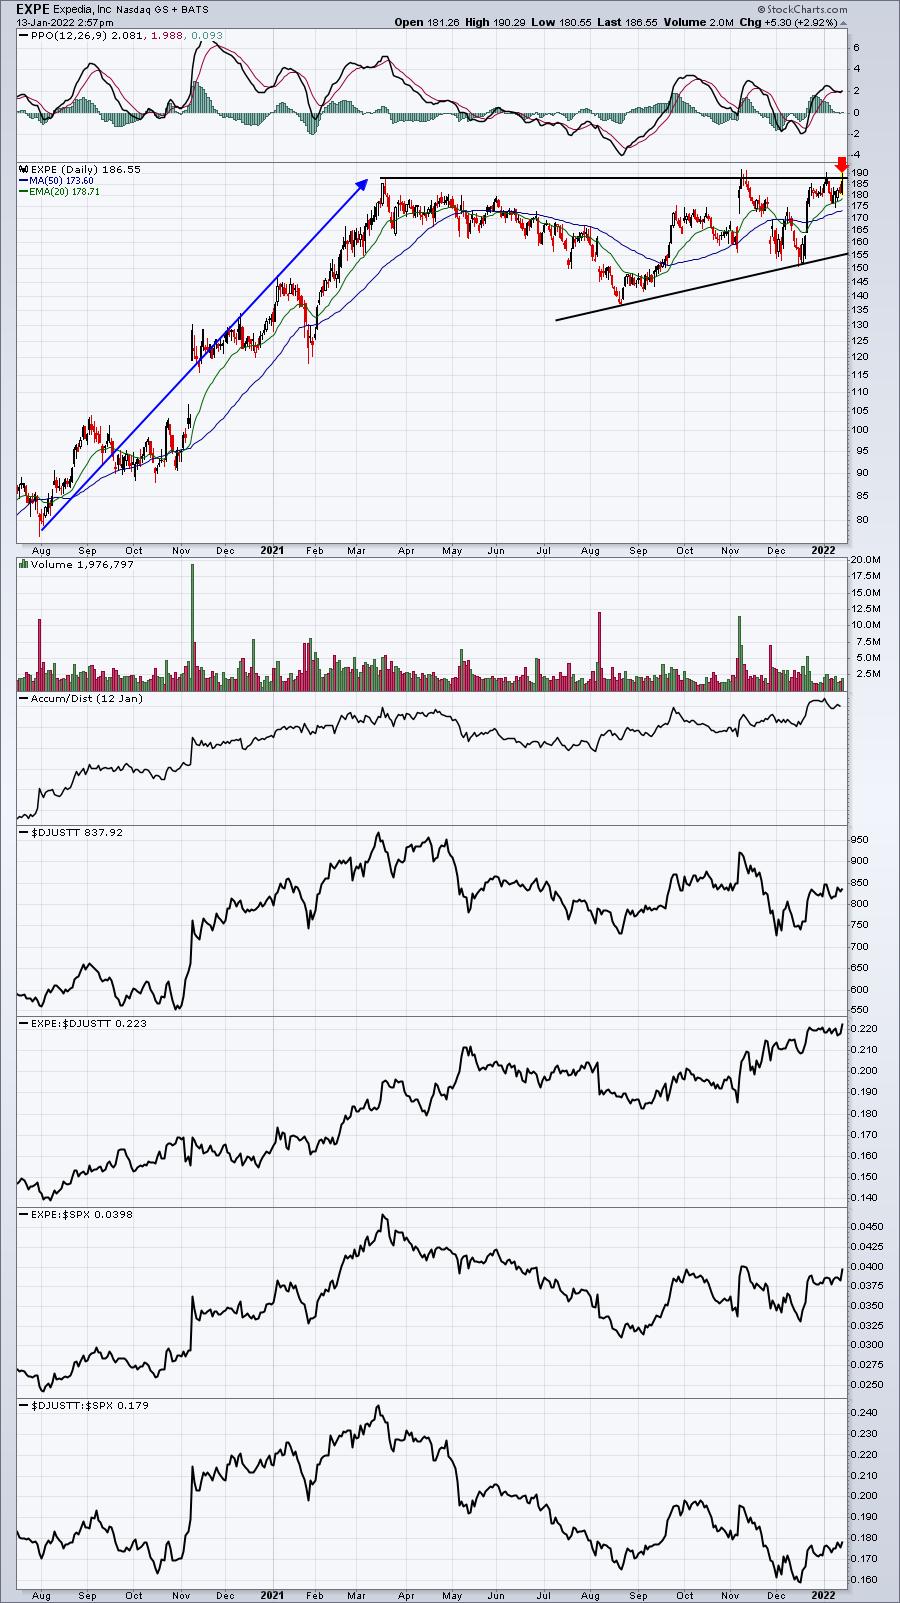
There were plenty of headlines today, discussing Omicron and the hospitals at or near capacity across the country. While this remains a health care issue, it is not a financial issue. In fact, Expedia (EXPE), a travel company, is challenging major overhead resistance (red arrow) in a bullish ascending triangle pattern, which I had recently discussed. Here's a refresh of the chart:
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, January 13:
DAL
Friday, January 14:
JPM, WFC, C, BLK, FRC
Economic Reports
Initial jobless claims: 230,000 (actual) vs. 205,000 (estimate)
December PPI: +0.2% (actual) vs. +0.4% (estimate)
December Core PPI: +0.5% (actual) vs. +0.5% (estimate)
Happy trading!
Tom