
EB Daily Market Report - Friday, January 14, 2022
Monday Event
The stock market is closed on Monday in observance of Martin Luther King Day. We will be hosting our "Q4 Earnings: Sneak Preview" at 4:30pm ET that afternoon. We will send room instructions out on Monday before the event. Hope to see you there!
I live 20 minutes south of Charlotte, NC and we're expecting a major winter storm all day Sunday that could bring with it heavy snow, sleet, and freezing rain. If I lose power, we'll need to reschedule this event or combine it with another event next week since we already have a full schedule.
Executive Market Summary
- Futures were lower as we moved into the open this morning
- Volatility ($VIX) is slightly higher, though it was much more so earlier in the session
- Key banks reported quarterly results to kick off earnings season: JP Morgan (JPM, -5.85%) and Wells Fargo (WFC, +2.93%) saw completely different market reactions
- Most commodities are lower, though crude oil ($WTIC, +2.22%) is up nearly $2 today and is challenging $84 per barrel
- Energy (XLE, +1.66%) is easily the best performing sector as technology (XLK, +0.16%) and communication services (XLC, +0.07%) are the only other two sectors in positive territory
- Real estate (XLRE, -2.07%) is struggling, along with financials (XLF, -1.65%)
- 11 of 12 industry groups within financials are lower today, despite a surge of 6 basis points higher in the 10-year treasury yield ($TNX)
- Economic reports were extremely weak today, especially December retail sales, which missed by a mile; this makes the surge higher in the TNX interesting
Market Outlook
The Fed is out frequently now with their interest rate hike rhetoric. I have to wonder if they saw December retail sales, which fell 1.9% vs. consensus estimates of +0.0%. Or how about industrial production for December that was expected to gain 0.3%, but instead fell by 0.1%. I'm sticking to my consistent prediction that inflation will peak in March or April. If that's the case and economic reports come in weaker than expected, I just don't see these 3-4 rate hikes in 2022.
Inflation usually results in a gain in gold (GLD, -0.25%) and a loss in the dollar (UUP, +0.29%), but the opposite is occurring today with those weak economic reports.
But let's get back to that awful retail sales report. The widely-diversified SPDR S&P Retail ETF (XRT) is getting clobbered today on this retail news. If strong consumer demand is expected in the weeks and months ahead, someone forgot to tell Wall Street. Check out this chart of the XRT and a few of the retail-related industry groups:
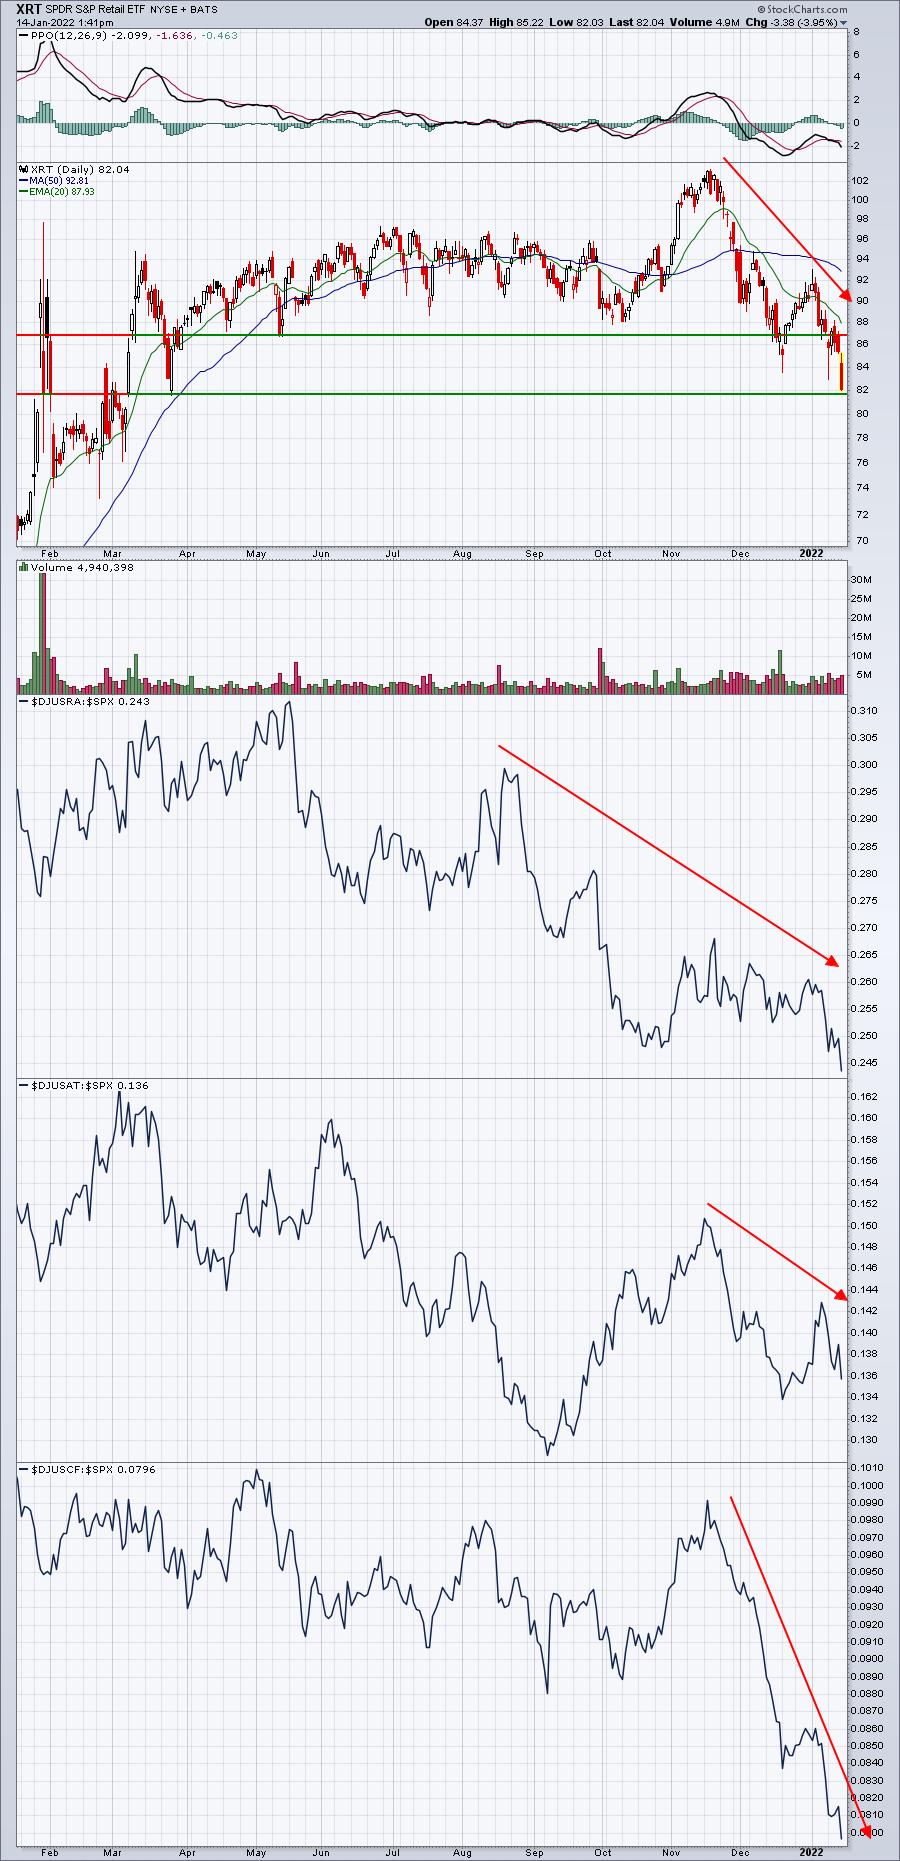
Of the 10 worst industry groups today, 7 of them are in consumer discretionary (XLY). The group is absolutely being torched. Look at the performance of the areas in the chart above. Does this look like Wall Street is enamored by the potential of huge consumer demand?
Sector/Industry Focus
Furnishings ($DJUSFH) and footwear ($DJUSFT) are two industry groups in consumer discretionary that are now battling to remain above key support:
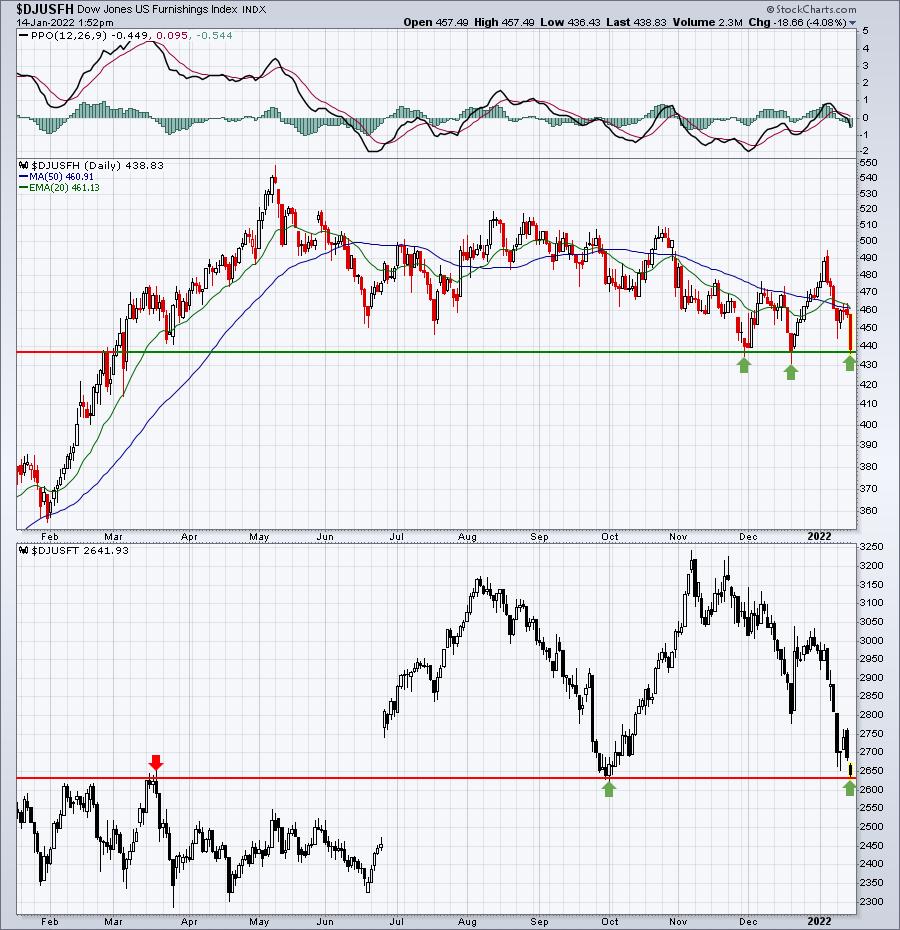
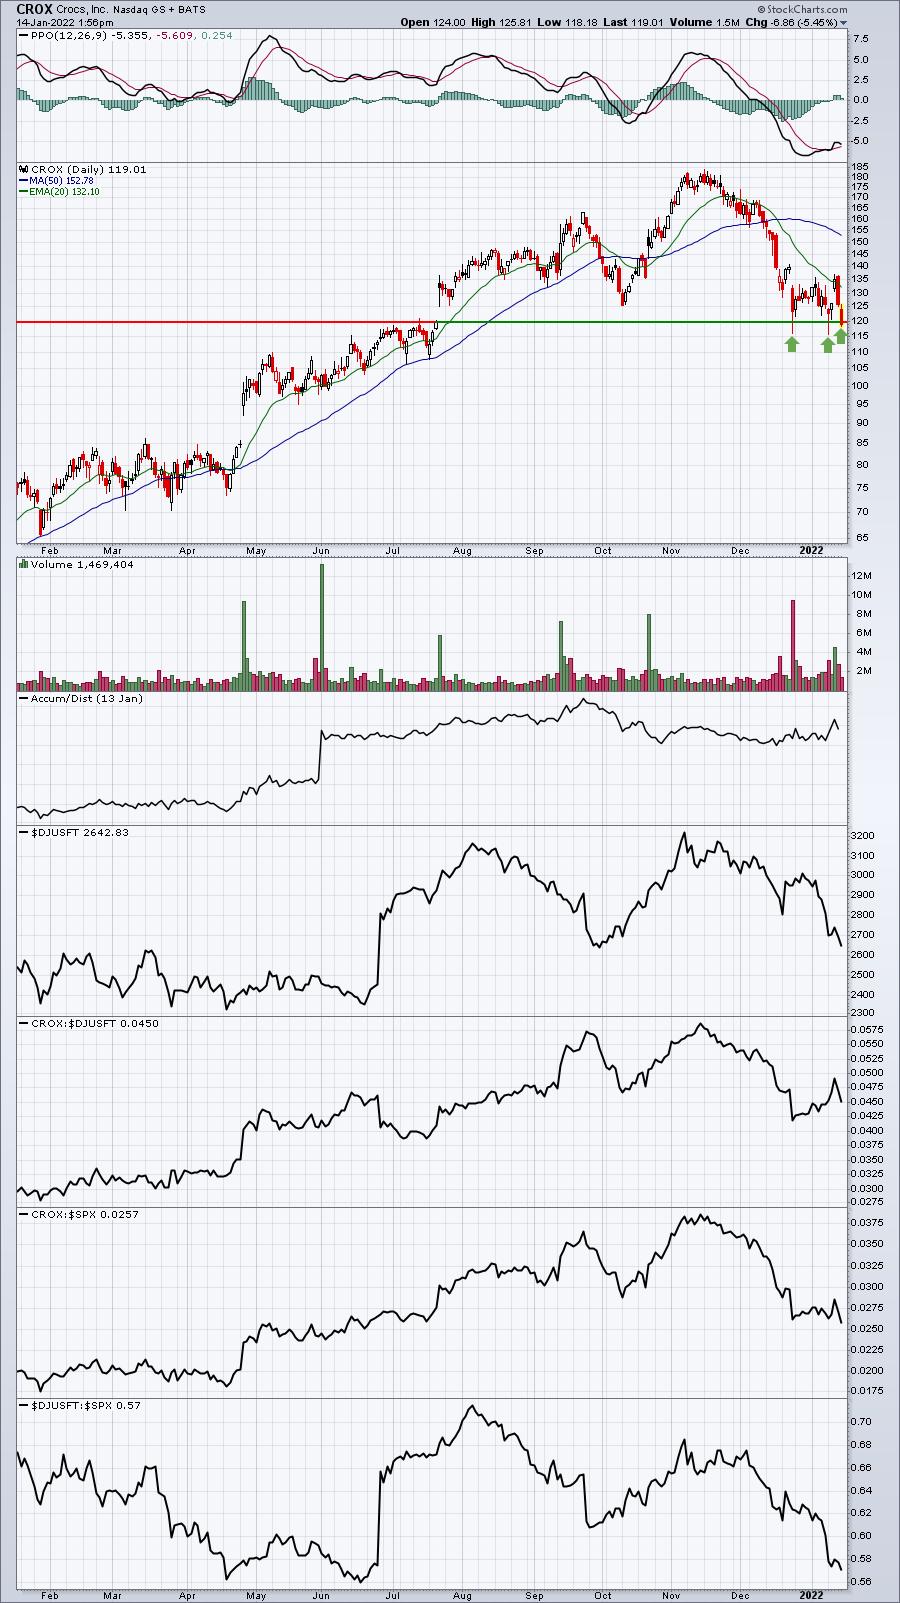
I would expect to see either a false breakdown, followed by a quick recovery - or a reversal from the current level. Stocks in these two groups that have a lot of in-the-money put interest might be enticing. Crocs, Inc. (CROX) will be a very interesting stock for next week. It's been battered over the past two months and is now trading at gap support:
ChartLists/Strategies
I've been pretty clear about being rather bearish near-term. But keep in mind one thing if you're shorting the growth stocks right now. Options expire next Friday and many growth names are heavily traded in the options world and are likely to be building EXTREME net in-the-money put value right now as they've been utterly trounced. I'd be using weakness to close out short positions today and/or Tuesday. Personally, I'll likely trade a few stocks on the long side next week given the options activity. Our January Max Pain webinar will be held on Tuesday at 4:30pm where we'll feature stocks that could move higher or lower based upon their January open interest. This one should be very interesting.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Friday, January 14:
JPM, WFC, C, BLK, FRC
Tuesday, January 18:
SCHW, GS, PNC, TFC, BK, IBKR, SBNY, JBHT, CNXC, PNFP, HWC, SI, UCBI, ONB, FULT, FMBI, FBK
Economic Reports
December retail sales: -1.9% (actual) vs. +0.0% (estimate)
December retail sales excluding autos: -2.3% (actual) vs. +0.3% (estimate)
December industrial production: -0.1% (actual) vs. +0.3% (estimate)
December capacity utilization: 76.5% (actual) vs. 77.0% (estimate)
January consumer sentiment: 68.8 (actual) vs. 70.4% (estimate)
November business inventories: +1.3% (actual) vs. +1.1% (estimate)
Happy trading!
Tom