
EB Daily Market Report - Tuesday, January 18, 2022
January Max Pain
Tonight we'll be hosting our January Max Pain event, which was pushed back to 7:30pm ET. We have expanded the number of stocks and ETFs that we'll cover tonight, including ALL 40 Portfolio stocks. It should be highly educational, so I hope you can make it!
ChartLists Updated
Most of our ChartLists have been updated over the past few days to a week, including the following:
- Strong Earnings ChartList (SECL)
- Strong Future Earnings ChartList (SFECL)
- Strong AD ChartList (SADCL)
- Raised Guidance ChartList (RGCL)
- Bullish Trifecta ChartList (BTCL)
- Short Squeeze ChartList (SSCL)
- Strong ETF ChartList (SETFCL) + ETF Analyzer Excel spreadsheet
- Upcoming Earnings ChartLists - houses earnings from every day this week
- Upcoming Earnings Relative Strength ChartList (*NEW*) - highlights every company (greater than $1 billion in market cap and also liquid) reporting earnings in the week ahead, but on a relative basis to its industry group. So it's a price relative chart. You can pull this ChartList up in "Summary" form and then go back for a one month period to highlight those solid relative strength performers heading into earnings.
All of our ChartLists can be found on our website
Executive Market Summary
- Futures were lower overnight and all of our major indices gapped lower
- The likely culprit (or one culprit) is higher treasury yields as the 10-year treasury yield ($TNX) is up 9 basis points to 1.86%
- Despite the huge jump in yields, financials (XLF, -2.08%) are challenging technology (XLK, -2.18%) as the worst performing sector today
- Banks ($DJUSBK, -2.49%) and investment services ($DJUSSB, -3.35%) are the biggest drags on the XLF
- Goldman Sachs (GS, -6.58%) is putting significant pressure on the Dow Jones, down over 500 points on the session
- Crude oil ($WTIC, +2.33%) is having another strong day, now approaching $86 per barrel; energy (XLE, +0.47%) is the only sector in positive territory
- Economic reports disappointed again today with a sharp drop in the empire state manufacturing index; this, combined with an awful retail sales report last week, makes the big surge in yields more bearish for stocks
Market Outlook
The TNX is a problem for now and it's certainly having an impact on large cap growth names ($DJUSGL). When rates break out and soar, growth stocks typically succumb to mounting pressure due to short-term lower valuations. Here's a chart that illustrates this:
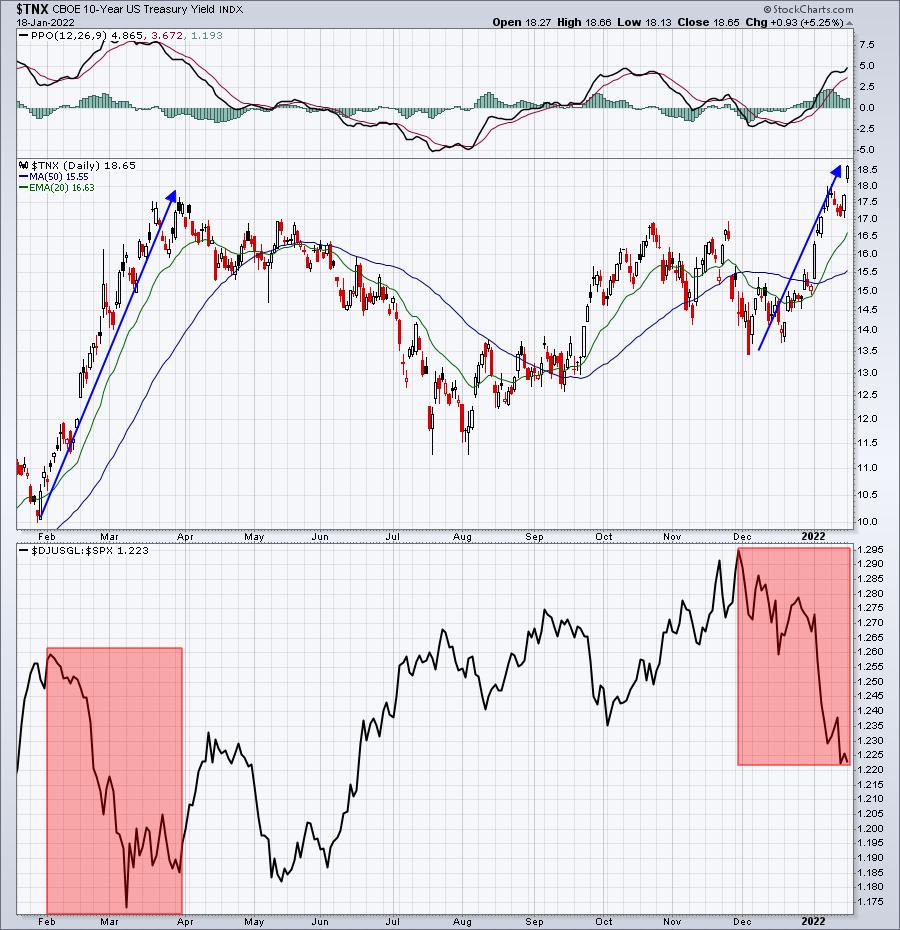
The growth area of the market will rally back in time as rates top and roll back over, but in the short-term, the only bullish indication is max pain. Many of the small and mid cap growth names may have significant net in-the-money put premium on the table. Some of those names could see a short-term push higher. Many of the large cap names, however, haven't suffered as much over the past couple months and instead have net in-the-money call premium. AAPL is one such company that I'll discuss tonight at our event.
Sector/Industry Focus
Integrated oil & gas ($DJUSOL, +1.34%) is having another strong day, continuing the breakout that occurred as we entered 2022:
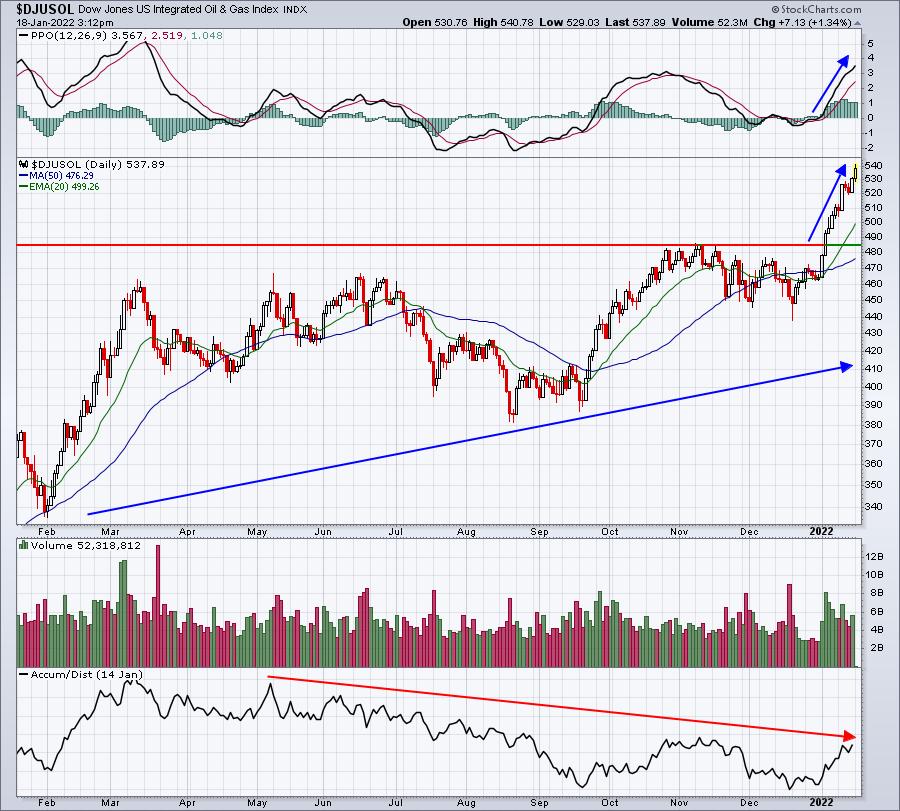
I see a short-term and a long-term bearish problem, although I'm fine with the energy space overall in the medium-term. The short-term issue deals with options expiration this Friday. This is the primary area of market strength as we approach Friday. A short-term selloff to reduce the net in-the-money call premium on many of these stocks wouldn't be a shocker to me. The long-term I have a problem with because (a) I feel the US dollar will be strong, and (b) I don't like the long-term decline in the AD line shown above. Energy is the unquestioned sector leader at this time, but I do not believe that relative strength will continue much beyond Q1 - just my opinion.
ChartLists/Strategies
It's Max Pain webinar day and we always provide potential trading candidates on both the long and short side as market makers are likely to have significant financial interest in the very near-term (through Friday and possibly into early next week). I've personally bought two max pain long candidates today - Peloton (PTON) and Teladoc (TDOC). These two companies currently have net in-the-money put premium of $276 million and $335 million, respectively. PTON, in particular, seems to bounce after its 5-day ROC moves below -10% and that's where we're at now:
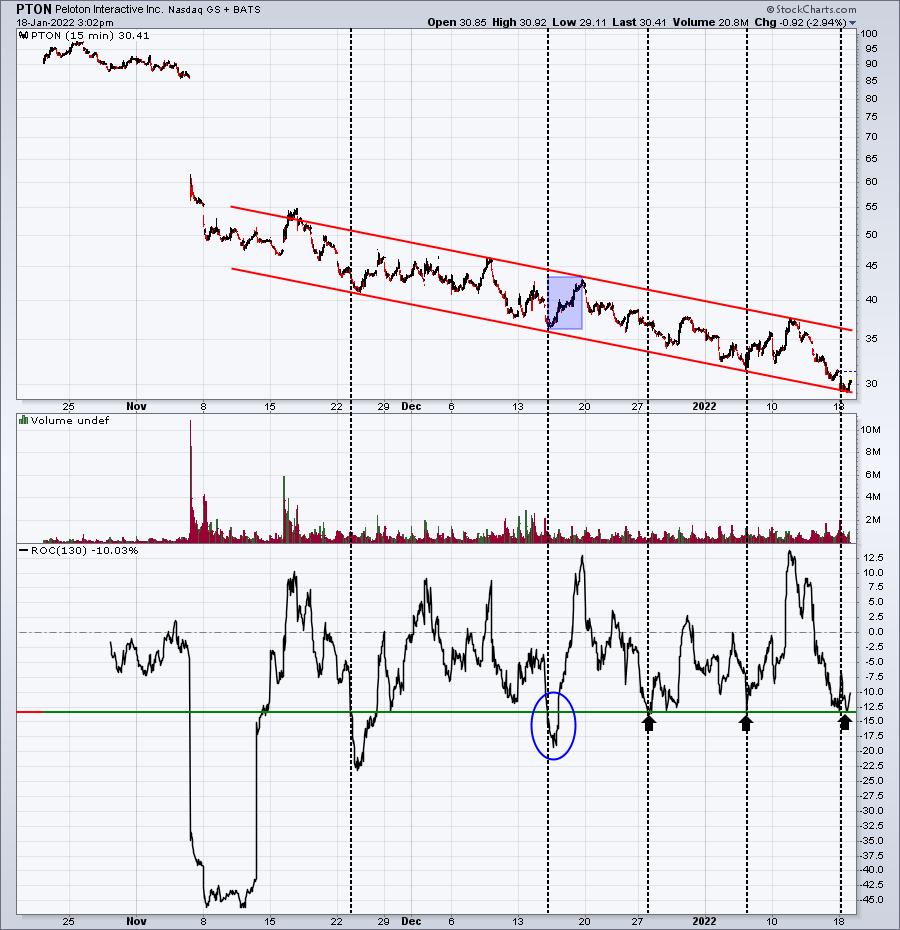
PTON has reached the lower end of its down channel, so that suggests a bounce could be in order. Also, the black-dotted vertical lines mark times when PTON has reached a rate of change (ROC) level of -12.5% over 5 days. This is a 15-minute chart and there are 26 such periods in a trading day. So a 130-period ROC is the equivalent of 5 days.
PTON is not a healthy stock, not even close. It's also a very aggressive trade. However, there's tremendous incentive for a short-term rebound, so we'll see what happens.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Tuesday, January 18:
SCHW, GS, PNC, TFC, BK, IBKR, SBNY, JBHT, CNXC, PNFP, HWC, SI, UCBI, ONB, FULT, FMBI, FBK
Wednesday, January 19:
UNH, BAC,PG,ASML, MS, PLD, USB, KMI, STT, DFS, FAST, CFG, UAL, CMA, AA, CBSH, PACW, WTFC
Economic Reports
January empire state manufacturing index: -0.7 (actual) vs. 26.0 (estimate)
January housing market index: 83 (actual) vs. 84 (estimate)
Happy trading!
Tom