
EB Daily Market Report - Thursday, February 3, 2022
Executive Market Summary
- Futures were significantly lower overnight after Meta Platforms (FB, -26.23%) imploded following a horrid outlook with forecasted revenues well below consensus estimates
- Cryptocurrencies are very weak as the market turns to a risk-off mentality; etherium ($ETHUSD) is down more than 4%
- Crude oil ($WTIC, +2.10%) has spiked to above $90 per barrel, but energy stocks (XLE, -1.11%) are not responding favorably today
- The only sector in positive territory today is a defensive group - consumer staples (XLP, +0.02%)
- One day after communication services (XLC, -6.55%) led the market higher with a strong report from Alphabet (GOOGL), it's lagging badly due to FB's implosion
- The 10-year treasury yield ($TNX) is up 6 basis points to 1.83%, but that's been unable to lift financials (XLF, -1.12%)
- Amazon.com (AMZN, -7.82%) is testing its 52-week low just as it gets set to report its quarterly results; AMZN has been a very poor relative performer, suggesting we could see more bad news after the bell
Market Outlook
It certainly appears as if the cyclical bear market counter trend rally has come to an end, thanks to a number of extremely poor earnings reports, namely Meta Platforms (FB) and Spotify (SPOT). Growth stocks never really did get much of a lift on a relative basis vs. value stocks, so I'm definitely not surprised by this sudden downturn. Check out the following chart, highlighting the S&P 500's reversal to the downside with growth vs. value relative charts included below the S&P 500 chart:
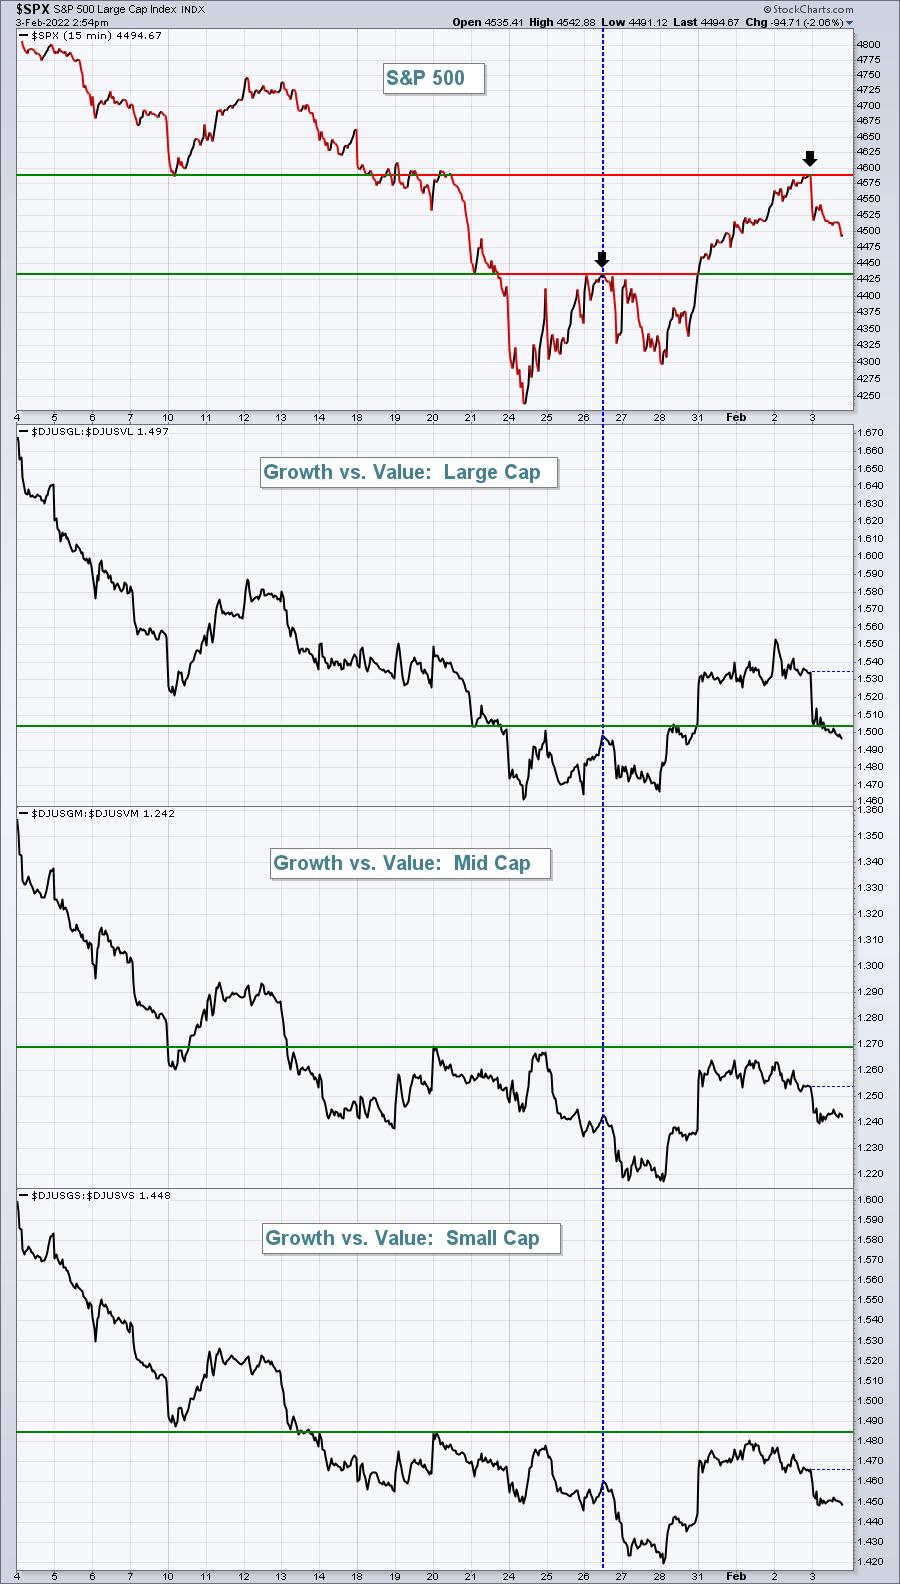
As we've seen for many months, the large cap growth names have performed much better recently, given the excellent earnings reports from Apple (AAPL) and Microsoft (MSFT), the two most-heavily-weighted S&P 500 stocks. But those bottom two panels show us that there's been little change in mid cap and small cap growth stocks. They remain in relative downtrends. This is an indication that Wall Street remains very much concerned about higher inflation and higher interest rates.
Sector/Industry Focus
Semiconductors ($DJUSSC) staged a nice rebound this week, but staggered once they tested the 20-day EMA and prior gap support:
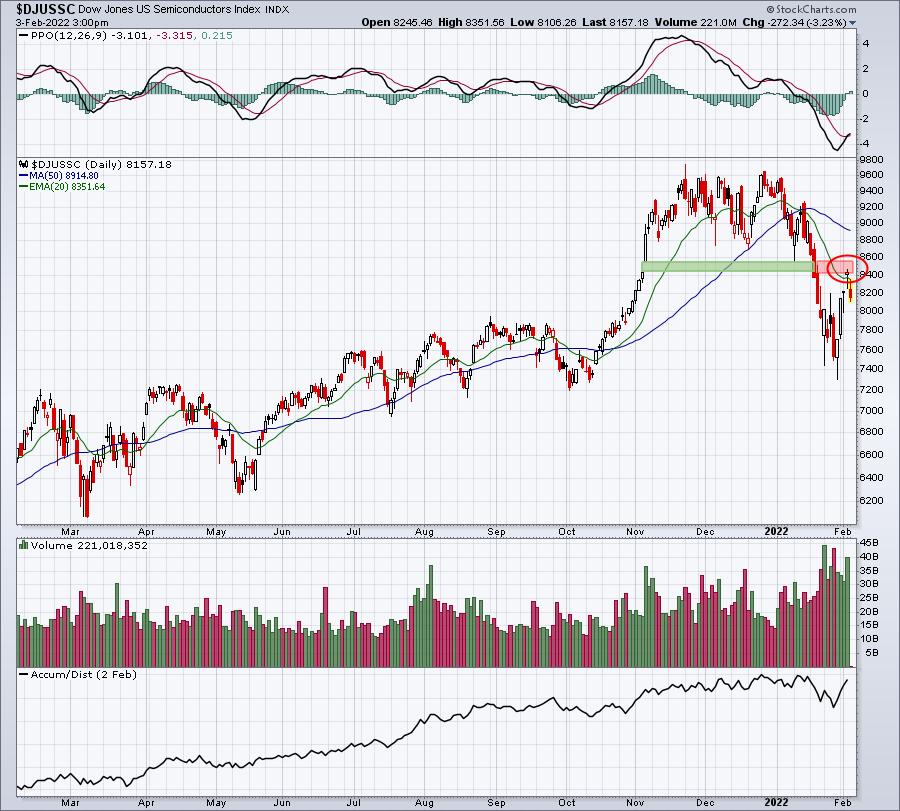
The one positive is the AD line moving back up close to its 52-week high, despite price action remaining significantly below its 52-week high. That's a sign that Wall Street could be accumulating this group during this weakness. However, while I still favor this group over the long haul, I believe prices of most stocks will head lower over the next 3-6 months, before we'll bottom and begin a rally into the 3rd or 4th quarters of this year.
ChartLists/Strategies
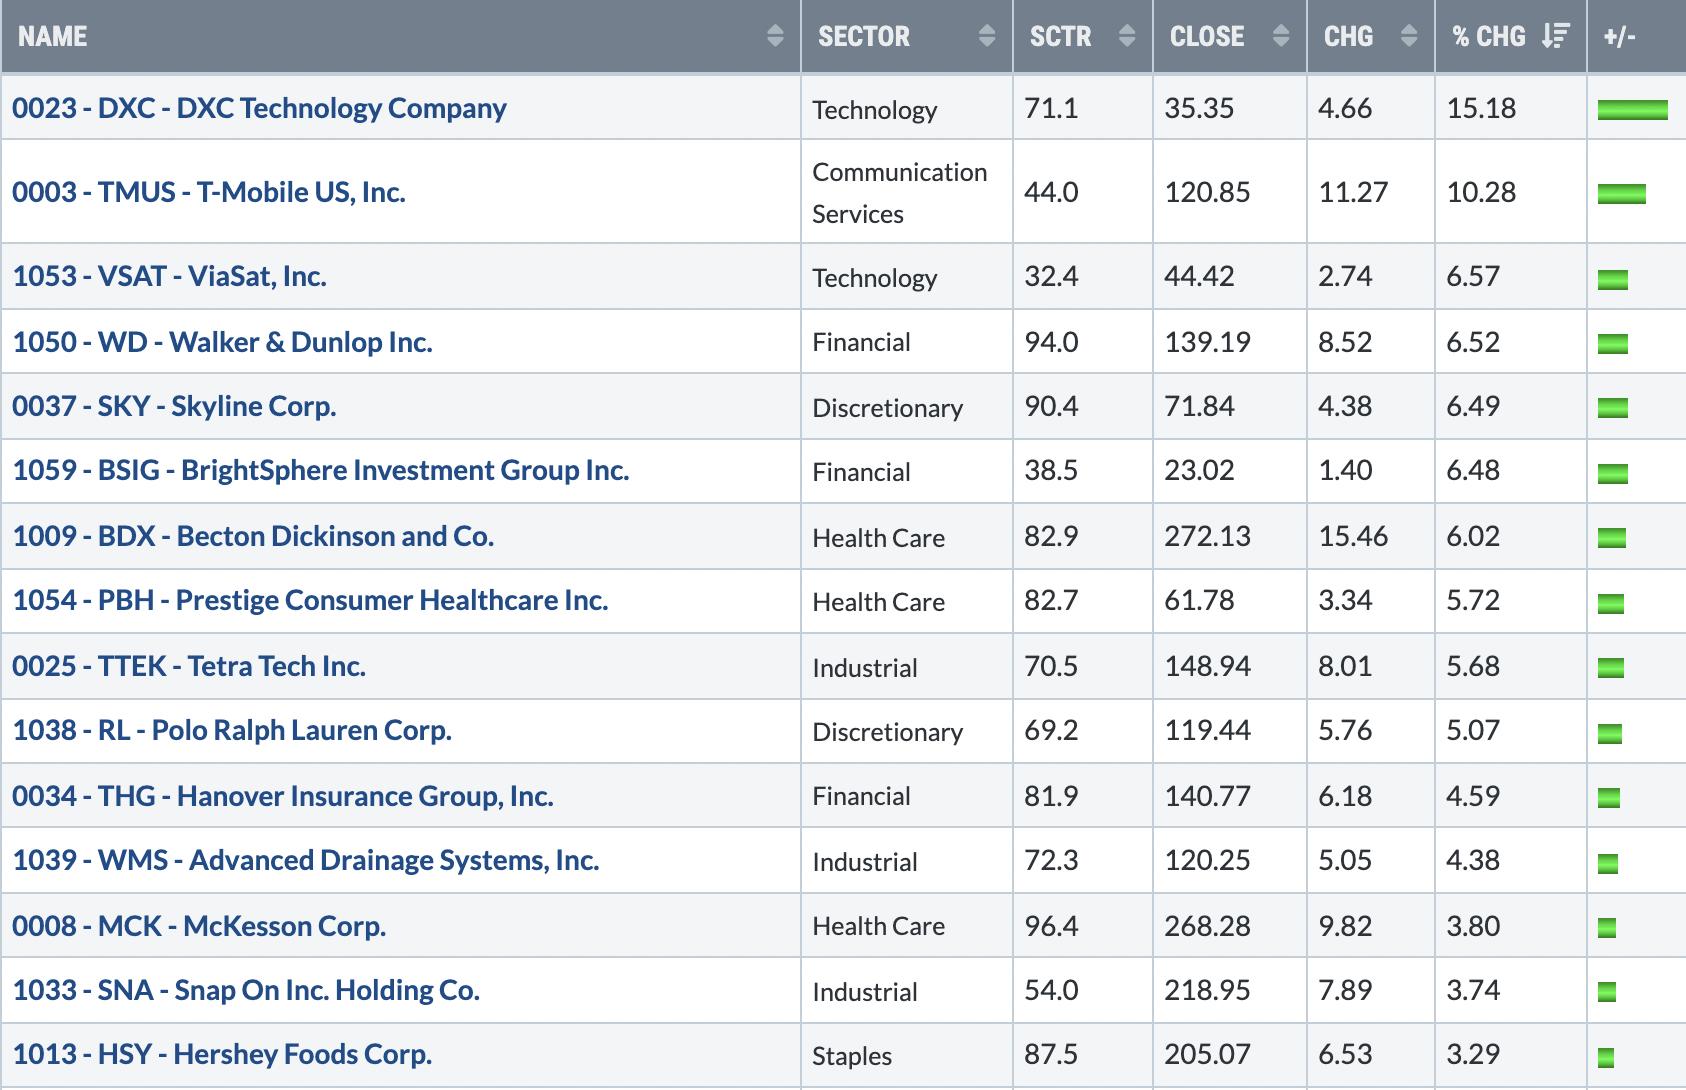
I always look at our Upcoming Earnings ChartLists after the market opens. It's a quick, organized way of seeing the stock market's reaction to a large number of companies reporting quarterly results. Below, I've taken two snapshots, the first of which is the Top 15 reactions today, while the second highlights the Bottom 15 reactions:
Top 15 Earnings Reactions:
Bottom 15 Earnings Reactions:
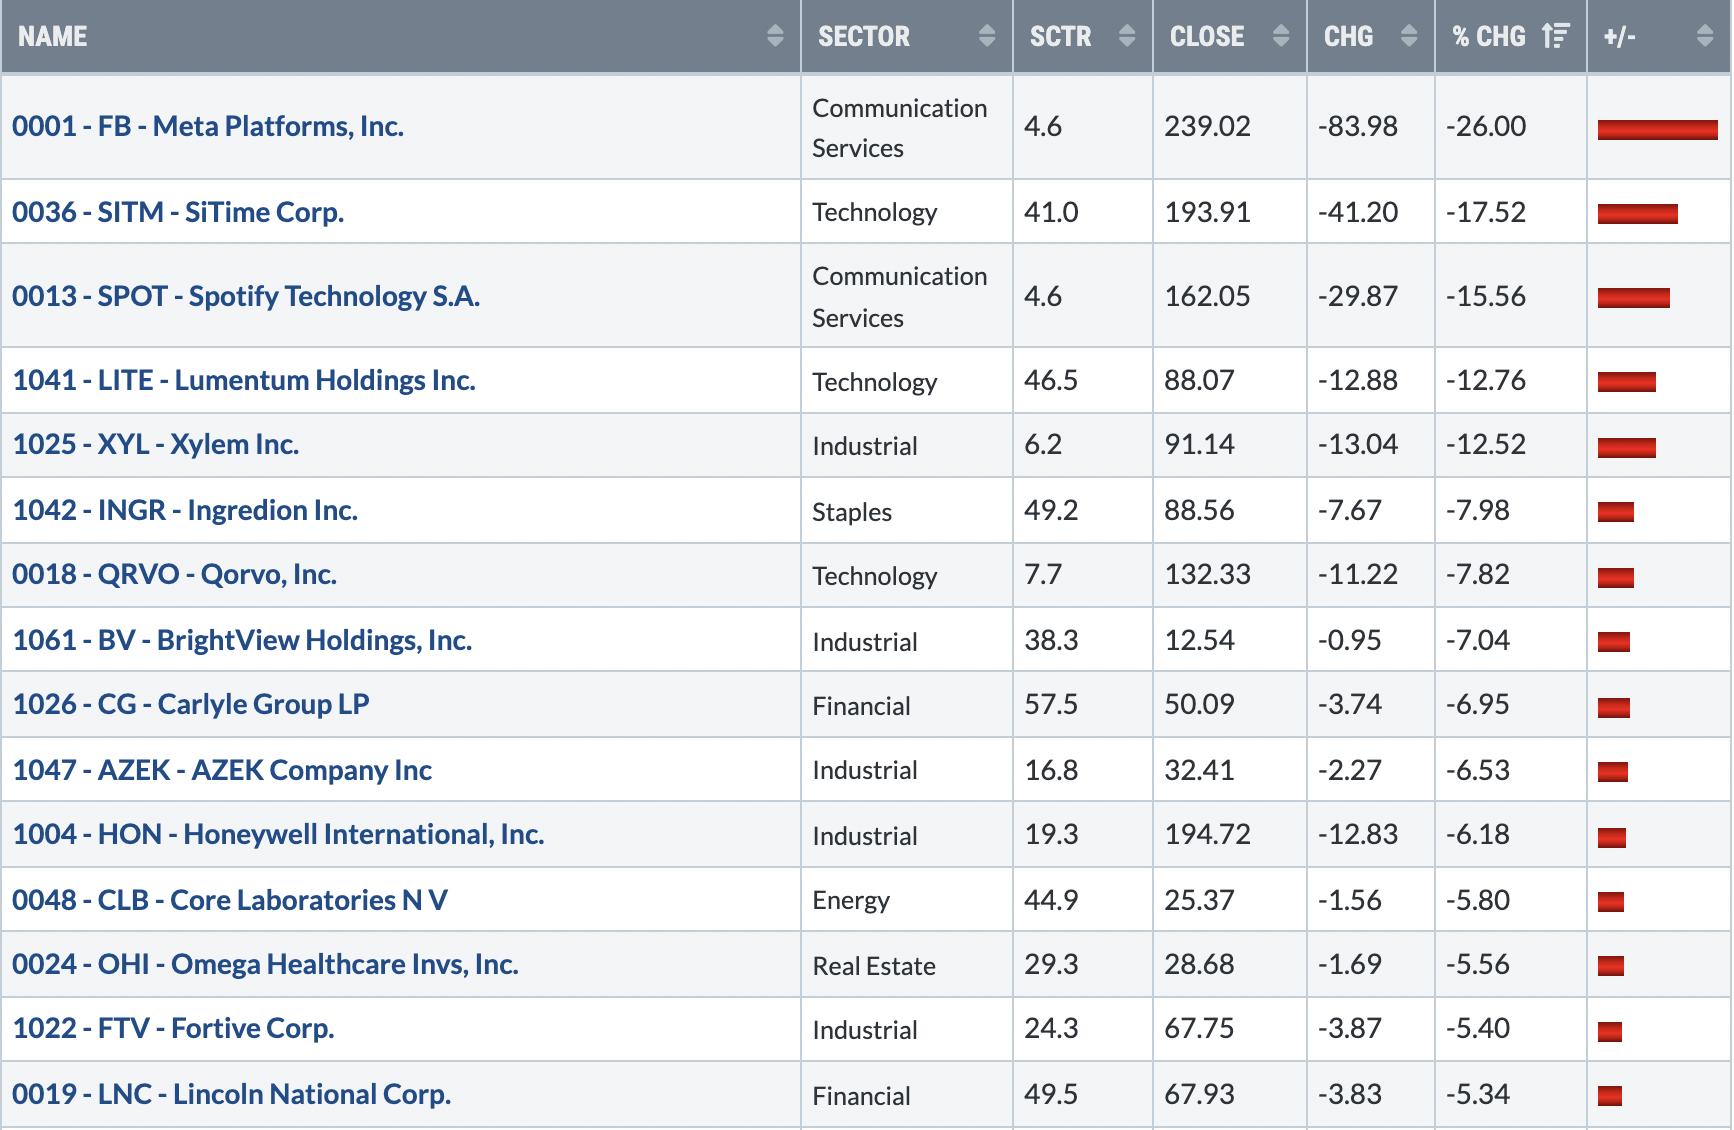
I rarely hold stocks into earnings reports because of the extreme risk. However, if I were to hold stocks into earnings, I'd want to own only those companies that are performing strongly vs. their industry peers. Of the 30 stocks listed above, one that catches my eye is BDX, one of the big earnings-related gainers:
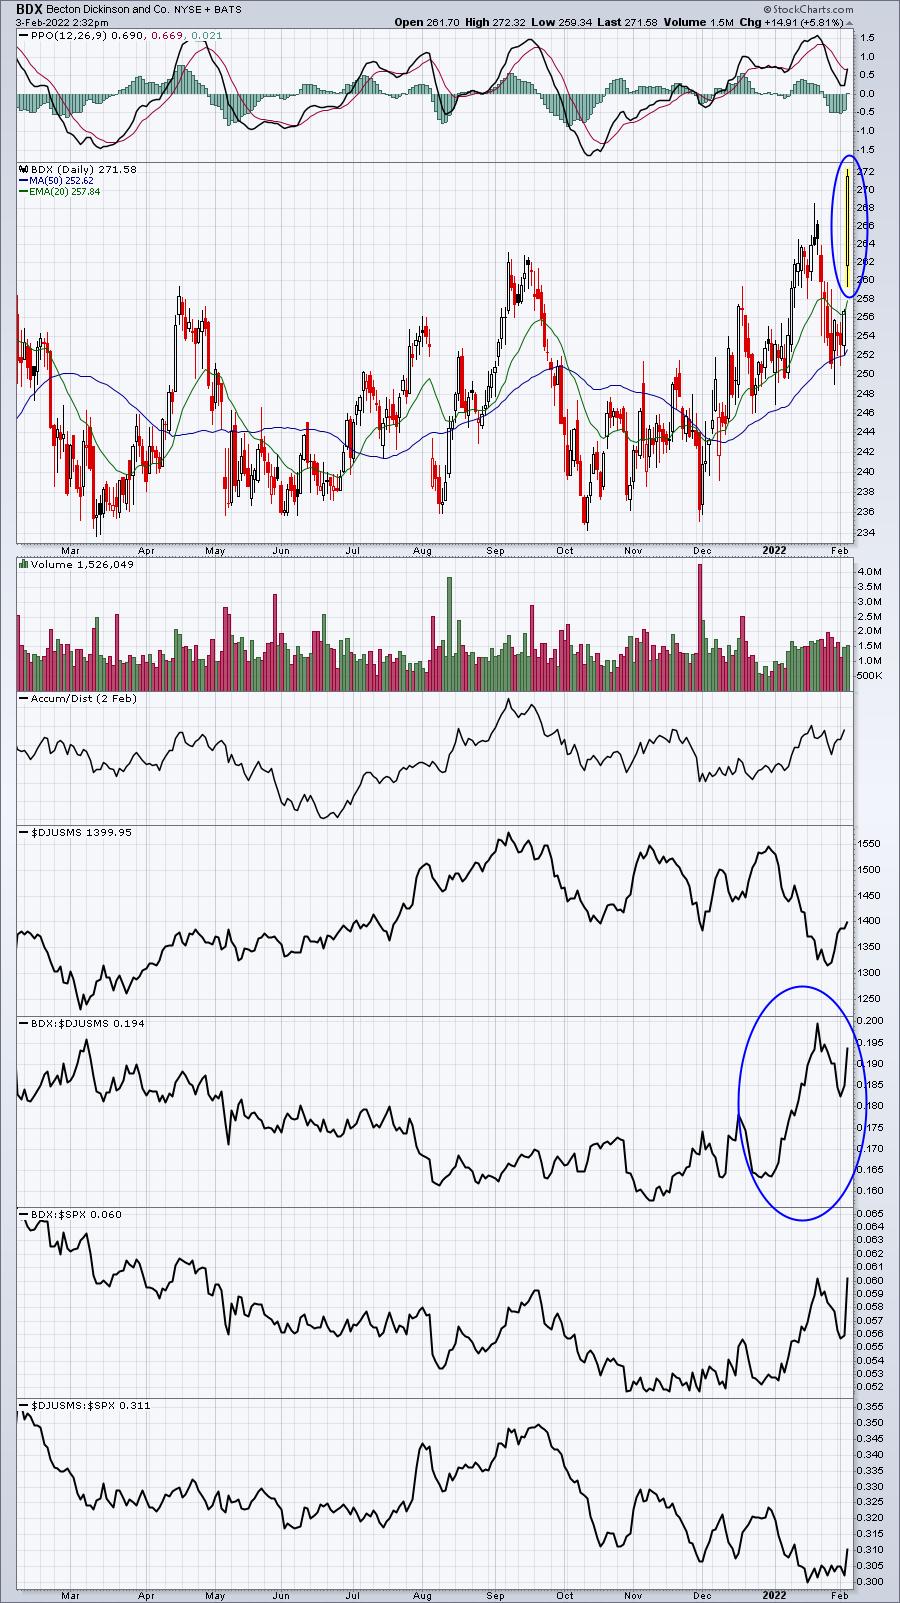
Note the extreme relative strength vs. its medical supplier peers ($DJUSMS) over the couple months prior to its earnings report. Wall Street's been getting wind of a strong quarter and outlook and today we're seeing it in terms of a breakout.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, February 3:
AMZN, LLY, MRK, HON, COP, EL, F, CI, ITW, BDX, ICE, ABB, ATVI, SNAP, FTNT, BCE, MCHP, PRU, HSY, PH, APTV, NOK, BIIB, AME, CMI, U, WEC, GWW, FTV, HIG, SWKS, AVTR, CLX, BILL, PINS, XYL, CMS, CG, TW, DGX, CPT, CHKP, NLOK, CAH, LPLA, MPW, ABMD, OTEX, WRK, NWSA, PCTY, SNA, HUBB, BERY, COLM, DLB, DECK, ARW, SYNA, RL, WMS, RGA, PENN, LITE, BYD, SKX, NOV, INGR, JHG, HBI, MIME, POWI, VIAV, BECN, HAIN, WERN, PBH, VSTO, MWA, SKYW, MTOR, ENVA, GPRO
Friday, February 4:
BMY, SNY, REGN, ETN, APD, AON, RCL, CBOE, ADNT, SPB, TWST, VRTS, ROAD
Economic Reports
Initial jobless claims: 238,000 (actual) vs. 250,000 (estimate)
Q4 productivity: 6.6% (actual) vs. 2.7% (estimate)
January PMI composite: 51.1 (actual) vs. 50.8 (estimate)
December factory orders: -0.4% (actual) vs. -0.2% (estimate)
January ISM services: 59.9 (actual) vs. 60.0 (estimate)
Happy trading!
Tom