
EB Daily Market Report - Wednesday, February 16, 2022
Sneak Preview: Top 10 Stocks Event Today
This is our quarterly webinar to look at our results from the prior quarter, and to consider themes for the quarter ahead. I'll be discussing not only our performance from this past quarter, but also looking at our results since inception. It's actually quite interesting, so I'm looking forward to sharing that with you today. Below is the room link for today's event, which begins at 4:30pm ET:
https://earningsbeats.zoom.us/j/86882675636
The room will open at 4:00pm ET. If you can't make it today, no problem. We record all of our events and will make sure you get a copy to review at your leisure.
Executive Market Summary
- Futures were weak overnight and our major indices drifted lower throughout most of today's session
- We're currently getting a lift after the FOMC minutes were released at 2:00pm ET
- Economic reports this morning added to inflationary concerns and the 10-year treasury yield ($TNX) reached a new high; it's since pulled back after the 2pm ET release of Fed minutes
- Options expiration this Friday favors the bulls as there remains billions of net in-the-money put premium - will it matter? We'll soon find out
- Gold ($GOLD, +0.94%) is climbing again and currently at $1874 per ounce; we haven't seen a close above $1870 since June
- Energy (XLE, +2.01%) is benefiting from a rise in crude oil prices ($WTIC, +1.75%)
- Communication services (XLC, -1.04%) is once again the laggard
- The Volatility Index ($VIX) is down 3.7%, but is still near 25, so we must be prepared for whipsaw action in both directions
Market Outlook
Despite TONS of net in-the-money put premium on the table and expiring Friday, large cap growth names have been unable to make any meaningful headway vs. its large cap value counterparts. Maybe that changes over the course of the next few days, but the growth area had begun to trek higher on a relative basis. Until today. Last month, the IWF:IWD (growth vs. value) could not rally despite max pain bias to the upside. So far, that's the case again today. If this ratio breaks down again, I believe the S&P 500 (and all of our major indices) will be in for another swoon:
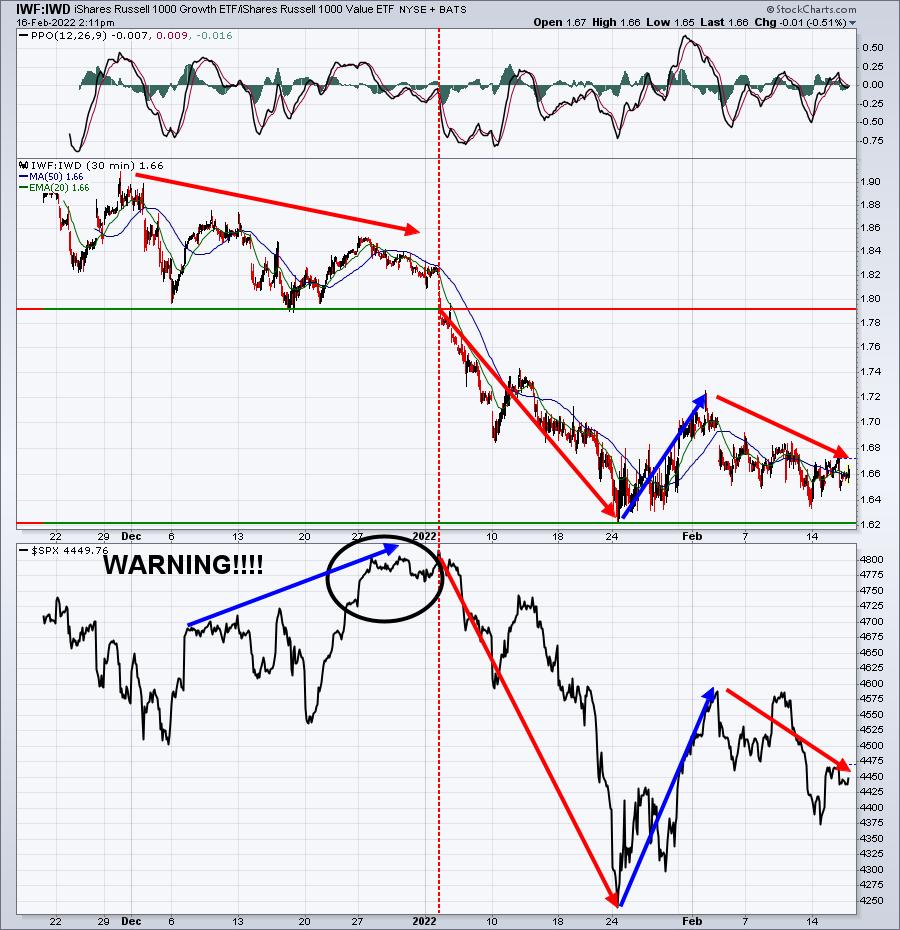
The Fed minutes were just released a few minutes ago. Could we see a relief rally this afternoon? Hey, anything is possible. But if the above IWF:IWD ratio breaks down, or when it breaks down, you will take considerable risk with any long positions - all in my opinion, of course.
Sector/Industry Focus
We saw an excellent retail sales report for January, blowing away estimates. But you'd never know it by the reaction in the widely-diversified retail ETF (XRT):
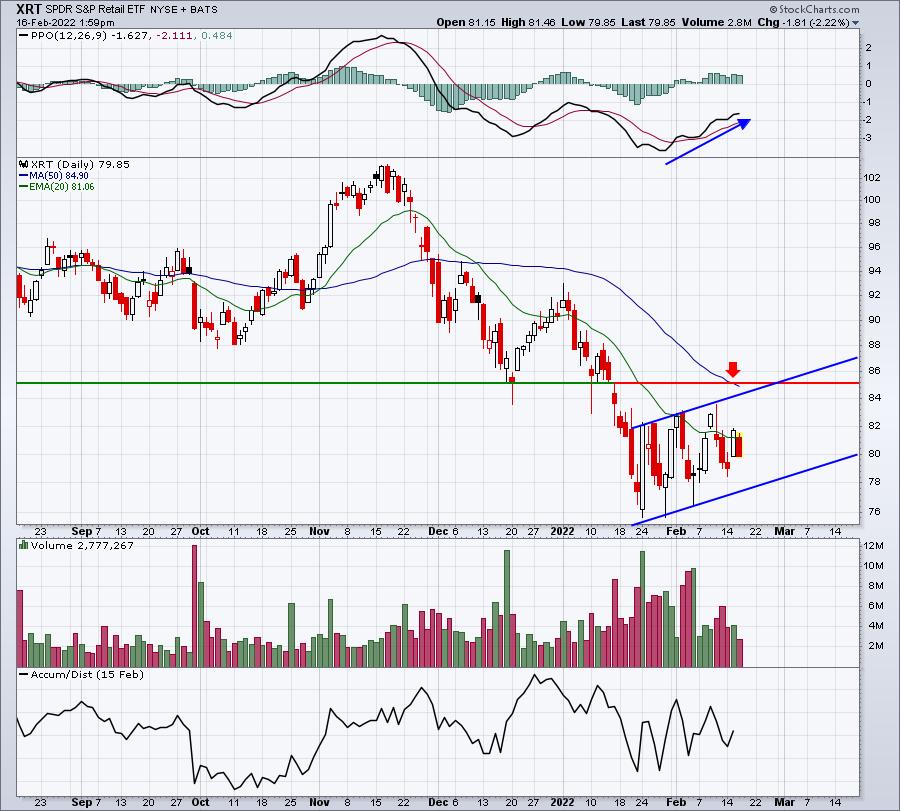
This is the same chart I highlighted yesterday. But note with that excellent January report, the XRT fell back below its 20-day EMA. Keep a close eye on the channel above. If that breaks to the downside, we're likely facing another drop ahead.
ChartLists/Strategies
I exited all my max pain trades earlier today with net losses. A couple violated stops, but in general, I simply wasn't impressed with the lack of follow through today in the overall market and I'm worried about downside potential - whether it's today or next week. This morning's industrial production report showed a HUGE increase, which is clearly inflationary. Throw in yesterday's monthly PPI report, which doubled expectations, and the inflation narrative remains firmly in play. The 10-year treasury yield ($TNX) was down earlier this morning, but has now moved to a fresh new high. High inflation and higher interest rates both add to problems among growth stocks and we're seeing that again today. I'm holding the GLD, but otherwise, I've moved to cash for now. If we do see a rally into the end of the week, I will likely use it as an opportunity to short the major indices with inverse ETFs.
At least that's my plan for now.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Wednesday, February 16:
NVDA, CSCO, AMAT, SHOP, ADI, EQIX, PXD, AIG, SNPS, KHC, NTR, HLT, GOLD, TTD, ET, DASH, WCN, ES, CPRT, AWK, ALB, APP, VMC, GRMN, GMAB, TYL, GNRC, MRO, CRL, WAB, TS, HST, CONE, H, TXG, OC, CHH, DNB, PEGA, BFAM, SITE, INFA, DAVA, KGC, RGLD, STAG, CROX, AM, WING, VMI, SUN, ALSN, TRIP, R, FSR, FSLY, SPWR, CAKE, INFN, KAR, VECO, PLMR
Thursday, February 17:
WMT, SO, BAX, DLR, KEYS, ED, WST, PLTR, EPAM, AEE, ROKU, VTR, GPC, POOL, OWL, NICE, LKQ, LBTYA, LNT, CGNX, RGEN, GLOB, RS, DBX, SEE, SYNH, USFD, ATR, RCM, AN, RBA, YETI, SWAV, AMN, AL, RUN, IRDM, POR, AUY, APPN, QDEL, LTHM, MATX, TSEM, SHAK, RDFN, FVRR, VC, TPH, TDS, AAWW, SWI, LGND, HIMX, SKT
Economic Reports
January retail sales: +3.8% (actual) vs. +2.0% (estimate)
January retail sales less autos: +3.3% (actual) vs. +1.0% (estimate)
January industrial production: +1.4% (actual) vs. +0.4% (estimate)
January capacity utilization: 77.6 (actual) vs. 76.7 (estimate)
December business inventories: +2.1% (actual) vs. +1.8% (estimate)
February housing market index: 82 (actual) vs. 83 (estimate)
FOMC minutes to be released at 2:00pm ET
Happy trading!
Tom