
EB Daily Market Report - Tuesday, March 15, 2022
Max Pain Event Delayed to 7:30pm ET Tonight
It's the Tuesday before the 3rd Friday of the calendar month, so that means its March Max Pain time! Due to a conflict, however, I am not available at 4:30pm ET today, so we had to move the session to 7:30pm ET. If you can't make it live, no worries. We'll record it as always and you can check out the recording at your leisure.
Sorry for the inconvenience and thanks for your understanding!
Executive Market Summary
- Futures were strong overnight and U.S. equities opened higher
- Most of my sustainability ratios are higher today, but have weakened since their earlier intraday highs; I'd like to see them strengthen into today's close (XLY:XLP is the primary ratio to watch)
- The 10-year treasury yield ($TNX) is down 1 basis point to 2.13% ahead of tomorrow's FOMC policy decision
- The Federal Reserve began its 2-day meeting this morning to deliberate
- Energy (XLE, -2.74%) names are getting hit today as crude oil ($WTIC, -4.70%) falls further and now trades beneath $100 per barrel
- Gold ($GOLD, -1.53%) is also weak on the session, along with most other commodities
- Consumer discretionary (XLY, +2.67%) and technology (XLK, +2.61%) are today's clear leaders
Market Outlook
We have an intermediate-term downtrend (cyclical bear market) that we must respect. I'm seeing more and more signs of a recession that takes the stock market another leg lower. BUT, we also have options expiring this Friday and I just finished calculating Max Pain for both the SPY and QQQ. Here's the table showing the NET in-the-money PUT premium:
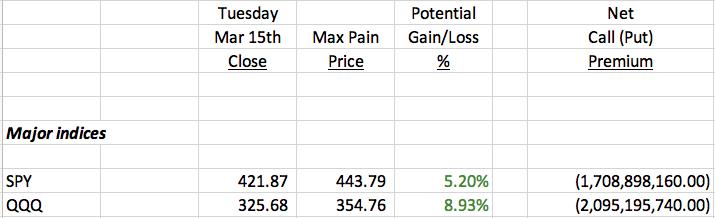
I don't know if I've EVER seen this much net in-the-money put premium. That's nearly $4 billion of net put value on just the SPY and QQQ options. So we can imagine how much TOTAL net in-the-money put premium there must be across the entire market right now. This information makes being aggressively short a difficult proposition short-term. It doesn't mean that we cannot move lower. Market makers can protect themselves from lower prices and having to pay out on put contracts by simply being short the respective ETFs or stocks.
We do have to realize, however, the financial incentive for stocks to move higher at some point this week. It could be today, tomorrow, or perhaps later in the week into early next week. But to think we'll go down without any bounce is probably not the best way to approach the stock market right now.
Let me be clear. To avoid being whipsawed, the absolute safest position is on the sidelines. If you don't want the risk of being whipsawed, then simply stay out. While I'm convinced that we're going to move lower, I'm not as convinced it's going to happen this week - not after doing my max pain research. Last month, max pain didn't provide us particularly good signals, so please remember that it doesn't always work. Just like RSI 30 doesn't mean we'll bounce. But if you're short, just understand that the risks are much higher given the current options environment heading into expiration this Friday.
Don't think there aren't risks being long, however. I am still convinced that when the next bout of selling hits, it's going to be impulsive. Like there are no buyers whatsoever and we could see 5-10% taken off of our major indices quickly.
So ask yourself whether you want the risk of trading AT ALL.
Sector/Industry Focus
I haven't discussed global markets much, so I thought I'd focus on Hong Kong, where the Hang Seng Index ($HSI) has been absolutely cratering. Its one-month decline right now is worse than its pandemic-related decline back in March 2020. In fact, the current one-month drop is the worst its seen during the past decade:
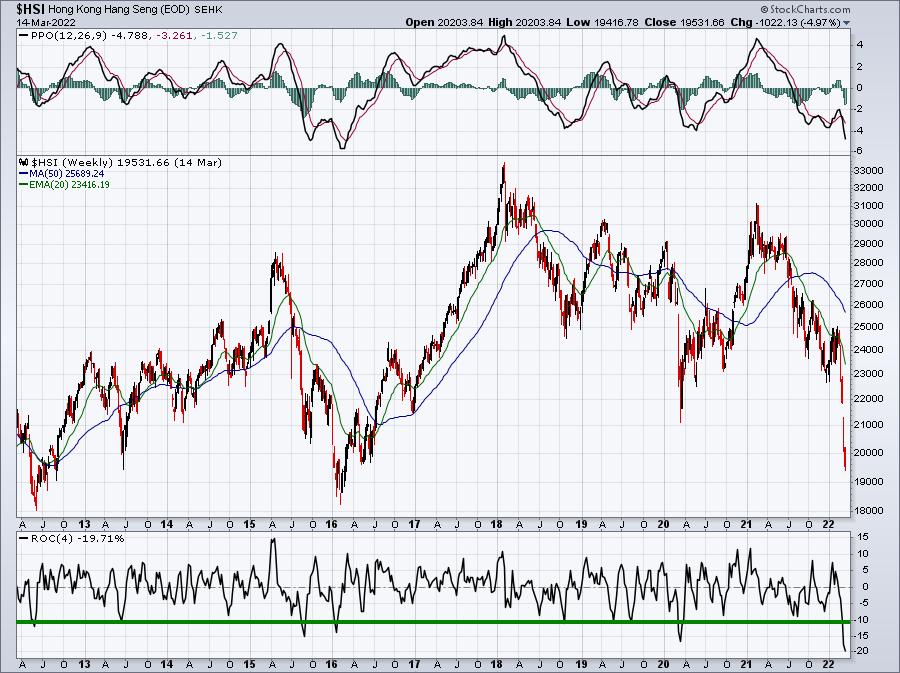
The 4-week rate of change (ROC) is close to -20%, which is considered bear market territory. Of course, the HSI is down a lot more than 20% from its high, but the steepness of this current drop is startling. It certainly seems as though a recession is being priced in across the globe as well.
ChartLists/Strategies
Crude oil ($WTIC) continues falling and, in my opinion, it's yet another sign of an impending recession. I exited both WTI and GLD this morning with losses. Perhaps they bounce, but I had my lines in the sand and both crossed them.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Tuesday, March 15:
S, SMAR, IHS
Wednesday, March 16:
LEN, EDR, ZTO, WSM, JBL, SMTC, PD, GES
Economic Reports
February PPI: +0.8% (actual) vs. +1.0% (estimate)
February Core PPI: +0.7% (actual) vs. +0.6% (estimate)
March empire state manufacturing index: -11.8 (actual) vs. +8.0 (estimate)
FOMC meeting begins
Happy trading!
Tom