
EB Daily Market Report - Tuesday, April 12, 2022
Today's Event - April Max Pain
At 4:30pm ET today, we'll attempt an encore of our March Max Pain, which was stunningly accurate. I'll dive into "April Max Pain", providing the max pain levels for the S&P 500 and NASDAQ, in addition to a few ETFs and several stocks. I hope you can join me.
If you'd like to join the webinar, you can click on the link below AFTER 4:00pm ET:
https://earningsbeats.zoom.us/j/81004655200
If you're unable to make the event live, but would like to view it later, we'll have the recording available for you.
Executive Market Summary
- Futures were higher as we awaited the latest inflation numbers
- March CPI rose a bit more than expected at the headline level, but Core CPI rose just 0.3%, below the +0.5% expectation
- Our major indices gapped higher and traded bullishly for nearly 30 minutes, then everything turned south
- The 10-year treasury yield ($TNX) fell 10 basis points during the first half of today's session, but it's recovered roughly half that this afternoon, currently at 2.73%
- Commodities are mostly higher, especially crude oil ($WTIC, +6.55%), which has surged more than $6 back above $100 per barrel
- The Volatility Index ($VIX, +1.72%) is up more than 10% from its intraday low this morning
- Carmax, Inc. (KMX, -8,44%) is today's worst-performing S&P 500 company after reporting quarterly earnings that fell short of expectations
- Energy (XLE, +1.52%) is the clear leader today, benefiting from the surge in crude prices
- Financials (XLF, -1.41%) is the weakest sector as banks ($DJUSBK, -1.73%) take another hit prior to the start of earnings season tomorrow; JP Morgan (JPM, -1.32%) is set to kick things off in the morning
- Finally, we'll get the latest inflation at the producer level tomorrow morning at 8:30am ET as the April report is released
Market Outlook
If you know one thing about me, it's that I never take anything at face value. I always like to look underneath the hood of the market to see what the real strengths and weaknesses are. Let me tell you something about today. It stinks. The intraday behavior reeks of more weakness to come.
This morning, we saw the latest inflation news at the consumer level. There was good news in that the March Core CPI was just +0.3%, below the +0.5% expected. On the surface, that appeared to be good news and our major indices exploded higher in pre-market. They settled down a bit heading into the open, then surged higher in the first 30 minutes of today's regular session. The S&P 500 moved just high enough to take me out of my SDS position. I made money, but obviously it was nothing to celebrate given the balance of the day's action.
Speaking of that balance of day action, would you like to see how each of our 11 sector ETFs performed from the opening bell to roughly 15-20 minutes ago? Check out this table:
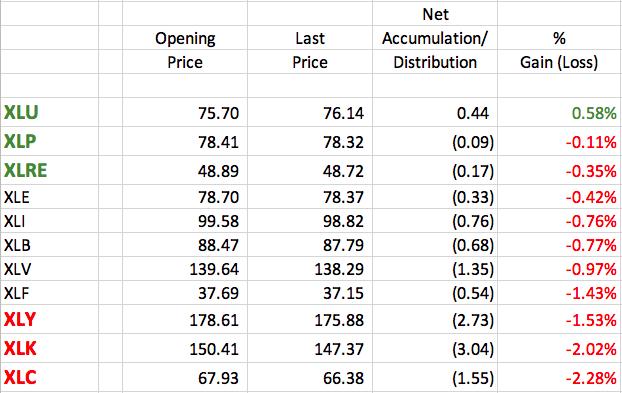
That early morning strength created an opportunity for Wall Street to increase its selling in the most aggressive sectors. And notice what's held up best since the opening bell? The defensive sectors. The action is telling me that Wall Street is growing much more concerned about a recession than it is concerned about inflation.
The rotation into defense continues and that is setting us up for a further drop ahead. If you happen to have traded the SDS (or QID), I'd remain in both until their respective indices (S&P 500 and NASDAQ 100, respectively) are able to clear the declining 20-day EMAs.
Sector/Industry Focus
The Dow Jones U.S. Apparel Retailers Index ($DJUSRA) looked to be breaking out above recent price resistance this morning, but like so many other areas, it's been a little disappointing in the afternoon. The downtrend line has been broken, but we've yet to see this group confirm a breakout above price resistance. Here's how it currently looks:
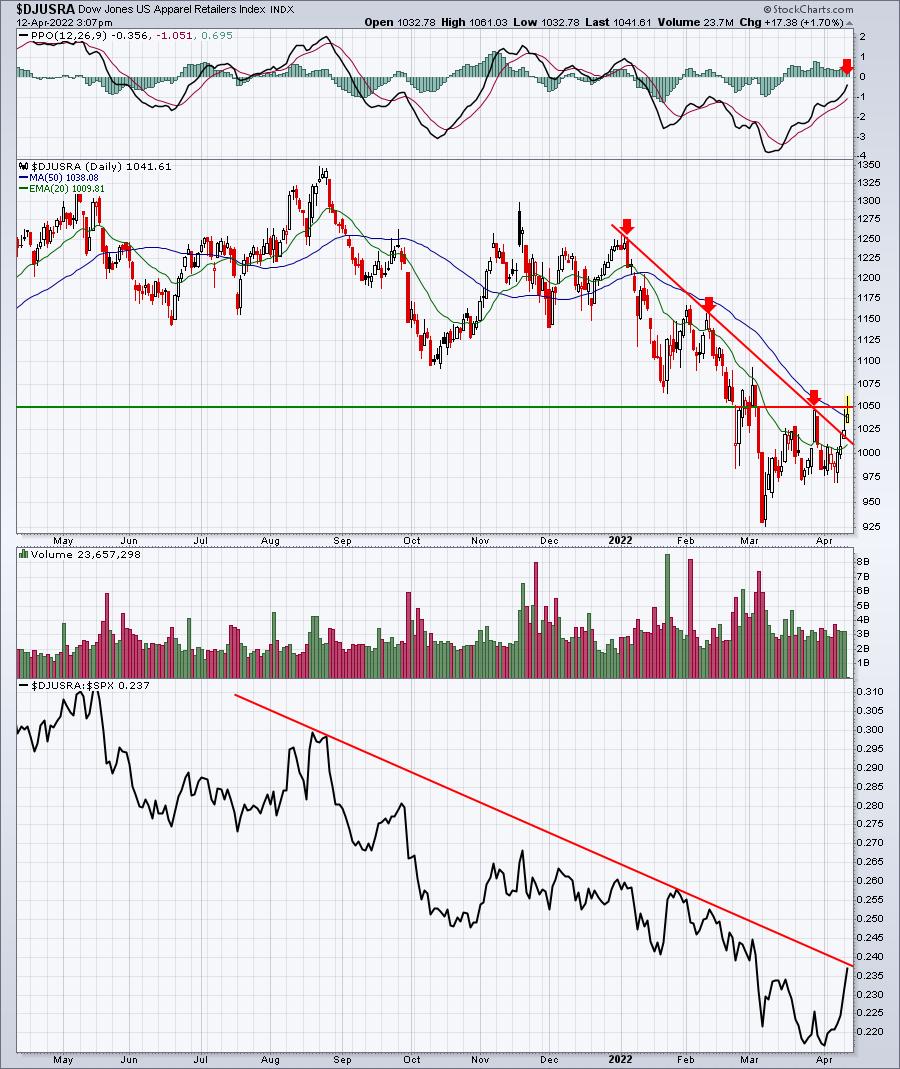
While the absolute price action has cleared its short-term downtrend line, the relative strength downtrend in the bottom panel has yet to be cleared.
ChartLists/Strategies
I'll be discussing potential max pain trades in an hour or so at your event this afternoon.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Tuesday, April 12:
ACI, KMX
Wednesday, April 13:
JPM, BLK, INFY, FAST, FRC, DAL, SJR, SGHC, BBBY
Economic Reports
March CPI: +1.2% (actual) vs. +1.1% (estimate)
March Core CPI: +0.3% (actual) vs. +0.5% (estimate)
Happy trading!
Tom