
EB Daily Market Report - Thursday, April 14, 2022
Reminder
Tomorrow is Good Friday and both the bond and stock market will be closed. Enjoy your three-day weekend!
Executive Market Summary
- Futures were relatively flat this morning, with a slight advantage to the Dow Jones
- That relative strength in Dow Jones stocks has continued throughout the session
- Crude oil ($WTIC, +2.37%) and natural gas ($NATGAS, +4.02%) are both higher, though commodities are mixed today
- The 10-year treasury yield ($TNX) has surged another 14 basis points to 2.83%
- Higher rates are likely triggering further selling in growth stocks (IWF, -1.49%) as value stocks (IWD, -0.23%) are performing much better on a relative basis
- The sector leaderboard looks familiar - energy (XLE, +0.75%), utilities (XLU, +0.47%), and consumer staples (XLP, +0.29%)
- Meanwhile, technology (XLK, -1.90%) is the primary laggard, though both communication services (XLC, -1.48%) and consumer discretionary (XLY, -1.17%) are weak as well
- Unitedhealth Group (UNH, +0.02%) is flat despite reporting excellent quarterly results and threatening a breakout earlier in the session
Market Outlook
It's hard to think too many bullish thoughts on U.S. stocks right now. The following 60-minute chart shows both the SPY and QQQ inside down channels:
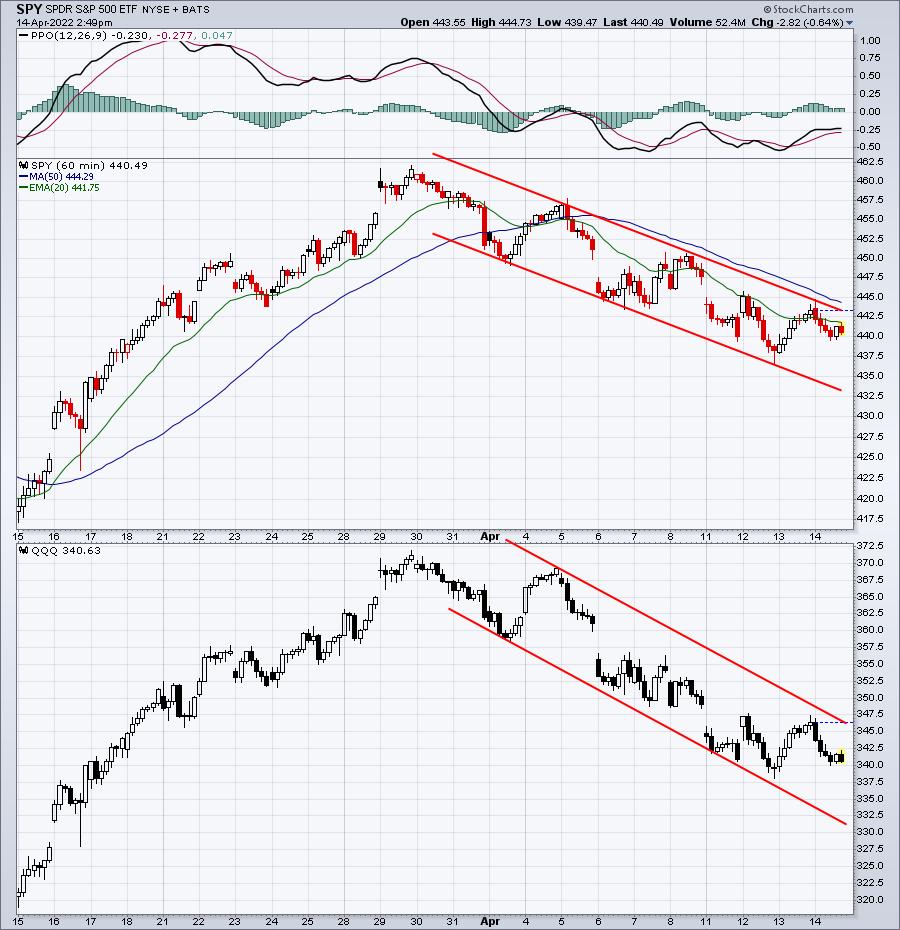
"The trend is your friend." There's no doubt that the trend right now is lower. If the lows from earlier in the week do not hold as support, expect the selling to accelerate and for the Volatility Index ($VIX) to spike again. Surprisingly, the VIX is flat today and it's been down considerably the past two sessions.
Sector/Industry Focus
The March retail sales report was out this morning and it showed that consumers spent a bit more than expected. We're not seeing that translate into a strengthening retail group, however - at least not yet. Below is a weekly chart of the widely-diversified retail ETF (XRT) and it's rather clear that the downtrend beneath the declining 20-day EMA remains perfectly intact:
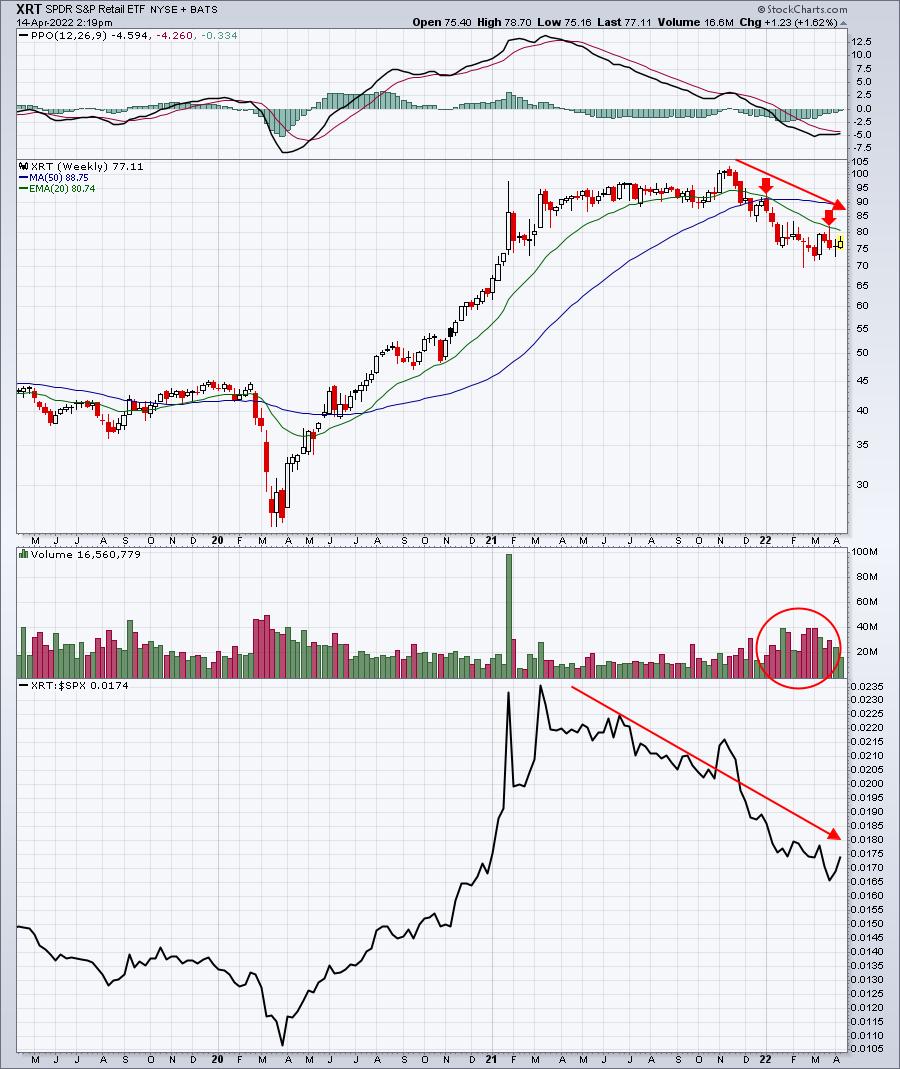
The absolute price downtrend began in November 2021, but the relative strength began deteriorating over a year ago in March 2021. It's hard to imagine consumer discretionary stocks showing a whole of strength until retail stocks show marked improvement. That needs to start with a weekly close back above the 20-week EMA.
ChartLists/Strategies
The ABBV trade off the Strong AD ChartList (SADCL) is paying early dividends after I nearly got stopped out yesterday. I decided to take another stab at a leading stock off our SADCL as well. Arcos Dorados Holding (ARCO) has been a very strong restaurant & bar ($DJUSRU) stock and, after recently printing a negative divergence, it tested its 50-day SMA earlier. I'm looking for it to recover back to its recent price high in the 8.25-8.45 range:
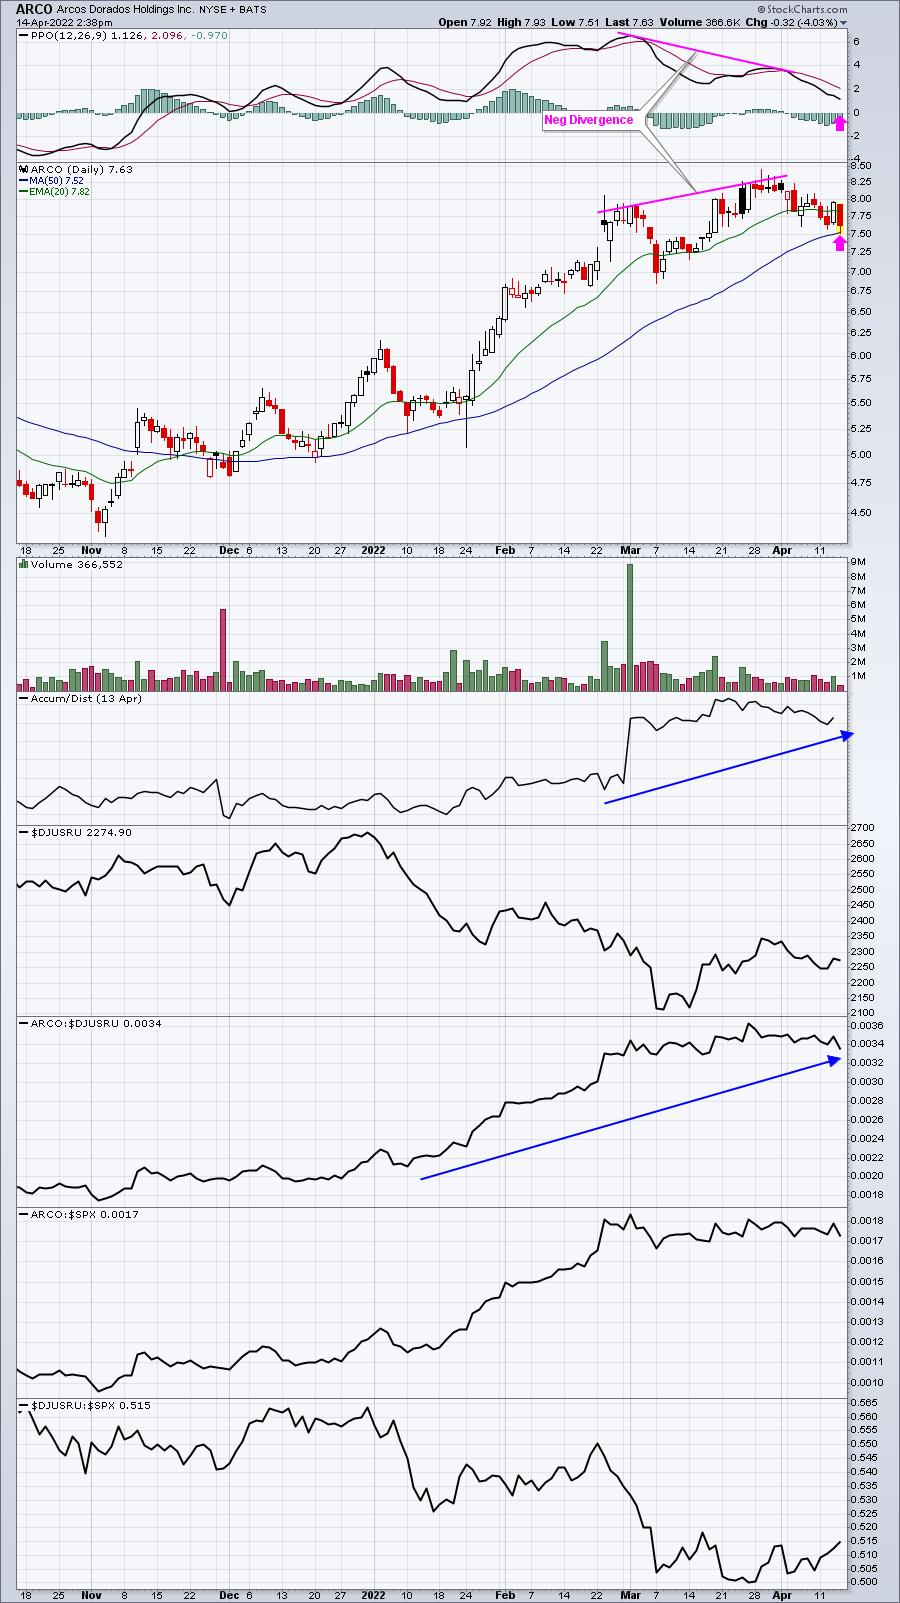
A close below the 50-day SMA could lead to the early-March low at 7.00, so I find the 50-day SMA to be the key closing stop level.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, April 14:
UNH, WFC, MS, GS, C, PNC, USB, STT, ALLY
Monday, April 18:
BAC, SCHW, BK, SYF, JBHT, ELS, PNFP
Economic Reports
Initial jobless claims: 185,000 (actual) vs. 175,000 (estimate)
March retail sales: +0.5% (actual) vs. +0.6% (estimate)
March retail sales less autos: +1.1% (actual) vs. +1.0% (estimate)
February business inventories: +1.5% (actual) vs. +1.3% (estimate)
April consumer sentiment: 65.7 (actual) vs. 58.8 (estimate)
Happy trading!
Tom