
EB Daily Market Report - Monday, May 2, 2022
Executive Market Summary
- Futures were mixed overnight and our major indices opened very close to the flat line
- Selling did pick up throughout the session, with value stocks underperforming today
- Gold ($GOLD, -2.59%) is tumbling today as the U.S. Dollar ($USD) threatens a breakout above multi-year resistance
- Other commodities are mostly higher, led by natural gas ($NATGAS, +3.64%)
- The 10-year treasury yield ($TNX) is up more than 11 basis points, touching 3% for the first time since late 2018
- In a strange twist, communication services (XLC, +1.39%) is rising in the face of higher interest rates and is leading all sectors
- Technology (XLK, -0.23%) and consumer discretionary (XLY, -0.41%) are also trading well on a relative basis
- Meanwhile, defensive groups are selling off today, led by real estate (XLRE, -3.58%), which could be interpreted bullishly
- The Volatility Index ($VIX) moved above 36, before reversing over the course of the past hour; a strong finish by the market could represent another short-term advance upcoming
Market Outlook
Technology (XLK) remains, by far, the largest sector among our 11 sectors, representing more than 28% of the S&P 500. Clearly, its movements will have a tremendous impact on the S&P 500's performance. Here is the latest technical outlook for the group and how it's been performing on a relative basis to the benchmark:
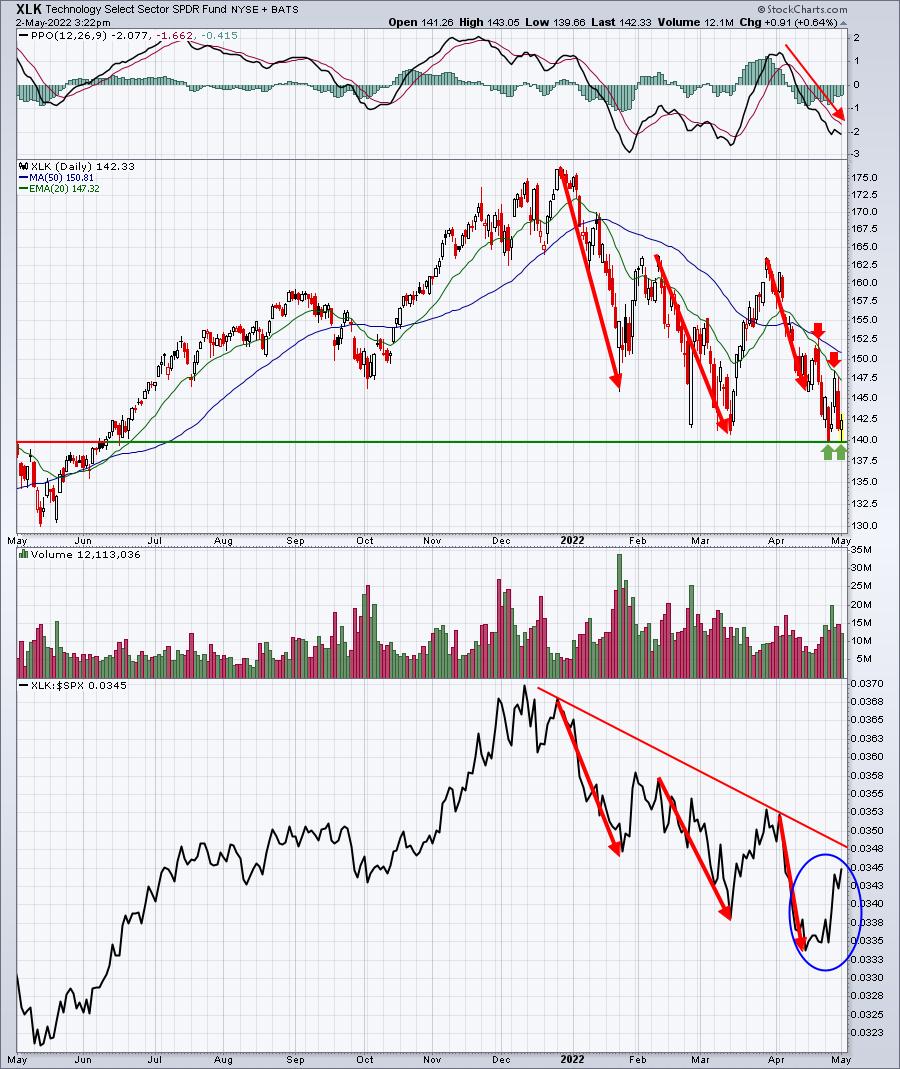
Note that when technology falls, it's usually leading the stock market lower. However, recent back-and-forth action is actually occurring with the XLY:$SPX ratio rising. Is this an initial sign of a bottom approaching? Perhaps. I'll keep monitoring this.
Sector/Industry Focus
Selling is intensifying in the real estate sector (XLRE, -3.58%) as the group has now fallen nearly 10% in just the past two trading sessions. Higher interest rates certainly are not helping. Below shows a key support zone that will soon come under fire:
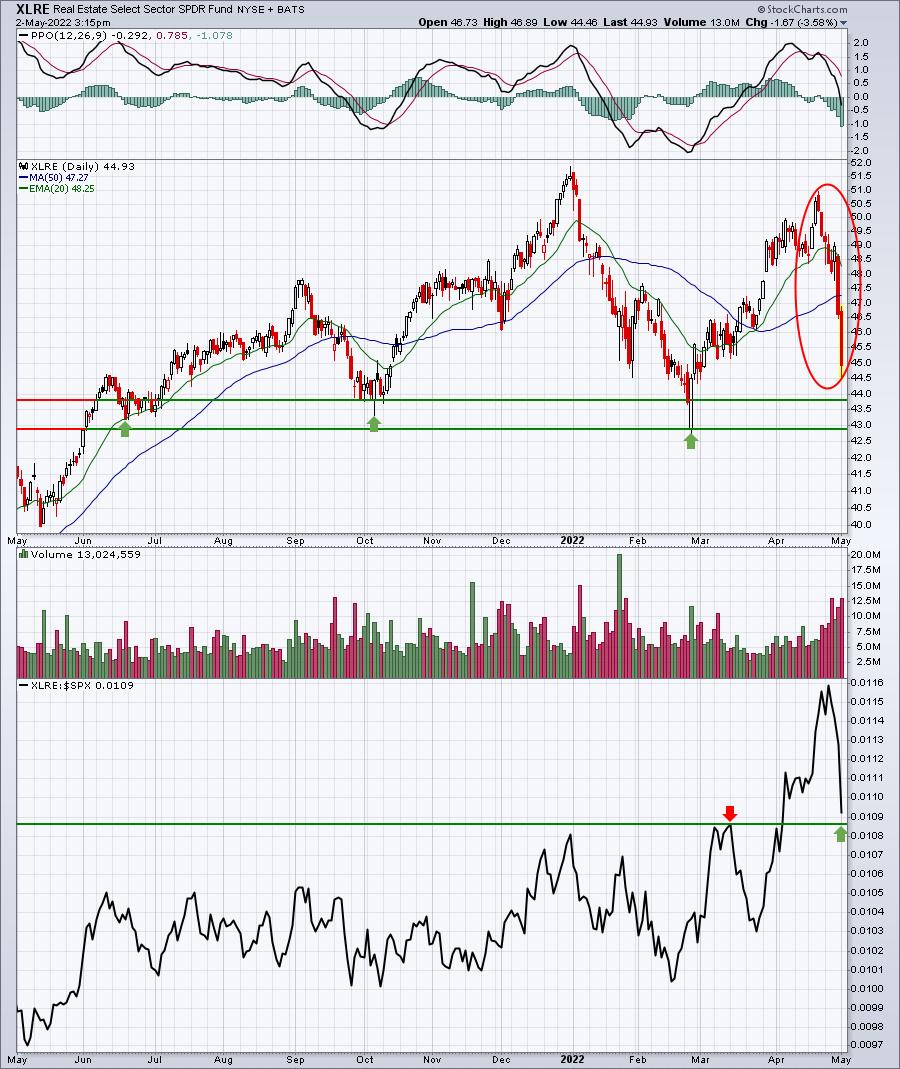
I would be expecting a rebound on both an absolute and relative basis very soon.
ChartLists/Strategies
If we do continue strengthening into the close, a stock like Datadog (DDOG) could represent a short-term buying opportunity as it's trying to reverse at key price support. Just keep in mind that DDOG reports its latest quarterly results before the opening bell on Thursday and ANYTHING goes at that point. Here's the current chart showing the key price support:
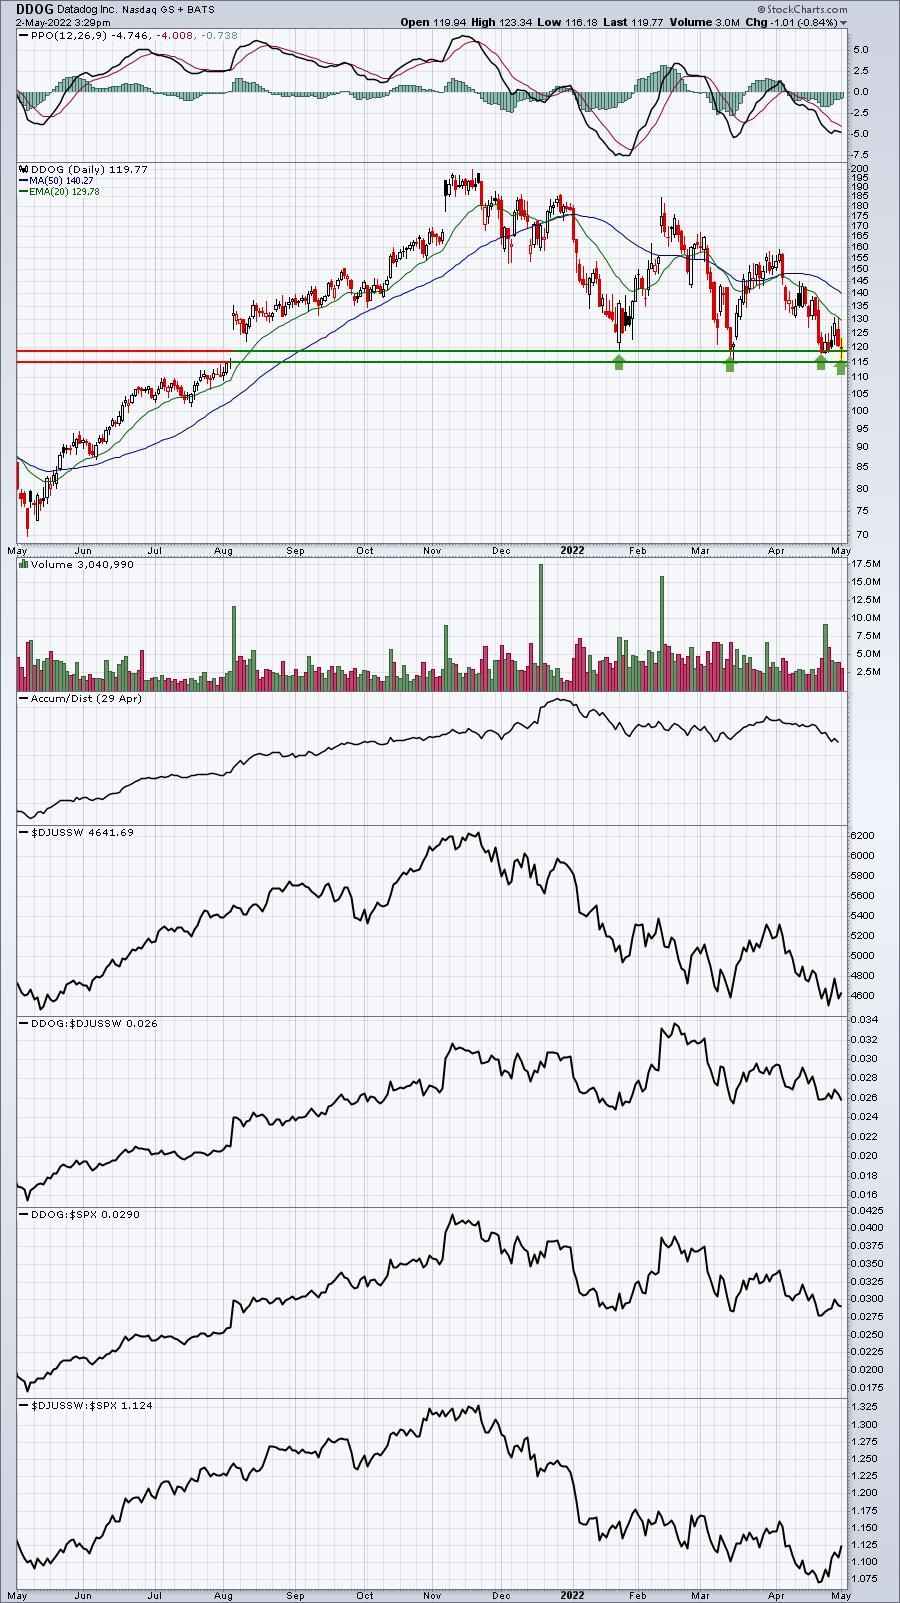
A weak finish today and a breakdown clearly would be bearish. I annotated both recent closing price report lately (near 119) and gap support from August 2021 near 115. If the overall market finishes strong, I wouldn't be surprised by a quick rebound heading into DDOG's earnings report on Thursday. Let's see how we finish today first.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include a few select companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Monday, May 2:
MCO, EPD, NTR, NXPI, WMB, GPN, DVN, ANET, WEC, EXPE, FMX, MOS, CTRA, FANG, ON, ZI, BXP, MPWR, CLX, MGM, FMC, CAR, SEDG, CNA, AIRC, VNO, OHI, AGNC, SAIA, AMG, LEG, VRNS, AMKR, FRPT, OUT, CBT, FN, CHGG, QTWO, CNO, RMBS, RIG, SANM, KMT, ITRI, FSS, MWA, KFRC, BIGC, IPI, CDLX
Tuesday, May 3:
PFE, AMD, ABNB, EL, BP, SPGI, SBUX, PSA, FIS, ITW, ETN, MPC, TRI, AIG, HLT, PRU, WCN, PEG, DD, VRSK, MPLX, BIIB, KKR, ROK, OKE, AME, EXR, CMI, EIX, ZBH, IT, MTCH, MLM, CMS, ZBRA, CNP, CNHI, SWKS, PARA, AKAM, WAT, PKI, PEAK, AMCR, J, QSR, PAYC, BR, YUMC, EXPD, INCY, WLK, CTLT, HWM, CZR, LDOS, JKHY, XP, BEN, REG, TAP, LYFT, HSIC, SCI, AIZ, TEVA, SEE, AGCO, NNN, LEA, STAG, LSCC, VOYA, MASI, ITT, MUSA, INSP, LPX, LFUS, SMG, WK, AQUA, IPGP, RRR, SGRY, OSH, AYX, MSTR, CRUS, ONTO, SABR, LTHM, SPT, REZI, VIAV, HLF, CVLT, OMI, VSH, ARNC, WERN, ATRC, XHR, LGIH, CWH, KAR, FLGT, INFN, VCYT, IAG, ENVA, NVTA, ATEN
Economic Reports
April PMI manufacturing: 59.2 (actual) vs. 59.4 (estimate)
April ISM manufacturing: 55.4 (actual) vs. 58.0 (estimate)
March construction spending: +0.1% (actual) vs. +0.8% (estimate)
Happy trading!
Tom