
EB Daily Market Report - Thursday, May 26, 2022
Spring Special
We are currently running our Spring Special, but it will only last through Monday, May 30th. Don't let it slip by, it's the best deal we offer all year! You can CLICK HERE for more details.
Historical Trends Event
I am hosting a VERY important "Historical Trends" webinar later today at 4:30pm ET. If you EVER trade stocks, you'll want to be aware of the historical trends that I plan to discuss. Here's the link to today's event (room will open at 4:00pm ET):
https://earningsbeats.zoom.us/j/85343950942
If you can't attend live, be sure to check out the recording. I promise it'll improve your trading success.
Executive Market Summary
- Futures were mixed overnight after disappointing guidance from NVIDIA Corp (NVDA, +4.73%)
- The NASDAQ was the opening laggard, but Wall Street used this opening weakness as an opportunity as growth is outperforming value for a second day in a row
- An S&P 500 close today above 4050 would clear its 20-day EMA
- Despite the "risk on" environment today, cryptocurrencies are very weak with etherium ($ETHUSD, -6.43%) particularly so
- Crude oil ($WTIC, +3.15%) is nearing $114 per barrel again, and most other commodities are higher as well
- The 10-year treasury yield ($TNX) is flat after being higher by 4 basis points earlier in the day
- Consumer discretionary (XLY, +4.42%) is leading all sectors, with only real estate (XLRE, -0.02%) in negative territory
- Gambling stocks ($DJUSCA, +6.78%) are among many very strong discretionary industry groups; all 21 industry groups in this sector are higher and only two (toys and business training) are up less than 2%
- The second estimate of GDP was released this morning and it was lowered from -1.3% to -1.5%
- Dollar Tree (DLTR, +21.52%) is surging after reporting its quarterly results, which easily beat expectations
Market Outlook
NVIDIA Corp (NVDA, +5.45%) is doing EXACTLY what I discussed in yesterday's DMR. They reported better results than expected, but did disappoint with light guidance. The initial gap lower was bought from the opening bell. NVDA opened at 160.36 and, at last check, traded just below 180. That's helped to ignite the semiconductor industry ($DJUSSC, +3.92%):
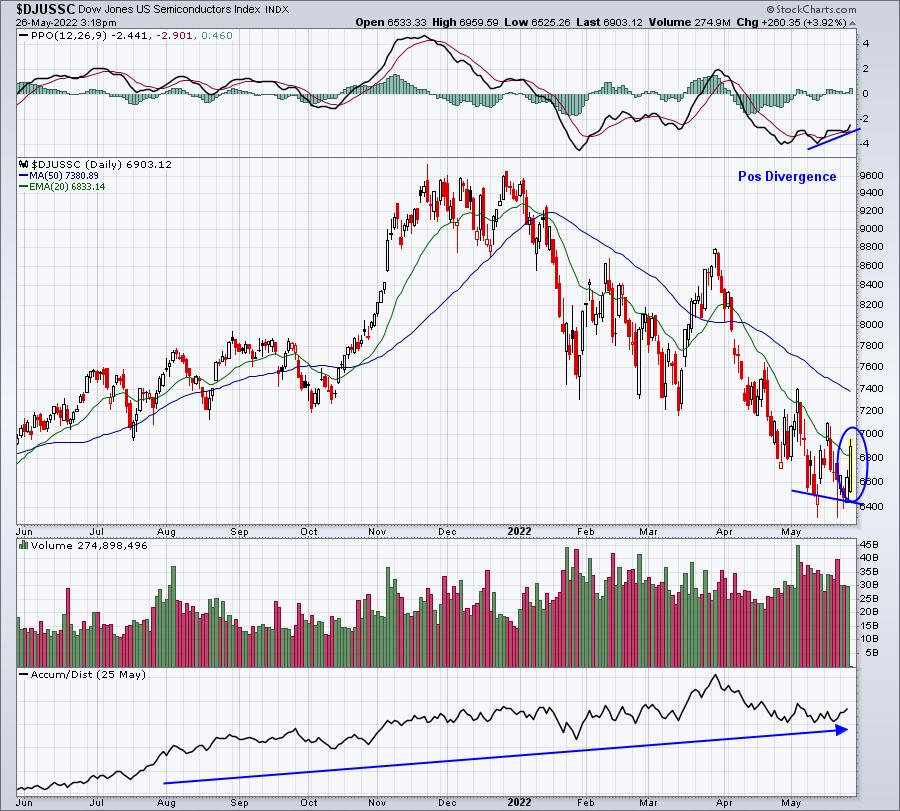
The AD line has been quite strong and today's action, barring a significant final hour decline, will only add to this strength. This is one of the most influential areas of the market. A resumption of the secular bull market will not begin without participation from semis. Like retail yesterday, semiconductors are beginning their "bottoming arguments."
Sector/Industry Focus
Consumer discretionary (XLY, +4.42%) is showing a second consecutive day of absolute and relative strength. It's still got a LOT of work to do to mark a major bottom, but this is a start:
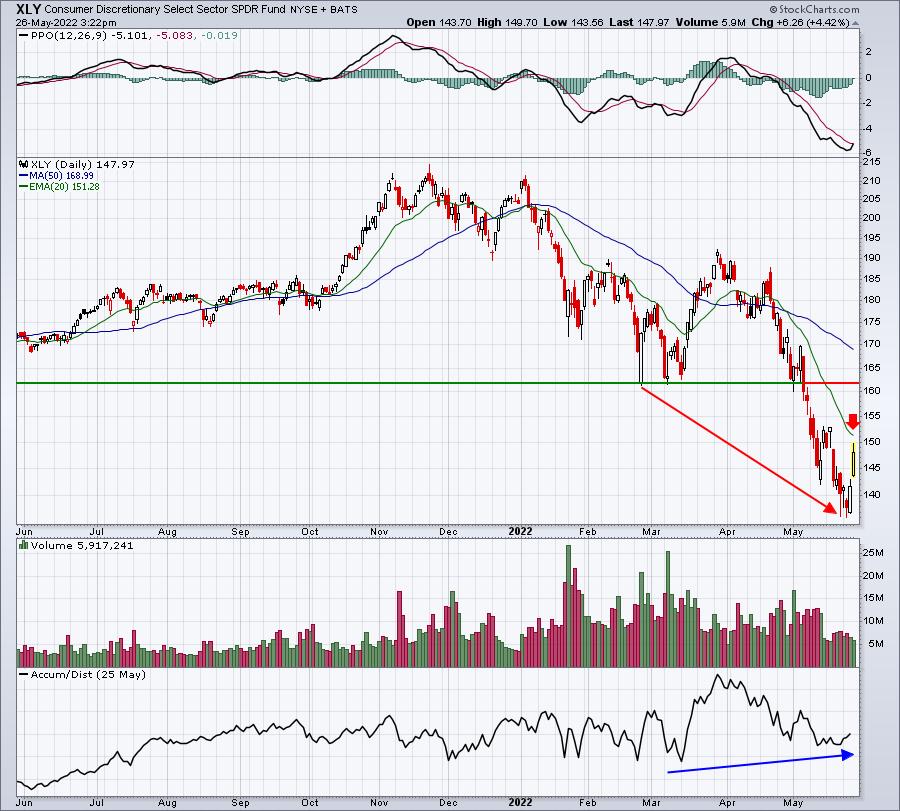
Notice that the AD line is higher at the most recent bottom than it was when the XLY was trading much higher? I do believe Wall Street is happily accepting XLY from those willing to sell at this depressed level. However, we're still not seeing any meaningful relative strength other than these past two sessions. There's more work to be done.
ChartLists/Strategies
From our Strong Earnings ChartList (SECL), here are two stocks finally starting to see some love:
LULU:
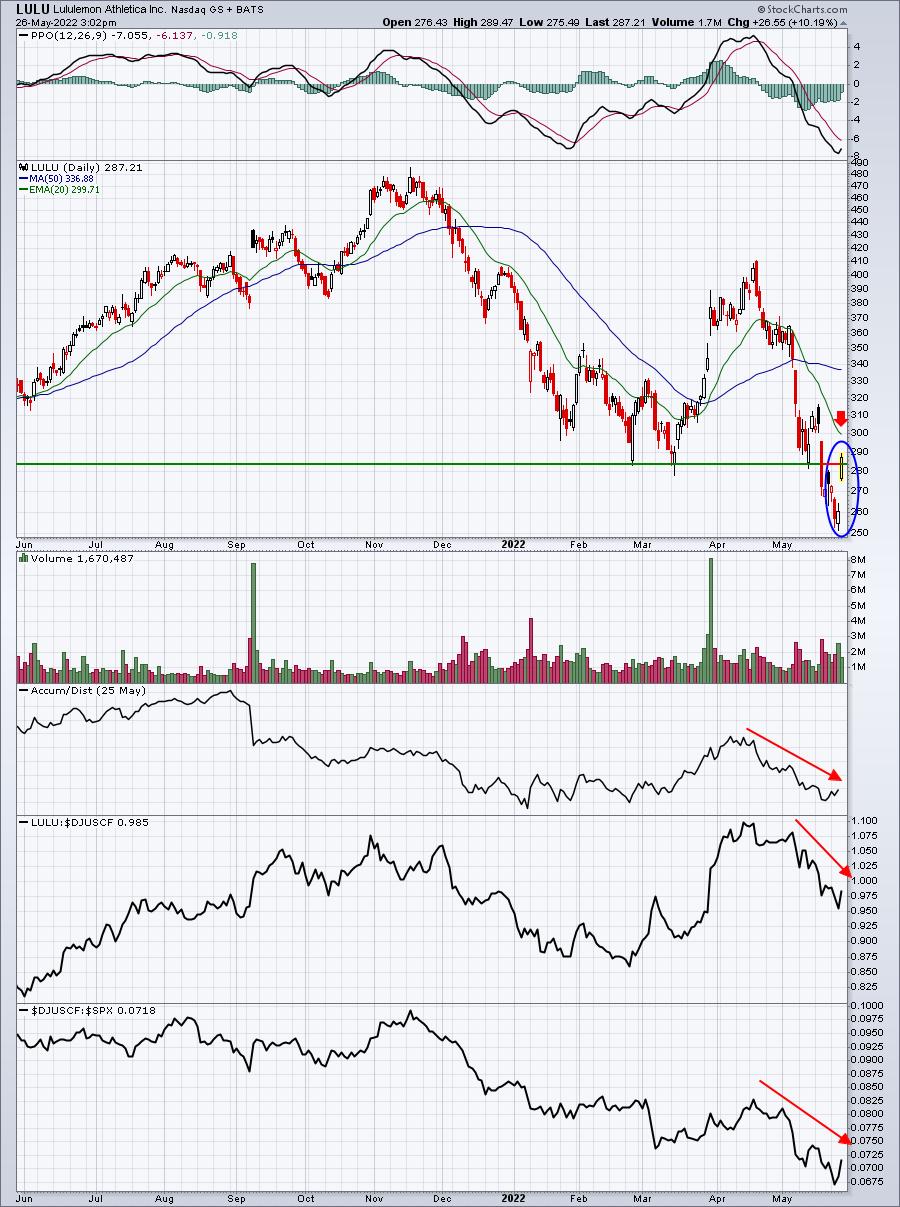
LULU doesn't look great right now, other than the action from yesterday and today. Its relative strength needs improvement, as does its AD line. But this could be the start of a bottoming process. Be careful in the 285-300 range as these two numbers represent price resistance and 20-day EMA resistance, respectively. Another trip lower, however, could set LULU up nicely going forward.
LOVE:
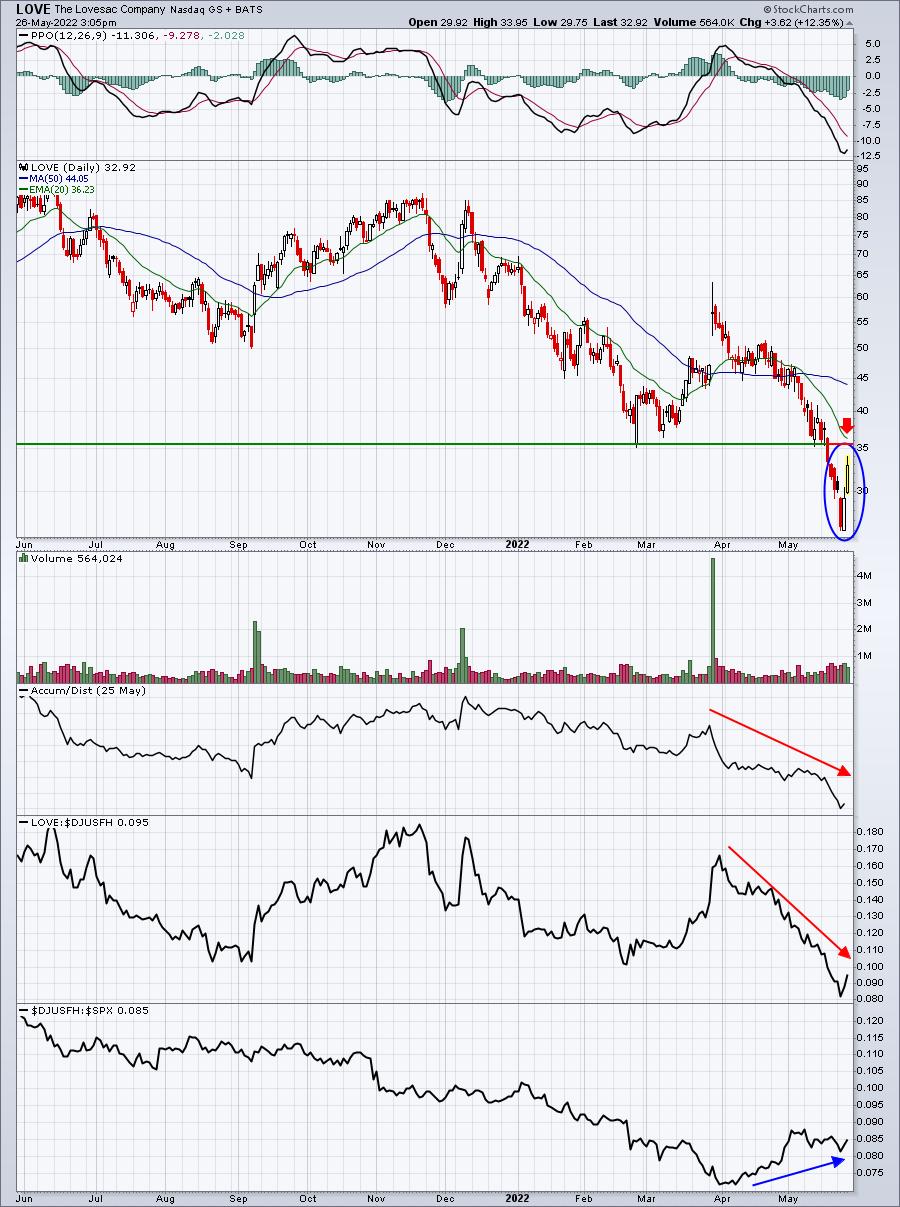
With LOVE, the furnishings industry ($DJUSFH) has started to trend higher relative to the S&P 500 - at least a positive initial start. LOVE has the same overhead issues as LULU. Price resistance and 20-day EMA resistance are in the 35.50-36.25 area.
Earnings Reports
Here are the key earnings reports for the next two days, featuring stocks with market caps of more than $10 billion. I also include several companies with market caps below $10 billion. Finally, any portfolio stocks that will be reporting results are highlighted in BOLD. If you decide to hold a stock into earnings, please understand the significant short-term risk that you are taking. Please be sure to check for earnings dates for any companies you own or are considering owning.
Thursday, May 26:
BABA, COST, RY MDT, TD, VMW, CM, MRVL, DG, BIDU, WDAY, DELL, DLTR, ZS, ULTA, BURL, M, GPS, IQ, FTCH, LGF, GLNG, AEO, JACK, BKE, DOMO
Friday, May 27, 2022:
PDD, CGC
Economic Reports
Q1 GDP (2nd estimate): -1.5% (actual) vs. -1.3% (estimate)
Initial jobless claims: 210,000 (actual) vs. 208,000 (estimate)
April pending home sales: -3.9% (actual) vs. -1.5% (estimate)
Happy trading!
Tom